

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Helicopter Simulator Market to Climb from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 at 6.98% CAGR

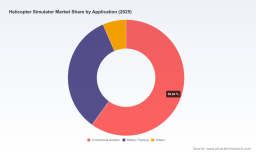
Helicopter Simulator Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive snapshot
PW Consulting’s latest Helicopter Simulator Market report (base year 2025) synthesizes five years of historic performance (2020–2025) with a detailed outlook through 2032. The market has expanded materially since 2020 and is projected to continue growing at a compounded annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. From a strategic planning perspective, this trajectory transforms simulator programs from niche cost centers into scalable training and sustainment platforms that materially affect fleet readiness, instructor staffing models, and supplier selection across civil and defense operators.
Helicopter Simulator Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 is an inflection year. Regulatory shifts, rapid adoption of mixed-reality technologies, and supplier consolidation are converging to create first-mover advantages for operators and vendors who align procurement, certification, and commercial models now.
Helicopter Simulator Market -
Risk-to-opportunity translation: The market’s steady growth trajectory—built on a resilient base established during the previous five years—means decisions made in 2026 about simulator type, certification pathways, and support contracts will influence total cost of ownership and training throughput for the next decade.
Helicopter Simulator Market -
Strategic clarity: For C-suite and operational leaders, the report converts macro growth and competitive dynamics into actionable priorities—procurement timing, technology partnerships, and aftermarket strategies—that preserve optionality while capturing upside from digitalization.
What the report contains (practical, actionable deliverables)
-
Market sizing and forecast: A validated topline series covering 2020–2032, with scenario-based forecasts to stress-test growth assumptions under differing regulatory and technology adoption paths.
-
Demand modelling toolkit: Customizable templates for operators to estimate training demand, simulator seat-hours, instructor staffing and break-even timelines under multiple fleet and utilization scenarios.
-
Certification and regulatory playbooks: Step-by-step guidance on contemporary FAA/EASA pathways, risk mitigations for cancelled or evolving advisory circulars, and a checklist for mixed-reality pre-qualification.
-
Supplier evaluation matrix: Rigorous comparative assessment criteria—technical fidelity, maintainability, upgradeability, IP and software openness, delivery lead times, and aftermarket economics—that buyers can deploy immediately.
-
M&A and partnership maps: Target profiles and diligence checklists for strategic acquisitions, minority investments, and OEM-operator JV structures to accelerate capability acquisition.
-
Commercial templates: Negotiable contract language, service-level benchmarks, and TCO calculators designed for procurement teams to secure predictable lifecycle costs and performance guarantees.
Market dynamics and what’s driving growth
The overall simulator market has shown robust expansion from its 2020 base, with an accelerated pace through 2024–2025 and sustained momentum into the forecast period. The drivers are multifold:
-
Technology substitution: Mixed-reality and high-fidelity visual systems are reducing the marginal cost of scenario complexity and enabling faster certification pathways for certain training objectives.
-
Operator economics: Rising real-flight costs and crew availability pressures are increasing the share of training conducted in simulators, while operators seek scalable, on-site training solutions.
-
Defense and security demand: Modern doctrines emphasizing realistic mission rehearsal have increased investments in mission-specific simulation capabilities.
-
Aftermarket service growth: With higher installed bases and longer lifecycle expectations, service revenues—updates, motion platform maintenance, and scenario libraries—are an expanding value pool for suppliers.
Regulatory & standards landscape — implications for 2026
-
Regulatory flux brings both risk and opportunity. The cancellation of FAA AC 120-63 in April 2026 alters the certification environment for some helicopter simulators, introducing uncertainty for certain device qualification routes but also opening space for manufacturers to propose alternate compliance regimes. Our report provides a navigation map for operators and vendors to re-scope certification programs, reduce rework risk, and accelerate deployment.
-
EASA’s Special Conditions framework and national pre-qualifications are emerging as practical accelerators for mixed-reality solutions; recent pre-qualifications and device pre-approvals demonstrate viable templates to follow.
Competitive landscape — players to watch and strategic moves
The market displays a concentrated supplier structure: the top three companies control a meaningful share of industry revenues, and the top five capture an even larger portion. This concentration creates differentiated routes to scale—either by partnering with established integrators or by targeting underserved niches with modular, lower-cost offerings.
-
CAE Inc. (Montreal): A dominant provider of full-flight devices and Level D-capable platforms, CAE’s portfolio and global service network make it a primary partner for large airlines, OEMs and defense customers. Strategic implication: CAE remains the go-to for turnkey, high-fidelity programs but can be expensive for mid-market operators seeking rapid deployment.
-
Frasca International (Urbana, IL): With a broad line of FTDs, AATDs and CPTS, Frasca is positioned to capture training center and flight school demand that prioritizes cost-effectiveness and reliability. Strategic implication: Frasca is a logical partner for scale-focused operators and regional training networks.
-
ELITE Simulation Solutions (Zurich): Known for FAA- and EASA-certified TH-125 and AS355 models, ELITE’s recent delivery and commissioning of an FAA-certified TH-125 for a law-enforcement unit underscores its operational focus and credibility in public safety markets.
-
Reiser Simulation and Training GmbH (Germany): A leader in mixed-reality integration, Reiser’s pre-qualification of the H145 D3 demonstrates the viability of high-fidelity XR solutions under EASA frameworks.
-
Ryan Aerospace (Gold Coast): By launching an affordable Robinson mixed-reality simulator, Ryan targets the professional training segment with a disruptive price-performance proposition.
-
TRU Simulation + Training (South Carolina) and Helisim GmbH (Germany): TRU’s close alignment with specific OEM platforms, and Helisim’s pre-qualification work for large twin-engine models, make both key partners for OEM-endorsed training ecosystems.
Recent market moves—product launches, certification milestones and localized deliveries—signal that suppliers are diversifying go-to-market approaches: OEM-aligned high-end devices, lower-cost XR-based solutions, and dedicated public-safety and regional operator offerings. The report decodes these tactics into playbooks for both buyers and investors.
Strategic imperatives for 2026
-
Prioritize certification-aligned procurement: Map procurement timelines to certification windows rather than catalog lead times. The cancellation of certain advisory guidance means certification strategy must be an early input to RFPs.
-
Adopt hybrid deployment models: Combine fixed-base simulators for core type-rating activities with mixed-reality units for recurrent and mission-specific training to optimize capital intensity and utilization.
-
Lock in service agreements with clear upgrade paths: Given the value of scenario libraries and software updates, negotiate multiyear, outcome-based SLAs that include upgrade credits and predictable refresh cycles.
-
Invest in instructor competence and digital curriculum: Simulation ROI compounds when paired with optimized curriculum and instructor training—investing in both reduces seat-hour inflation and shortens qualification timelines.
-
Explore consortium approaches for distributed training: Regional operators can pool demand to justify higher-fidelity devices while keeping per-operator costs manageable.
-
Embed simulation strategy into fleet acquisition and sustainment planning: Decisions about aircraft variants, avionics suites, and mission modules should consider simulator compatibility and lifecycle support.
How PW Consulting’s report accelerates execution
Beyond market maps and competitive profiles, our report equips executives with operational tools: customizable demand models, procurement templates, certification roadmaps, and a prioritized list of vendor diligence questions. For private equity and corporate development teams, we provide an M&A playbook that identifies thinly served niches and value-creation levers—service expansion, software monetization, and geographic channel development—that have the highest projected IRR given market growth and concentration dynamics.
Conclusion — decision-ready intelligence for 2026
As the helicopter simulator market transitions from tactical displacement to strategic capability, 2026 will be a decisive year for those who align procurement, certification and commercial models with emergent technology and regulatory realities. With an industry CAGR of 6.98% underpinning continued expansion through 2032 and a market structure where the top vendors hold meaningful share, the winners will be those who convert macro growth into repeatable, service-driven revenue streams while de-risking certification and delivery timelines.
To access the full dataset, regional and application-level segmentation, proprietary vendor scoring, and the suite of decision-support tools described here, visit our official report page. The report intentionally preserves certain granular segment outputs for subscribers—ensuring you receive the depth required to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Helicopter Simulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com