

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Engineering Tech Center Market to Grow from USD 145 Million in 2025 to USD 203 Million by 2032 at a 5.25% CAGR

PW Consulting Releases Strategic Market Brief: Engineering Tech Center Market — Critical Guidance for 2026 Decision-Making
Executive summary
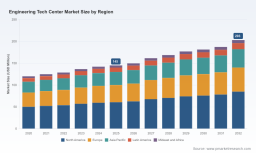
PW Consulting today published a focused market brief, the Engineering Tech Center Market Report (base year 2025, historical window 2020–2025, forecast 2026–2032). Built for senior leaders making capital allocation, site strategy, and product development decisions in 2026, the brief synthesizes quantitative market modeling with on‑the‑ground facility assessments and vendor benchmarking. Our core forecast shows the market expanding from approximately USD 145 million in 2025 to an estimated USD 203 million by 2032 — a compounded annual growth rate of roughly 5.25% — underscoring steady, investment‑grade growth driven by product innovation cycles, localized prototyping needs, and increased demand for controlled testing environments.
Engineering Tech Center Market
Why this report matters for 2026 strategic planning
-
Timing of investment: 2026 is a hinge year for companies that must decide between centralized lab consolidation and distributed “edge” Engineering Tech Centers designed for rapid prototyping and customer co‑development. Our analysis quantifies the valuation implications of each approach and maps the operational tradeoffs that matter most to executive boards.
Engineering Tech Center Market -
Funding and portfolio choices: With predictable mid‑single digit CAGR and identifiable pockets of premium margin activity, boards and PE sponsors can prioritize investments that accelerate time‑to‑customer and reduce NPI cycle time without materially increasing fixed overhead.
Engineering Tech Center Market -
Talent and regulatory planning: The brief links facility requirements to talent sourcing strategies and regulatory exposures that tend to surface as Tech Centers scale from pilot to production support roles.
What you’ll find in the report — practical, decision‑ready content
This is deliberately an operationally focused study designed to move leaders from analysis to action. Highlights include:
-
Investment playbook: step‑by‑step decision matrices for greenfield versus retrofit Tech Centers, including CapEx/Opex modelling templates and sensitivity scenarios tailored to different product types (optical, electro‑optical, digital visualization).
-
Site selection framework: a scoring model that blends accessibility to talent, supply‑chain proximity, real estate costs, utility and permitting risk, and time‑to‑operational readiness.
-
Facility design and layout templates: sample lab footprints (cleanroom gradings, test bays, collaborative demo spaces), equipment lists, and throughput simulations that translate strategic intent into square‑foot and staffing plans.
-
Operational playbook: SOPs for rapid prototyping workflows, test protocol checklists, quality gates, and supplier integration guidelines to compress NPI timelines while safeguarding IP.
-
Commercialization and customer engagement models: go‑to‑market templates for using Tech Centers as sales accelerators, co‑development hubs, and training centers.
-
Risk and compliance toolkits: a regulatory matrix, hazardous materials handling checklist, and market entry considerations for defense‑adjacent optical and imaging technologies.
-
M&A and partnership playbook: diligence checklists and integration roadmaps for bolt‑on acquisitions of lab assets, technology license arrangements, and strategic alliances.
Methodology and confidence
The report blends quantitative market-sizing with qualitative validation. Key inputs include: proprietary revenue modeling (reporting in USD millions), primary interviews with facility operators and technology buyers, on‑site assessments of exemplar Tech Centers, equipment vendor benchmarks, and scenario analysis across alternative adoption curves. We deliberately use a base year of 2025 and a forecast horizon through 2032 to align with typical capital planning cycles and to support multi‑year budgeting decisions.
Competitive landscape — who to watch and why
The Engineering Tech Center market exhibits moderate concentration; top three firms account for a material but not dominant share, while the top five capture roughly half of industry revenue—an environment that rewards both specialized niche players and scale‑enabled platforms. Our qualitative analysis identifies two distinct strategic archetypes that are particularly instructive for 2026 planning:
-
High‑specialization, mission‑driven facilities: companies that invest in deep lab capabilities aligned to a narrow product class (for example, precision electro‑optics for defense and high‑accuracy imaging). These operators compete on technical differentiation, integrated testing capabilities, and IP protection strategies.
-
Customer‑facing collaboration centers: vendors and OEMs that design Tech Centers primarily to accelerate adoption, training, and demonstration for commercial customers. These centers emphasize immersive demo spaces, training curricula, and rapid customization pipelines.
Recent facility investments — practical implications
Two recent facility openings illustrate the strategic calculus that executives should consider when evaluating their own Tech Center plans.
-
EOTECH (Plymouth, Michigan) inaugurated a new Engineering Tech Center in Orofino, Idaho in early 2025. The facility features a purpose‑built optics lab with cleanroom capabilities and precision test gear intended to shorten R&D cycles for weapon sights and camera systems. For competitors and partners, the move signals a commitment to in‑house prototyping and vertically integrated testing — a model that raises the bar for suppliers that rely on legacy external labs.
-
Vision Engineering Ltd (Send, UK) launched a West Coast Tech and Training Center in Irvine, California, also in 2025, focused on immersive visualization and digital microscopy demonstrations. The center emphasizes customer co‑development and hands‑on training with the latest product portfolio. This underscores a contrasting strategy: using Tech Centers to drive adoption and product stickiness rather than to centralize complex manufacturing testing.
Both examples highlight a central strategic choice: prioritize deep technical testing vs. prioritize customer engagement. Many mid‑market players will pursue hybrid models, but the path chosen has immediate capex, talent, and partnership implications that we map in the report.
Market dynamics and strategic implications
-
Structural growth with pockets of premium: Moderate market expansion at roughly 5.25% CAGR suggests that well‑timed investments can be accretive if they capture adjacent service revenue or improve product commercialization velocity.
-
Fragmentation creates opportunities: With a meaningful share held by specialized players, there are acquisition and partnership opportunities for companies seeking rapid capability build‑out without incurring full greenfield costs.
-
Operational complexity is underestimated: Our fieldwork shows that the hidden costs in facility qualification, staffing, and certification frequently extend payback timelines unless managed with explicit gating and milestone economics.
Actionable recommendations for 2026
-
Run a defend vs. expand decision: Use our CapEx/Opex template to model a defend‑or‑expand scenario for each product line in 60–90 day decision cycles. Prioritize experiments that demonstrate measurable reductions in NPI lead times.
-
Adopt a two‑tier hub strategy: Consider a compact central lab for high‑complexity testing paired with regional demo/validation hubs to accelerate sales and shorten feedback loops. The report provides a decision matrix to quantify this tradeoff.
-
Lock in supplier roadmaps early: Negotiate equipment and service contracts with performance SLAs tied to throughput and qualification timelines to protect against backlogs that can derail go‑to‑market launch plans.
-
Embed scalability criteria: Design facilities with modularity in mind so they can pivot between R&D, pilot production, and customer demonstration without major rework.
How to use this brief and where to access detailed datasets
This market brief is intentionally positioned as a high‑value preview: it outlines core forecasts, strategic frameworks, and operational checklists that senior teams can act on immediately while withholding select granular segment tables and regional/application breakdowns that form the basis for executable site and investment decisions. The full report includes comprehensive, downloadable models, regional and application splits, facility benchmarking data, and appendices with interview summaries and sample contractual terms.
To download the complete report, view Excel modeling workbooks, and access the proprietary benchmarking dataset, please visit our report page. The full dataset is available to subscribers and corporate clients who require the granular inputs for budgeting, M&A, and site selection exercises.
Closing perspective
Engineering Tech Centers are becoming a strategic lever: not merely a line item on an operations budget but an active part of product strategy and customer engagement. With predictable mid‑single digit growth and evolving competitive dynamics — including targeted investments from both equipment specialists and customer‑facing OEMs — 2026 is the year to convert strategy into tangible assets or strategic partnerships. PW Consulting’s Engineering Tech Center Market Report equips leaders with the frameworks and templates to do exactly that, while preserving the granular datasets that will inform definitive capital and partnership decisions.
For detailed analysis of this topic, please visit the official page: Engineering Tech Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com