

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Press Machine Market to Surpass USD 20.3 Billion by 2032, Expanding at a 5.8% CAGR

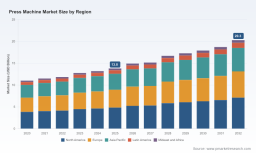
Press Machine Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
PW Consulting is pleased to release an executive briefing drawn from our comprehensive Press Machine Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032). As manufacturing leaders finalize 2026 capital allocation and supply-chain strategies, this briefing highlights the report’s strategic value: rigorous market sizing, trend-forward scenario planning, and actionable playbooks that translate industry insight into board-level decisions. We present high-level findings and strategic recommendations here — detailed segmentation tables, vendor scorecards, and modelled scenarios are intentionally reserved for the full report to preserve competitive utility and to drive direct engagement.
Press Machine Market
Why this report matters for 2026 decision-makers
The press machine market has emerged from a period of steady recovery into a structurally evolving sector. Our analysis shows the market expanding from a post-pandemic baseline in 2020 to a materially larger industry by 2025, and continuing to grow through our forecast window. Specifically, total industry value rose consistently during 2020–2025 and, under PW Consulting’s baseline forecast, is projected to expand at a compound annual growth rate (CAGR) of 5.8% through 2032. This trajectory reflects an intersection of cyclical capital expenditures and durable, secular drivers — electrification and lightweighting in transport, reshoring of precision manufacturing, and accelerating adoption of digital process controls — which together create a multi-year investment runway.
Press Machine Market
Core dynamics shaping 2026 strategy
-
Technology substitution and product differentiation: Servo-driven systems and advanced control platforms are reshaping competitive advantage. Buyers now evaluate press procurements through a total-cost lens that places a premium on energy efficiency, repeatability, and integration with factory automation platforms.
Press Machine Market -
Aftermarket and service monetization: With presses being capital-intensive, vendors are competing on lifecycle economics. Service agreements, retrofits, remote diagnostics and spare-parts availability are becoming decisive procurement criteria, and they also represent high-margin revenue streams for machine builders.
-
Concentration and supplier dynamics: The market exhibits mid-level concentration, where the largest global suppliers capture a substantial share of installed capacity while a diverse long tail serves niche and regional needs. This dynamic creates predictable strategic choices for buyers: standardization around a few OEMs to secure scale efficiencies, or diversification to mitigate supplier risk.
-
Trade-show and product-cycle indicators: Recent industry calendar activity — including strategic rebranding and product demonstrations by major OEMs and a persistent presence at major trade events — signals that vendors are prioritizing platform upgrades and partnerships to differentiate in automation and digital services.
What the full PW Consulting report contains (practical, decision-grade content)
-
Market sizing and validated growth scenarios: An audited top-down and bottom-up market model covering 2020–2025 historicals and 2026–2032 forecasts, with sensitivity cases for high/low capex and demand shocks.
-
Buy-side playbooks: Procurement templates that translate market intelligence into RFP language, evaluation scorecards (technical, TCO, service), and tender timetables aligned to supplier lead times and long-lead components.
-
Sell-side strategies: Commercial playbooks for OEMs and integrators addressing portfolio prioritization (new machines vs retrofit), aftermarket monetization, and channel structuring to optimize lifetime value.
-
Technology and CapEx roadmaps: Comparative assessments of mechanical, hydraulic and servo-based platforms — focusing on control architectures, energy profiles, die-handling integration, and retrofit pathways that minimize production disruption.
-
Vendor dossiers and competitive gaps: In-depth company profiles, capabilities maps, M&A radar, and partner-fit assessments to support alliance and sourcing decisions. (Note: granular segmentation tables and per-vendor market shares are available in the full report only.)
-
Scenario planning and stress tests: Playbooks for supply-chain disruption, policy shocks (tariffs, content rules), and demand pivot scenarios with recommended tactical responses and contingency budgets.
Competitive landscape — strategic read for 2026
Our vendor analysis concentrates on leading global OEMs and innovative regional specialists. Rather than publish proprietary market shares in this briefing, we provide qualitative differentiation and strategic implications for corporate decision makers.
-
Schuler Group / ANDRITZ Schuler (Germany) — Following the March 2025 rebranding to ANDRITZ Schuler, the company has signalled a stronger emphasis on integrated forming and handling solutions for automotive and heavy industry. For buyers, this means a compelling proposition when seeking end-to-end systems with strong integration competence — especially for high-volume production lines where co-optimization of press and downstream automation reduces TCO.
-
AIDA (Japan) — AIDA continues to leverage breadth in mechanical and servo stamping solutions and has been active at major trade events. Their value proposition rests on a long track record of reliability and a clear channel for global support — a key consideration for multi-site manufacturers standardizing across geographies.
-
Komatsu (Japan) — Strong in progressive and transfer applications, Komatsu’s engineering depth in sheet-metal cutting and stamping technologies offers advantages in high-mix environments where die complexity and throughput balance are important.
-
Macrodyne Technologies (United States) — Macrodyne’s specialization in custom servo and hydraulic presses with turnkey automation positions it as a preferred partner for large OEMs and tier suppliers demanding bespoke line solutions and on-site engineering support.
-
Wickert Maschinenbau (Germany) — Known for high-precision hydraulic systems for deep drawing and aerospace applications, Wickert is an example of a technology-driven niche player where tolerance and process control command a price premium.
-
MULTIPRESS, Inc. (United States) — With recent product updates and ongoing trade-show engagement, MULTIPRESS remains relevant for buyers seeking proven custom hydraulic solutions and strong retrofitting capability.
-
Beckwood Industries & MetalPress Machinery (United States) — Both firms illustrate the strong North American supplier ecosystem for hydraulic and servo systems, with Beckwood notable for complete press systems and MetalPress for automation integration within regional production networks.
Recent tactical indicators (what we watched in 2025–2026)
-
March 2025: Schuler’s rebranding to ANDRITZ Schuler — signals consolidation of systems-level offerings and a strategic focus on automotive forming lines.
-
Throughout 2025: Active trade-show participation by multiple OEMs, including demonstrations at major regional shows — indicating a product refresh cycle and intensifying competition around digital capabilities and energy efficiency.
-
March 2026: MULTIPRESS updates public technical documentation — reflects an ongoing upgrade cadence among mid-sized suppliers catering to retrofit and custom projects.
Implications for procurement, operations, and corporate strategy in 2026
-
CapEx sequencing: Defer or accelerate? Our modelling suggests that organizations with existing assets that can be retrofitted for control upgrades and energy optimization should prioritize targeted retrofits in 2026 to capture rapid ROI, while greenfield capacity expansion should be staged to align with demand scenarios and component lead times.
-
Vendor selection: Prioritize lifecycle economics over headline price. Formalize TCO metrics in supplier evaluations and require transparent SLAs and spare-part roadmaps as part of contract awards.
-
Digital and service strategies: OEMs and integrators must commit to recurring-revenue models through enhanced service offerings; buyers should negotiate remote-monitoring clauses and joint continuous-improvement programs linked to performance KPIs.
-
Risk management: Diversify supplier exposure across OEM types (global integrators vs regional specialists) to balance lead-time resilience, local serviceability, and technological fit.
Actionable takeaways — what executives must do now
-
Commission a 90-day CapEx triage: classify presses by retrofit potential, remaining useful life, and strategic criticality to prioritize 2026 spend.
-
Update procurement scorecards to include digital compatibility, remote service capability, and spare-parts continuity — require these as contractual deliverables for all major equipment purchases.
-
Engage with two or three shortlisted OEMs on pilot projects to validate retrofit savings and digital integration before committing to fleet-wide rollouts.
-
Embed scenario-based stress tests into the 2026 budget cycle to quantify the impact of supply interruptions and demand variance on both CapEx and maintenance budgets.
How to obtain the full report and analytical assets
This briefing is an executive preview. PW Consulting’s full Press Machine Market report includes the detailed segmentation tables, vendor market shares, downloadable Excel models, and procurement templates that corporate and investor clients will need to operationalize these insights. Given the commercial sensitivity of granular segment-level data, those annexes are reserved for report purchasers and subscriber clients. Visit PW Consulting’s research portal to access the full package, obtain licensing for internal use, or schedule a private briefing with our industry practice team.
PW Consulting’s Press Machine Market report is designed to be a practical, decision-grade resource for 2026: it combines audited historicals, defensible forecast scenarios, and hands-on playbooks to help manufacturers, OEMs and investors convert market signals into measurable outcomes. For organizations that must balance CAPEX discipline with competitiveness, the report provides the frameworks and vendor intelligence needed to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Press Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com