

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Lab Balance Market to Reach USD 3.25 Billion by 2032

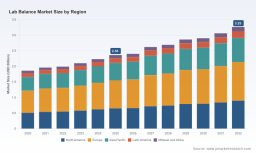
Lab Balance Market 2026: Strategic Imperatives from PW Consulting’s Lab Balance Market Report
PW Consulting today releases a focused preview of its Lab Balance Market report, offering senior executives, procurement leaders, and R&D heads a high-confidence strategic compass for decisions in 2026. The global lab balance market—anchored in a detailed 2020–2025 historical analysis and a 2026–2032 forecast—has moved from USD 1.85 Billion in 2020 to USD 2.36 Billion in 2025 and is projected to reach approximately USD 3.25 Billion by 2032, representing a forecast compound annual growth rate (CAGR) of roughly 4.7% across the outlook period. This release highlights the practical implications of those trends while intentionally withholding the granular segment-level data to encourage direct engagement with the full report and underlying models.
Lab Balance Market
Why this matters for 2026 decision-making
2026 is an uncommon inflection year for laboratory measurement equipment. Regulatory changes, accelerating digital workflows, and concentrated vendor dynamics combine to transform procurement, validation, and service economics. Organizations that treat lab balances as transactional consumables risk non-compliance, downtime, and surprise capital requirements. By contrast, teams that align procurement strategy with site-specific measurement uncertainty, lifecycle service models, and data integrity expectations will unlock lower total cost of ownership and faster regulatory acceptance.
Lab Balance Market
Market trajectory and what drives it
-
Measured, resilient expansion: The market has exhibited steady recovery and growth since 2020, reflected in the rise from USD 1.85 Billion to USD 2.36 Billion by 2025, and a forecast path to roughly USD 3.25 Billion by 2032. Underneath this topline increase are two durable forces: regulatory-driven equipment refresh cycles in regulated industries, and modernization investments in research and manufacturing labs.
Lab Balance Market -
Regulation as a demand accelerator: Revised pharmacopeial and regulatory expectations have created a near-term compliance wave that affects purchase timing, specification stringency, and qualification budgets.
-
Technology and services convergence: Advances in sensor design, electromagnetic compensation technologies, connectivity, and on-board diagnostics are shifting vendor competition away from price-only strategies toward integrated hardware + software + services offerings.
Regulatory inflection points and operational impact
-
USP and regional pharmacopeias: The revisions to USP Chapters 41 and 1251—finalized in mid‑2025 and effective February 1, 2026—redefine minimum sample weight determination by tying it to site-specific repeatability rather than manufacturer catalog claims. European Pharmacopoeia Chapter 2.1.7 remains an active compliance baseline in Europe. These changes have immediate consequences for qualification protocols, acceptance testing, and supplier claims validation.
-
Enforcement and traceability: Regulatory bodies, including the FDA under existing statutes, are treating the revised chapters as required for drug manufacturing and quality control processes. At the same time, ISO/IEC 17025-accredited calibration certificates and recognized procedures (EURAMET cg-18, ASTM E898) remain the operational standard for traceability and estimating measurement uncertainty.
-
Practical consequences: Expect increased spend on site-specific repeatability studies, expanded qualification packs, more frequent accredited calibrations, and heightened scrutiny of vendor documentation and software audit trails.
Competitive landscape: concentration and vendor positioning
The lab balance market is moderately concentrated: the three largest vendors account for a significant share of market revenue, and the top five firms represent an even larger portion, creating structural advantages around scale, distribution reach, and service networks. That concentration changes negotiation dynamics for mid‑market buyers and elevates the importance of supplier risk management for large enterprises.
-
Sartorius (Göttingen, Germany) — Sartorius has positioned its Cubis II modular platform as a compliance-first solution. The company emphasizes configurability and pharma‑grade qualification support, aligning product development to the revised USP and pharmacopoeial demands. Recent product and regulatory milestones underscore a push to integrate validation workflows directly with hardware capabilities.
-
Mettler‑Toledo (Columbus, Ohio, USA) — Mettler‑Toledo’s XPR, MS‑TS, and MR series focus on electromagnetic force compensation and robust internal adjustment features, with recent portfolio consolidation and upgrades emphasizing connectivity and sensor improvements. Their product strategy targets laboratories that prioritize repeatability, automated adjustment, and compatibility with updated pharmacopeial requirements.
-
OHAUS Corporation (Pine Brook, New Jersey, USA) — OHAUS emphasizes operational ergonomics—motorized leveling, touchless sensors, static mitigation features—and automated calibration to streamline high‑precision workflows in teaching and industrial environments.
-
RADWAG (Poland) — RADWAG’s recognition in independent awards for moisture analyzers and industrial scales signals a reputation for performance and value in both lab and industrial contexts. Awards and product recognition serve as a trust signal for procurement teams weighing non‑legacy suppliers.
-
A&D Company (Tokyo, Japan) — A&D focuses on precision balances with integrated ionization and fanless designs to control static in demanding environments, aligning products to labs where environmental control is limited or variable.
Together, these vendor strategies reveal two competing architectures: highly configurable, compliance-oriented platforms designed for regulated pharmaceutical and biopharma customers versus streamlined, cost‑efficient balances optimized for academic, environmental, and food testing labs. Both types will coexist; the choice depends on site risk profile, regulatory exposure, and lifecycle cost tolerance.
Actionable recommendations for 2026
-
Run site‑level repeatability audits now: Because minimum sample weight and acceptance criteria are now tied to site performance, procurement should not rely on catalog specifications alone. Conduct rapid repeatability studies across representative bench locations to inform acceptance thresholds and MZW calculations.
-
Reframe procurement as lifecycle procurement: Prioritize vendor ecosystems that include qualification documentation, secure connectivity, and predictable calibration schedules with ISO/IEC 17025 traceability. Short‑term capex savings can be eclipsed by the cost of re‑qualification and compliance failures.
-
Segment investment by risk profile: Reserve premium, configurable units for processes with the highest regulatory exposure and sample criticality; deploy validated, high‑value economy units in low‑risk applications. Our full report models multiple buy‑mix scenarios and TCO outcomes to inform this phasing—detailed tables and supplier scorecards are available in the complete dataset.
-
Strengthen calibration and service partnerships: Build formal SLAs with accredited calibration providers and ensure calibration certificates and uncertainty budgets are ingested into asset management systems for audit readiness.
-
Prepare for integration and data governance: As balances gain connectivity, include them in cybersecurity and data integrity assessments. Look for vendor support for electronic records, audit trails, and secure transfer protocols to meet 21 CFR Part 11 expectations where applicable.
-
Stress‑test supplier continuity: Given market concentration, include alternate‑supplier strategies and evaluate cross‑qualification paths to avoid lengthy qualification cycles in the event of supplier disruption.
What the PW Consulting report delivers (operational highlight)
The full Lab Balance Market report offers the toolkit senior leaders need to translate macro trends into executable plans. Key practical deliverables include:
-
Comprehensive market sizing and a seven‑year forecast with sensitivity scenarios aligned to regulatory and tech adoption inflection points;
-
Vendor scorecards that assess product features, compliance readiness, service footprint, and integration maturity;
-
Procurement playbooks and TCO models for phased replacement versus opportunistic upgrades;
-
Calibration and qualification cost models that map to ISO/IEC 17025, EURAMET, and ASTM best practices;
-
Decision matrices for lab managers to select balances by risk class, including sample‑weight driven acceptance criteria templates;
-
Market concentration analysis and supplier risk frameworks that inform sourcing and M&A diligence.
How to use this preview
Consider this release a strategic preview: it outlines the regulatory, competitive, and operational contours that will shape vendor selection and capital planning in 2026. We intentionally withhold detailed segment share tables, regional and application‑level splits, and granular price curves to preserve the integrated, model‑driven value of the full report. Those datasets are essential when constructing procurement RFIs, calibrating qualification budgets, or designing an MRO plan tied to site‑specific uncertainty metrics.
Next steps for leaders
-
Schedule a PW Consulting briefing to run your site‑level repeatability assessment against our models;
-
Request the full report and dataset to access supplier scorecards, regional channel maps, and the downloadable qualification templates required for regulatory submissions;
-
Engage with our advisory team for bespoke procurement roadmaps or to stress‑test vendor contracts under revised pharmacopeial requirements.
PW Consulting’s Lab Balance Market report is designed to convert market intelligence into executable actions. For compliance‑driven organizations and methodically run research labs alike, the right balance decision in 2026 will reduce audit risk, lower lifetime costs, and accelerate time‑to‑value. Visit our website to access the full report, proprietary models, and vendor datasets. Detailed segment and pricing data are available exclusively in the full report to support procurement and validation teams with audited inputs necessary for regulatory filings and capital planning.
For detailed analysis of this topic, please visit the official page: Lab Balance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com