

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: UV Lasers Market Poised to Expand at 8.7% CAGR as Demand from Semiconductor and Medical Sectors Surges

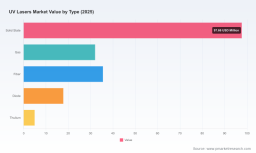
UV Lasers Market 2026: Strategic Signals for Executive Decision-Making
Executive snapshot
As a strategic advisor at PW Consulting, I present a high-level briefing of our latest UV Lasers Market study (base year 2025). The market has expanded from approximately USD 137.0 Million in 2020 to USD 188.0 Million in 2025 and is forecast to accelerate through the coming decade, reaching roughly USD 338.0 Million by 2032. This trajectory represents a compound annual growth rate of about 8.7% across the forecast horizon. For 2026 planning cycles, these macro dynamics convert into discrete strategic imperatives for product roadmap prioritization, capacity investment, channel strategy, and regulatory compliance.
UV Lasers Market
Why this matters for 2026 strategy
- Predictable growth envelope: Sustained mid-single-digit to high-single-digit CAGR gives boards the confidence to underwrite multi-year R&D programs targeted at UV-specific applications (deep UV lithography, micromachining, precision marking) while preserving optionality for faster pivots.
- Increasing technical differentiation: Breakthroughs in ultrafast pulses, wavelength stabilization, and compact deep-UV modules are shifting competition from commodity pricing to system performance, uptime, and application-specific integration.
- Regulatory and safety inflection: New standards and sectoral regulations are raising the bar for compliant deployment—turning what was once a cost center (safety, certification) into a market-access prerequisite and a source of competitive advantage.
What the market evolution tells us
The UV lasers market is maturing. The historical period (2020–2025) shows steady organic expansion driven by increased adoption in semiconductor microfabrication, precision medical devices, industrial marking, and advanced display processing. Looking forward to 2032, the forecast indicates both deeper penetration into existing applications and emergence of higher-value use cases—driven by ultrafast pulse capabilities and novel wavelength modules. These shifts favor suppliers that can offer end-to-end repeatability, minimal thermal load on substrates, and validated integrations for regulated industries.
UV Lasers Market
Practical, near-term actions for 2026
- Prioritize modular product architectures: OEMs and systems integrators should accelerate modularization—enabling faster wavelength swaps, plug-and-play safety enclosures, and serviceable power modules that reduce downtime and total cost of ownership.
- Embed compliance into design: Product development must incorporate regulatory testing and certification roadmaps (e.g., aerospace and medical standards). Early alignment reduces time-to-market friction and can command pricing premiums in safety-critical segments.
- De-risk supply chains: With demand rising, buyers should map critical subcomponents (nonlinear crystals, UV-grade fibers, diode pumps), identify single-source risks, and establish dual-sourcing or vertical partnerships before capacity shortages drive spot price volatility.
- Shift go-to-market toward solutions: Vendors should bundle lasers with validated process recipes, fixtures, and software analytics to move up the value chain—from component supplier to process partner.
- Invest selectively in photonics IP and service ecosystems: For strategics and financial sponsors, targeted M&A in laser control electronics, ultrafast pulse shaping, or specialized optics offers disproportionate leverage on product roadmaps.
Report highlights — what’s inside (practical, operational content)
Our full study is structured to support fast, board-level and operational decision-making. Key elements include:
UV Lasers Market
- Market sizing and trajectory models: A transparent, auditable topline model covering historical (2020–2025) and forecast (2026–2032) performance, with scenario variants for conservative, base, and accelerated adoption cases.
- Technology readiness and TRL mapping: Comparative assessment of major UV technologies (solid-state, fiber, excimer, diode-pumped solutions, ultrafast vs. nanosecond regimes) against performance, cost, and manufacturability metrics. This is presented as decision matrices and go/no-go thresholds for product roadmaps.
- Commercial playbooks: Channel strategies, pricing archetypes, MQL-to-deal conversion benchmarks, and service revenue levers for suppliers seeking to capture aftermarket and license revenues.
- Regulatory and standards compendium: Practical checklists and test protocols required for aerospace, medical, and industrial deployments—linking standards to certification steps and expected timelines.
- Supply chain heatmaps and sourcing playbooks: Component concentration analyses, supplier scorecards, and recommended strategies for redundancy and nearshoring where warranted.
- Financial scenarios and investment cases: Capex/Opex modeling templates, NPV sensitivity runs, and break-even timelines for common investment archetypes (capacity expansion, new wavelength lines, service network rollouts).
- Actionable use-case dossiers: End-user process validation guides for semiconductor, medical, marking, and other prioritized segments—complete with expected yield improvements, cycle-time impact estimates, and key integration risks.
Because this publication follows a “trailer” design, the full segmented revenue tables, geographic and application splits, and the granular unit economics are available exclusively in the paid report and through our client portal.
Competitive landscape — who’s shaping the next wave
The market structure is moderately concentrated: the top three suppliers capture approximately two-thirds of market revenues, while the top five approach three-quarters of the market—indicating strong incumbents with meaningful scale advantages. Competitive dynamics are now defined less by raw output and more by system-level performance, service availability, and validated application expertise.
- Coherent Corp. — A leader in high-energy deep-UV systems tailored to semiconductor lithography and display processing. Recent launches demonstrate a push toward wavelength-stabilized, high-power platforms that aim to reduce variability in critical process windows.
- TRUMPF — Focused on precision short-pulse UV sources for marking and sensitive substrates; their architecture emphasizes gentle, air-cooled operations suited for high-throughput production lines.
- IPG Photonics — Investing in ultrafast and deep-UV fiber solutions with a clear slant toward reliability and uptime—critical for micro-machining and inspection markets. Their showings at recent industry events signal readiness to scale module-level offerings.
- Han’s Laser — Maintaining strong presence in industrial marking and engraving with broad product accessibility, including handheld solutions. Their trade-show activity underlines continued focus on intelligent, factory-ready systems.
- Lumentum — Concentrating on nanosecond Q-switched platforms for micromachining and high-stability industrial applications; recent product showcases underline throughput and micro-processing performance improvements.
- Amplitude Laser, MKS (Spectra-Physics), DPSS/Laserax — These firms advance specialized niches—ultrafast femtosecond offerings, high-speed marking, and certified workstations respectively—each providing potential partnership or acquisition targets based on corporate strategy.
Recent industry developments to watch (implications for 2026)
- IPG Photonics and Lumentum showcased new high-precision deep UV and ultrafast platforms at SPIE Photonics West 2026—signaling accelerated commercialization of higher-power, application-ready modules. Buyers should expect availability of more compact, higher-throughput units in 2026–2027.
- Coherent’s March 2026 launch of a wavelength-stabilized deep UV system highlights vendor competition at the lithography and display processing frontier. This raises the bar for suppliers addressing sub-micron process windows.
- Han’s Laser and other assembly-line-focused vendors are positioning smarter, more connected marking systems at major trade shows—indicating a shift toward integrated factory deployments where laser performance is coupled with process analytics.
- Standards activity (e.g., aerospace wiring marking requirements and safer Class 1 workstation certifications) is increasing the compliance burden—but also creating opportunities for “compliant-by-design” products that simplify customer procurement and audit trails.
Risk map and mitigation priorities
- Technology obsolescence risk: Shorten development cycles via modular platforms and incremental upgrades rather than monolithic single-version releases.
- Supply concentration: Source critical optics and pump diodes from multiple qualified suppliers; consider component stockpiles for planned ramp phases.
- Regulatory delay: Build certification timelines into go-to-market plans; pursue joint validation pilots with anchor customers to accelerate approvals.
- Customer adoption lag: Offer pilot-as-a-service programs to demonstrate value and reduce procurement friction.
How PW Consulting helps
Our report is designed to be immediately actionable for CFOs, CTOs, VP Product, and corporate development teams. We combine quantitative market models, legal/regulatory mapping, competitive benchmarking, and executable commercial playbooks. For organizations preparing capital budgets or strategic roadmaps for 2026, the study provides tailored scenario outputs and a suite of templates that compress decision cycles from months to weeks.
Next step — where to go for full intelligence
This briefing intentionally presents the strategic contours and executable implications while omitting detailed subsegment tables and proprietary financial matrices. For the full dataset—region and application splits, wavelength and technology revenue breakdowns, unit economics, and downloadable modeling files—please visit our report landing page. Engaging with the full report will equip your leadership team with the granular inputs required to finalize 2026 capital allocations, product launch sequencing, and M&A screening criteria.
For tailored briefings, model walkthroughs, or scenario workshops focused on your role in the UV lasers ecosystem, PW Consulting offers executive workshops and bespoke modeling services to turn this market intelligence into immediate competitive advantage.
For detailed analysis of this topic, please visit the official page: UV Lasers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com