

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Air Beds Market Hits $340M in 2025: 7.9% CAGR and Asia Pacific Reshaping Revenue by 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Air Beds Market
Market Overview: Scale, Trajectory, and Structural Realities
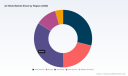
The global air beds market has evolved from a niche hospitality and camping accessory into a diversified commercial category shaped by shifting sleep preferences, flexible accommodation models, and incremental engineering improvements. Between 2020 and 2025, the market expanded from roughly 230 million USD to 340 million USD, reflecting a compound annual growth rate of 7.9 percent over the broader forecast window through 2032. By the end of the projection period, revenue is expected to approach 575 million USD, indicating sustained demand expansion rather than a temporary post-pandemic rebound. This trajectory suggests that air beds are no longer treated as disposable substitutes but are increasingly evaluated against conventional foam, innerspring, and hybrid sleep surfaces on the basis of portability, space efficiency, and targeted comfort performance.
The composition of demand reveals a market in transition. Household applications continue to anchor the majority of revenue, driven by guest accommodation, apartment living, and multi-purpose room setups where floor space is at a premium. Commercial deployments represent a meaningful secondary channel, with hospitality operators, event organizers, and emergency housing providers leveraging air beds for rapid scalability and reconfiguration. The product mix remains bifurcated: one segment emphasizes consumer-grade mattresses designed for prolonged home or guest use, while the other focuses on traditional air beds optimized for temporary deployment, travel, and outdoor recreation. This divergence matters because each segment faces distinct performance expectations, margins, and replacement cycles.
Concentration levels underscore the strategic importance of brand position and distribution reach. A small group of established players controls a substantial share of revenue, particularly in the consumer category, where repeat purchases, retail visibility, and brand trust heavily influence category growth. At the same time, the market has not reached full consolidation, leaving room for specialized manufacturers, regional distributors, and performance-oriented entrants to carve out defensible niches. The reality on the ground is therefore one of measured expansion layered with structural friction: strong top-line growth coexists with pricing pressure, substitutability concerns, and uneven channel performance across segments.
PW Consulting
Key Challenges and Inflection Points
The most pressing challenge is the tension between convenience and long-term performance perception. Air beds have historically been associated with temporary use, and many buyers still hesitate to treat them as primary sleep surfaces. This perception cap limits penetration in households seeking durable, everyday comfort solutions. Overcoming it requires more than incremental softness improvements; it demands demonstrable durability, stable support under repeated inflation cycles, and clear differentiation from low-cost, short-lived alternatives that damage category credibility.
A second inflection point involves channel fragmentation and the shifting economics of trial and return. In online-first retail, buyers increasingly expect easy testing, clear product descriptions, and reasonable return policies. For bulky or inflatable products, logistics costs and return rates can erode margins quickly, especially when specifications are ambiguous or when products are positioned too close to conventional mattresses without clear justification. Companies that cannot align product messaging, packaging, and fulfillment with digital purchasing behavior risk losing share to brands that make the buying decision simpler and more predictable.
The third challenge is regulatory and sustainability scrutiny around materials and end-of-life handling. As consumer awareness of product composition grows, manufacturers face increased pressure to justify material choices, reduce environmental footprints, and avoid over-reliance on formulations that invite reputational or compliance risk. This is not yet a uniform market requirement, but it is becoming a differentiator in premium segments and in procurement environments where sustainability criteria influence vendor selection. Companies that address this proactively can use it as an entry point into higher-margin channels, while laggards may find themselves excluded from bids or retail listings that increasingly factor in material transparency.
Core Drivers Shaping Market Direction
Technological Advancements and Performance Engineering
The most tangible driver of category evolution is engineering progress in support stability, air retention, and integrated convenience features. Modern designs increasingly combine internal coil structures, layered fiber or fabric systems, and refined valve or pump mechanisms to address long-standing complaints about sagging, leakage, and uneven pressure distribution. These improvements matter because they shift the product narrative from temporary convenience to viable comfort support, especially for guest rooms, multi-use spaces, and short-term lodging. Pumping technology has also become more integrated and quieter, reducing friction in setup and improving usability for both consumer and commercial settings.
Several established manufacturers illustrate this trajectory. Intex Recreation Corp. has emphasized fiber-tech construction and high air retention in consumer-oriented lines, reinforcing the idea that air-based products can deliver more consistent comfort over repeated use. Coleman has focused on leak-resistant airbed cots and raised designs with coil support, targeting outdoor and guest applications where durability and quick deployment are critical. Sound Asleep Products has built its Dream Series around internal pump integration and eco-friendly PVC construction, reflecting a broader move toward convenience and material-conscious positioning. King Koil Airbeds has pursued a luxury-leaning angle with enhanced coil technology and built-in pumps for guest and home use, demonstrating how elevated support claims can support higher price points. These product directions are not isolated; together they signal a market that is rewarding precision, reliability, and clearer use-case positioning.
Policy, Regulation, and Procurement Standards
Policy and procurement environments are becoming more influential as buying decisions move beyond pure price comparison. In commercial and institutional settings, procurement teams increasingly evaluate durability, maintenance requirements, and material documentation alongside upfront cost. Where public or large-scale private buyers incorporate sustainability, safety, or vendor qualification criteria, air bed suppliers that can provide consistent specifications and reliable compliance narratives gain an advantage. This does not mean regulation is changing the market overnight, but it is raising the floor for what qualifies as an acceptable commercial product in certain channels.
At the same time, labeling and material disclosure expectations are gradually shaping consumer confidence. Buyers are more likely to engage with brands that communicate construction details clearly, especially when a product is positioned as suitable for longer-term guest or household use. This trend favors companies that invest in straightforward product storytelling and consistent quality control, while penalizing those that rely on vague comfort claims without supporting design or manufacturing discipline.
Hospital Beds Market
Demand-Side Shifts in Consumer and Commercial Behavior
Demand is increasingly shaped by space constraints, flexible living arrangements, and the normalization of temporary or multi-purpose furniture. In urban and rental-heavy housing markets, consumers value products that can be stored compactly, deployed quickly, and repurposed across guests, travel, or seasonal needs. This supports continued household demand, particularly where bedrooms are shared or where a secondary sleeping surface must be available on demand. At the same time, consumer expectations for comfort have risen, meaning that basic inflatable products face tougher competition from designs that approximate the feel of more traditional sleep surfaces.
On the commercial side, the relevance of air beds depends on operational flexibility. Hospitality operators, event providers, and overflow accommodation managers value products that can be installed rapidly, sanitized or replaced with minimal downtime, and adapted to varying occupancy patterns. This creates recurring demand in settings where speed and reconfigurability matter more than permanent bed infrastructure. Glamping and outdoor lodging concepts have also expanded the commercial-use conversation, with brands such as Zempire emphasizing durable bases and stretch fabrics for outdoor and renovated camping environments. Such use cases illustrate how commercial demand can stretch beyond traditional hospitality and into experience-led accommodation models.
Air Springs Market
Supply Chain and Cost Structure Dynamics
Cost structures remain sensitive to materials, manufacturing consistency, and outbound logistics. Inflationary pressure on components and freight has periodically squeezed margins, especially for lower-priced products where cost differentiation is already narrow. In response, manufacturers have leaned more heavily on design efficiency, localized product variation, and packaging optimization to protect viability without undermining perceived value. Supply chain resilience has also become a strategic consideration, as disruptions can quickly affect retail availability and commercial replenishment cycles.
For both consumer and commercial players, the practical implication is that total cost of ownership is increasingly important. A cheaper unit with higher failure or replacement frequency may be less attractive than a slightly more expensive option with better durability and lower service burden. This shifts attention toward engineering consistency, quality assurance, and after-sale support, especially for commercial buyers managing multiple units across locations.
Competitive Landscape and Strategic Positioning
The market is anchored by a set of recognizable manufacturers with distinct positioning. Intex Recreation Corp. maintains a strong consumer-facing presence through product lines that emphasize comfort features and practical inflation performance, supported by broad retail familiarity. Coleman leverages its outdoor and seasonal brand equity to compete in recreational and guest-use segments, where leak resistance and straightforward setup are valuable selling points. Sound Asleep Products and King Koil Airbeds both pursue more comfort-oriented narratives, but with different emphases: one leans into integrated convenience and material-conscious construction, while the other targets a higher-end feel with enhanced coil support and built-in pumps for home and guest applications.
Beyond the consumer core, specialized players add differentiation through use-case focus. Zempire has positioned itself in glamping and outdoor applications with durable bases and stretch fabrics, an approach that aligns with experience-led lodging and camping demand. Pittman Outdoors has built relevance through vehicle-specific and truck bed air mattress solutions, an example of how niche adjacency can create defensible demand where general-purpose products are less optimized. Together, these companies illustrate that competitive advantage in this market is rarely about scale alone; it is often about how precisely a brand aligns product design, messaging, and distribution with a defined purchasing context.
Looking forward, the competitive landscape is likely to evolve along two parallel tracks. One track involves continued brand consolidation among broad consumer manufacturers that can compete across retail channels, manage product complexity, and sustain visibility in high-traffic categories. The other track favors targeted entrants and regional players that serve specific applications well enough to command better margins and stronger buyer loyalty. There is also room for private-label and procurement-oriented supply relationships, especially where commercial buyers prioritize specification consistency over brand recognition. The market is therefore unlikely to become monochromatic; instead, it will probably become more segmented, with winners defined by application fit as much as by product features.
Future Trends and Commercial Opportunities
Performance-Driven Premiumization in Household Use
One of the clearest medium-term trends is the gradual push toward more performance-oriented household products. As buyers become more comfortable evaluating air-based sleep surfaces for guest rooms and secondary bedrooms, manufacturers that can deliver stable support, low maintenance burden, and credible durability will have an opening to expand into higher-value positions. This trend creates opportunities for products that combine inflatable convenience with more conventional comfort expectations, particularly where integrated pumps, reinforced support structures, and clearer warranty or quality messaging reduce purchase risk. The commercial implication is straightforward: brands that can convincingly bridge the gap between temporary use and everyday comfort can capture willingness to pay that basic models cannot.
Expansion of Commercial, Experience-Led, and Flexible Accommodation Demand
Commercial demand is expected to remain important, but its composition may shift toward experience-led and flexible lodging contexts. Glamping, boutique outdoor retreats, event overflow, and short-term accommodation operators all value products that are quick to deploy, easy to maintain, and adaptable to changing occupancy. This creates opportunities for suppliers that can package products with operational reliability in mind, including consistent specifications, manageable storage profiles, and designs suited to repeated use. The broader opportunity lies in serving buyers who need sleep infrastructure that behaves more like flexible furniture than permanent fixtures, especially in settings where space and turnover are central constraints.
Material, Sustainability, and Procurement-Aligned Product Narratives
A third trend is the growing importance of material transparency and procurement-friendly positioning. As buying committees and retail gatekeepers pay closer attention to product composition, manufacturing consistency, and end-of-life considerations, companies that communicate clearly and maintain disciplined quality standards will be better placed to access premium retail listings and institutional buyers. This does not require dramatic reformulation across the board, but it does reward coherent product stories, controlled sourcing, and evidence-based claims. Businesses that treat sustainability and documentation as strategic assets rather than compliance overhead may find new access points in channels where trust and traceability increasingly influence purchasing decisions.
Risks and Uncertainties
Several uncertainties could shape how these trends play out. Consumer willingness to pay for upgraded air beds may stall if broader inflation or housing cost pressures tighten discretionary budgets, particularly in segments where air beds compete with lower-cost furniture alternatives. Substitution risk also remains relevant, as improved foam, hybrid, and modular sleep products continue to evolve and may capture buyers seeking permanent solutions. In commercial settings, demand can be sensitive to occupancy cycles, event activity, and procurement budget shifts, making revenue less predictable than in steady-state household use. Finally, any erosion in perceived product durability or inconsistent quality across batches could quickly weaken category confidence, especially in online channels where reviews and returns amplify negative experiences.
Strategic Implications for Decision-Makers
For Manufacturers
Product strategy should begin with use-case clarity rather than feature stacking. The most defensible positions emerge when a product is designed for a specific purchasing context, whether that is guest-room comfort, outdoor deployment, vehicle compatibility, or institutional repeated use. Once the application is defined, engineering priorities become easier to set: support stability, air retention, pump usability, material consistency, and packaging efficiency can all be tuned to the target buyer instead of diluted across competing demands. Manufacturing discipline matters as much as design ambition, because inconsistent quality in inflatable products quickly undermines trust and increases returns. Brands that invest in clear specifications, repeatable production, and reliable after-sale support will be better positioned to defend margins and expand into higher-value channels.
For Investors
Investment attention should focus on the segments where value creation is most sustainable. Broad consumer exposure can offer scale, but differentiation and channel fit often determine whether a player can maintain pricing power. Smaller, application-focused manufacturers may present more attractive operating leverage if they serve a defined niche with limited direct competition and clear procurement or retail gatekeeper alignment. Commercial-oriented supply relationships can also be attractive where recurring demand, specification reliability, and operational convenience create stickier customer relationships. At the same time, investors should monitor substitution risk and consumer sentiment, because the category's growth depends on continued acceptance of air-based sleep surfaces as more than temporary conveniences. Due diligence should therefore emphasize product consistency, channel economics, and the credibility of performance claims rather than headline category growth alone.
For Procurement and Commercial Buyers
Buying decisions should weigh total cost of ownership alongside upfront price. For household and guest applications, the practical question is whether a product will deliver consistent comfort and acceptable durability over its expected use life, not just whether it is inexpensive at checkout. For commercial deployments, the deciding factors often include storage efficiency, setup speed, sanitation or replacement feasibility, and the ability to standardize units across locations. Buyers benefit from demanding clearer product documentation, consistent specifications, and realistic warranty or replacement expectations, especially when purchasing at volume. Where sustainability or material transparency is relevant to internal procurement standards, it can be used as a screening criterion that narrows the field to suppliers with stronger operational discipline and more reliable documentation.
The air beds market is not expanding simply because consumers are buying more inflatable products; it is expanding because a growing set of households, lodging operators, and experience-driven businesses see air-based sleep surfaces as practical answers to space, flexibility, and deployment constraints. The next phase of value creation will belong to players who make those answers more credible, more durable, and more clearly aligned with real purchasing contexts. For decision-makers seeking to act on these dynamics with segment-level sizing, channel comparisons, and customized positioning guidance, the full research report is available for review.
For detailed analysis of this topic, please visit the official page: Air Beds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Calcium Aluminate Cement Market: How Asia Pacific’s 5.2% CAGR Trajectory and Refractory Demand Reshape the Sector
By pmarketresearch, 2026-09-21
Calcium Aluminate Cement Market: Strategic Trends and Commercial Opportunities in a High-Performance Materials Landscape
The Calcium Aluminate Cement (CAC) market has evolved from a niche binder solution into a strategically critical materials segment that underpins industrial durability, infrastructure resilience, and next-generation thermal applications. With global revenue expanding from approximately $1.28 billion in 2020 to $1.69 billion in 2025, and a projected trajectory to $2.38 billion by 2032 at a five-year compound annual growth rate of 5.2 percent, the sector demonstrates steady, demand-led expansion. Growth is not uniform across regions or use cases; rather, it reflects concentrated industrial adoption, shifting engineering requirements, and deliberate capacity investments by established players. For executives and capital allocators, the CAC market represents a structurally attractive but operationally complex environment where differentiation hinges on material performance, supply chain stability, and alignment with decarbonization and durability mandates.
Market Landscape and Structural Challenges
The revenue progression over the past five years illustrates a market that has recovered from earlier cyclical softness and is now entering a phase of disciplined expansion. The baseline year of 2025 anchors a forecast window extending through 2032, during which the market is expected to add roughly $690 million in incremental revenue. This trajectory reflects an industrial materials segment characterized by relatively high barriers to entry, application-specific formulation requirements, and steady replacement and retrofit demand rather than speculative volume growth. The concentration profile of the market reinforces this structure: the top three firms collectively account for approximately 43 percent of revenue, while the top five approach 60 percent. Such concentration signals the presence of entrenched technical expertise, established customer relationships, and scale advantages in specialized production, but it also leaves room for differentiated entrants and regional specialists to capture value in targeted segments.
Key Challenges and Inflection Points
Several structural pressures are reshaping how incumbents and new entrants compete. First, raw material dependency remains a persistent volatility driver. Bauxite feedstock sourcing is concentrated in a limited set of geographies, and procurement friction is a material share of supply planning complexity. Even with expectations of a modest alumina price decline in 2025, cost volatility tied to high-purity bauxite availability continues to influence margin planning and formulation economics. Second, the industry is navigating a transition in end-use engineering requirements. Steelmakers are increasingly moving toward electric-arc furnace configurations that demand alumina-rich refractory linings capable of withstanding temperatures above 1,700 degrees Celsius. This shift is not a simple volume story; it changes specification expectations, lining design assumptions, and the performance thresholds that CAC-based products must meet. Third, regulatory and standards adoption is gradually expanding the addressable use base in municipal and industrial infrastructure. The inclusion of sulfate-resistant calcium aluminate mortars in wastewater standards such as Australia’s WSA 160:2021 illustrates how specification changes can unlock new procurement pathways, but only when paired with local technical support, testing validation, and specification familiarity.
For decision-makers, these challenges translate into a clear operational mandate: growth will be captured by firms that can stabilize input costs, adapt formulations to higher thermal and chemical demands, and align with evolving standards rather than compete solely on price.
Calcined Alumina Market
Core Demand Drivers Shaping the Market
Technological Innovation and Performance Breakthroughs
Performance differentiation is becoming the primary battleground. CAC suppliers are expanding beyond commodity-grade offerings into specialized binders and refractory matrices that address longer service life, faster strength development, and greater resistance to thermal shock and chemical attack. Recent product introductions targeting improved thermal resistance and durability in steel and foundry environments reflect a broader industry push to support heavier operational loads and more aggressive process conditions. At the same time, enhanced binder portfolios are being developed for sustainable construction and high-performance refractory applications, signaling that technical Roadmaps are increasingly tied to durability, reduced maintenance frequency, and lifecycle performance. The commercial implication is straightforward: customers in refractory, infrastructure repair, and demanding construction applications are willing to pay for formulations that reduce downtime and extend replacement cycles, provided the supplier can demonstrate consistent quality and application support.
Policy and Regulatory Environment
Regulatory frameworks and technical standards are quietly re-shaping demand patterns. In wastewater and sewer infrastructure, specification changes that recognize sulfate-resistant calcium aluminate mortars create new acceptance pathways where conventional materials may underperform. Similarly, the growing adoption of thermal energy storage systems is introducing requirements for matrices that can endure hundreds of 600 to 650 degree Celsius cycles without losing mechanical strength. These are not marginal adjustments; they are design-level shifts that influence material selection at the engineering and procurement stages. For CAC producers, regulatory alignment offers a route to specification-led demand, but it also requires investment in testing, documentation, and technical collaboration with end users and engineering firms. Markets rarely move on raw material availability alone; standard-setting and certification often determine which materials become defaults in public infrastructure and industrial projects.
Demand-Side Shifts in Industrial and Infrastructure Behavior
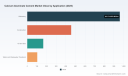
Demand is being shaped by two reinforcing behaviors. In heavy industry, there is a growing preference for materials that can withstand more severe operating conditions while reducing maintenance windows. This is evident in refractory applications, which represent the largest use segment and continue to drive volume as linings are specified for higher thermal loads and longer campaign life. In parallel, infrastructure repair and wastewater applications are increasingly valued for rapid strength gain and chemical resistance, making CAC-based binders attractive where downtime is costly or environmental exposure is significant. The construction segment, while smaller in relative terms, benefits from specialty uses where durability and fast setting are decisive. The broader message is that CAC demand is becoming more application-anchored: growth is tied to performance needs rather than generalized construction activity.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures remain influenced by feedstock concentration and the operational complexity of producing high-purity calcium aluminate products. Bauxite sourcing concentration in Guinea and China, combined with procurement challenges linked to raw-material cost volatility, keeps supply planning under scrutiny even as alumina prices are projected to ease modestly. This environment rewards companies that secure reliable feedstock arrangements, optimize energy and processing efficiency, and maintain flexibility in formulation to adapt to input cost movements. Regional capacity additions also play a role in shaping cost-to-serve. Localized production can reduce delivery lead times and improve service levels for large customers, which is particularly important in refractory and infrastructure applications where just-in-time supply and technical responsiveness can influence purchasing decisions. Cost efficiency in this market is less about absolute lowest input price and more about predictable availability, consistent quality, and the ability to serve demanding specifications without disruption.
Competitive Landscape and Leadership Strategies
The CAC market is defined by a mix of globally positioned specialists and regionally anchored producers with strong technical reputations. Leadership in this space is not determined by scale alone; it is increasingly tied to portfolio depth, application engineering capabilities, and strategic capacity deployment. Several firms have taken visible steps that highlight where the competitive frontier is moving.
Calucem has accelerated production at its New Orleans facility to meet rising demand from infrastructure and refractory applications, a move that underscores the importance of regional capacity in serving North American demand with shorter lead times and stronger local support. Imerys has expanded its calcium aluminate cement portfolio with advanced low-carbon binders for sustainable construction and high-performance refractories, reflecting a dual focus on performance and sustainability-oriented product design. Almatis introduced next-generation calcium aluminate cement products aimed at improved thermal resistance and durability in steel and foundry sectors, directly addressing the higher specification thresholds associated with modern furnace and casting environments. Cementos Molins increased R&D investment for high-performance calcium aluminate binders used in wastewater and infrastructure repair, signaling a deliberate push into specification-driven maintenance and municipal applications. In parallel, Calderys established a lightweight monolithics facility in Fulton, Missouri, increasing regional capacity by 60 percent and reducing delivery times, an example of how localized manufacturing can improve competitiveness in service-intensive segments.
Strategic Positioning and Differentiation
A few patterns emerge from these moves. First, portfolio premiumization is evident. Leading suppliers are not simply expanding volume; they are developing grades that target specific performance profiles, from high-alumina formulations to low-carbon binders and specialized mortar systems. Second, application proximity matters. Companies are investing where customer needs are most intense, whether that means refractory service for steel and foundry operations, marine and industrial flooring solutions, or wastewater and repair applications that require sulfate resistance and rapid strength development. Third, capacity is being aligned with demand geography and service expectations. Regional expansion is being used not only to increase output but also to improve responsiveness and reduce logistics friction for key accounts.
Market Structure Evolution
The market is likely to remain moderately concentrated, with room for both consolidation and targeted segmentation. Concentration at the top creates advantages in technical reputation, global supply coordination, and the ability to support large multinational customers across multiple regions. At the same time, the diversity of applications, grades, and regional standards creates opportunities for specialists that can dominate a particular use case or geography. New entrants face real barriers, including formulation know-how, qualification cycles, and feedstock access, but disruption is possible where a company brings a clearly differentiated value proposition, such as a novel binder architecture, superior cycle resistance for thermal storage applications, or a cost-effective regional supply model. The more probable evolution is not a single dominant wave of consolidation, but a continued mix of global leaders, regional specialists, and application-focused innovators competing on performance, service, and supply reliability.
Forward Outlook: Three Trends to Watch
Trend One: Specification-Led Demand in Infrastructure and Industrial Maintenance
Over the next several years, standards adoption and engineering preference shifts are expected to continue expanding CAC use in wastewater, sewer renewal, and industrial repair. The trend is not about sudden volume spikes; it is about a gradual but durable shift toward materials that meet more demanding chemical and durability requirements. Commercial opportunities lie in technical sales, specification support, and localized testing validation. Companies that invest in helping engineers and procurement teams understand sulfate resistance, rapid strength gain, and lifecycle cost advantages are better positioned to convert standards changes into recurring demand. The risk is that specification adoption can be slow and region-specific, requiring patience and sustained engagement rather than assuming immediate market pull.
Sodium Aluminate Market
Trend Two: Higher Thermal and Mechanical Performance Requirements in Refractories
As steelmaking and foundry operations adopt processes that push temperature and wear thresholds higher, refractory specifications will increasingly require alumina-rich linings and CAC-based matrices that maintain integrity under severe thermal cycling and mechanical stress. This trend favors suppliers with robust high-performance grades, consistent quality control, and the ability to support lining design and installation practices. The opportunity is to move from transactional supply to engineered solutions, where material selection is tied to campaign length, maintenance scheduling, and operational reliability. The uncertainty is that process changes can be uneven across regions and customers, and not every shift translates into immediate demand for premium grades if economics or operating strategies change.
Trend Three: Regional Capacity and Supply Chain Resilience Becoming Competitive Advantages
Given feedstock concentration and cost volatility, regional production and supply reliability are becoming differentiators rather than optional efficiencies. Near-customer capacity reduces delivery risk, supports large project timelines, and strengthens relationships with buyers who prioritize service continuity. Over the next few years, competitive advantage will increasingly accrue to companies that can combine formulation expertise with dependable supply and favorable cost-to-serve. This does not require universal scale; it requires strategic placement of capacity, disciplined feedstock management, and operational flexibility. The downside is that capacity additions and feedstock strategy carry capital and execution risk, and overinvestment in one region can leave a company exposed if demand patterns shift or input costs behave unexpectedly.
Strategic Implications for Decision-Makers
For Manufacturers and Suppliers
Focus on performance differentiation and application closeness rather than competing primarily on base commodity pricing. Develop and document grades that address specific high-value needs, such as higher thermal resistance, sulfate resistance, rapid strength development, and improved cycle durability for thermal storage environments. Invest in technical support and qualification assistance so that specification changes translate into actual adoption. Build feedstock and production strategies that reduce exposure to raw-material volatility while preserving the ability to serve key regions with shorter lead times. Consider targeted capacity additions where service levels and regional demand justify the investment, but avoid expanding without clear application pull and customer commitment.
For Investors and Capital Allocators
Evaluate CAC exposures through the lens of application mix, feedstock security, and regional service capability rather than headline market size alone. Segments tied to refractory performance, infrastructure repair, and specification-driven wastewater applications offer durable demand characteristics, but returns depend on execution, formulation leadership, and cost discipline. Watch for signals such as R&D emphasis on low-carbon binders and high-performance grades, localized capacity expansions, and standards adoption that broaden the specification base. Be mindful of concentration risk in feedstocks and the potential for margin pressure if input volatility persists despite easing alumina prices. The most resilient business models will likely be those that combine technical differentiation with dependable supply and the ability to serve demanding customers in multiple geographies.
For Procurement and Engineering Leaders
Treat CAC selection as a lifecycle decision rather than a transactional purchase. Where applications involve chemical exposure, thermal cycling, fast turnaround requirements, or long service life expectations, evaluate total cost of ownership including downtime, maintenance frequency, and replacement risk. Engage early with suppliers that can provide specification support, testing data, and application guidance, especially in projects governed by evolving standards or demanding operating conditions. Secure supply commitments where continuity matters, and consider regional sourcing options that reduce delivery risk for critical infrastructure and industrial maintenance programs. Procurement choices made with performance and reliability in mind can materially affect operational outcomes over the life of an asset.
Conclusion
The Calcium Aluminate Cement market is entering a phase where growth is increasingly tied to performance requirements, specification acceptance, and supply reliability. Steady revenue expansion toward the end of the decade reflects the material’s role in refractory durability, infrastructure resilience, and specialized industrial applications, but realizing commercial advantage requires more than exposure to a growing market. It demands formulation leadership, disciplined feedstock strategy, regional service capability, and the ability to convert engineering and standards shifts into qualified demand. For organizations operating in or adjacent to this space, the most valuable next step is to move from broad market awareness to precise segmentation, application-specific economics, and region-level supply strategy. Detailed segmentation data, regional breakdowns, and tailored strategic recommendations can sharpen those decisions and support more confident planning in a market where performance, standards, and supply chain resilience increasingly determine who captures value.
For detailed analysis of this topic, please visit the official page: Calcium Aluminate Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Imperatives in the Biaxially Oriented Polyamide (Nylon) Film Market: Navigating Growth, Volatility, and Sustainability
The biaxially oriented polyamide (BOPA) film market stands at a critical inflection point where traditional growth trajectories intersect with transformative pressure from raw material volatility, sustainability mandates, and shifting end-user expectations. Over the 2020–2025 historical period, the global BOPA film revenue expanded from approximately $1,170 million to $1,430 million, reflecting an average annual growth rate of roughly 4.2% in absolute terms. As the market enters the 2026–2032 forecast window, industry momentum is expected to accelerate, with a projected compound annual growth rate of 5.8%, pushing total revenue toward $2,088 million by the end of the decade. This expansion is not merely a continuation of historical demand patterns. It reflects a structural reconfiguration of how packaging, pharmaceutical, and industrial supply chains value barrier performance, mechanical durability, transparency, and increasingly, the carbon footprint embedded in film production.
For executives and strategic planners, this trajectory presents both a sizable addressable market and a complex operating environment. Growth is broad-based but uneven, shaped by regional manufacturing capabilities, regulatory divergence, and the concentration of value creation among a cohort of globally active producers. The following analysis examines the market’s current architecture, the forces reshaping its dynamics, the strategic positioning of leading participants, and the actionable implications for manufacturers, investors, and procurement teams navigating the next five years.
Market Architecture and Core Challenges
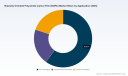
The BOPA film market operates within a moderately concentrated structure where scale, technology access, and application specialization determine competitive advantage. Revenue distribution spans multiple geographies and value chains, with Asia Pacific accounting for the largest share of global revenue, followed by Europe and North America. Latin America and the Middle East & Africa represent smaller but strategically relevant demand pools, often characterized by cost-sensitive industrial applications and emerging packaging consumption. Rather than competing purely on price, participants are increasingly differentiating through sequential versus simultaneous orientation technologies, gauge control, clarity, puncture resistance, and compatibility with laminates and heat-seal systems. The market’s oligopolistic tilt means that margin preservation depends on technical service, supply reliability, and the ability to anticipate downstream requirements in food safety, pharmaceutical compliance, and industrial durability.
Biaxially Oriented Polyamide (BOPA) Films Market
Despite the favorable growth backdrop, three structural challenges are reshaping the operating logic of the BOPA film sector:
- Raw material price sensitivity and input volatility. BOPA production depends on polyamide resins whose pricing is closely tied to caprolactam and adiponitrile dynamics, energy costs, and regional supply balances. Recent price adjustments in the nylon value chain have increased pressure on converters and film manufacturers, squeezing margins unless absorbed through product premiumization, contract structuring, or efficiency gains.
- Regulatory fragmentation and trade barriers. Divergent packaging regulations, anti-dumping measures, and evolving sustainability certification expectations are fragmenting what was once a relatively standardized export market. Producers now face a patchwork of obligations that affect cost, eligibility, and time-to-market for new grades.
- Sustainability expectations as a procurement imperative. End users are increasingly embedding environmental criteria into supplier selection, not simply as compliance but as part of brand positioning and risk management. Films with lower carbon intensity, recyclability alignment, and certified sustainable feedstocks are moving from niche differentiators to baseline requirements in certain segments.
These challenges are not isolated. They interact with one another, creating a landscape where cost, compliance, and customer expectations must be managed simultaneously. The firms that navigate this triad most effectively will be those that treat sustainability and regulatory adaptation as design parameters rather than afterthoughts, and that use technical differentiation to justify price realizations in a rising-cost environment.
Key Drivers Reshaping the BOPA Film Market
Technology Innovation and Performance Differentiation
Performance advancement remains the central engine of value creation in BOPA films. Sequential and simultaneous orientation processes continue to evolve, enabling tighter control over dimensional stability, barrier properties, and optical clarity. For pharmaceutical packaging and specialty high-barrier applications, this translates into films that maintain integrity under strict processing conditions and extended shelf-life requirements. For food packaging, improvements in tensile strength, sealability, and moisture resistance support thinner gauges and more flexible laminates without compromising protection. The strategic significance of these advances lies in their ability to shift competition away from commodity substitution and toward application-specific value. When a film can enable lighter structures, reduce waste in downstream converting, or improve reliability in sensitive applications, it becomes a strategic input rather than a replaceable component.
Recent dynamics underscore the importance of feedstock reliability in supporting these technical goals. In North America, price adjustments for caprolactam and polyamide grades have been announced for 2026, reflecting evolving conditions across the nylon value chain. At the same time, spot pricing for caprolactam has shown month-over-month increases in both North American and European markets. For BOPA producers, this environment rewards integrated planning, long-term supply agreements, and grade architectures that maintain performance even as input economics fluctuate. It also elevates the strategic importance of alternative feedstocks and certified sustainable options, particularly where customers view supply continuity and environmental credentials as linked priorities.
Policy, Trade, and Certification Shifts
The regulatory environment is becoming a more active determinant of market access and competitive positioning. Trade measures have already begun to reshape regional dynamics. For example, Indonesia has imposed anti-dumping duties on nylon film imports from China, Thailand, and Taiwan, with a multi-year validity period. Such measures influence not only the cost structure of imported films but also the broader pattern of regional sourcing, inventory positioning, and local manufacturing incentives. In parallel, certification frameworks are gaining commercial relevance. ISCC PLUS certification and product carbon footprint disclosures are increasingly referenced in customer evaluations, especially where end brands are under pressure to communicate environmental progress credibly.
These policy and certification developments have a dual effect. They raise the bar for market entry and expansion in affected geographies, but they also reward firms that can demonstrate verifiable sustainability claims and adapt their supply footprint to regional trade realities. For BOPA manufacturers, the implication is that geographic strategy can no longer be separated from compliance strategy. Production capacity, feedstock sourcing, and documentation capability are now part of the same commercial equation.
Demand-Side Evolution Across Packaging Ecosystems
Demand for BOPA films continues to be anchored by food packaging, pharmaceuticals, and industrial applications, each with distinct performance and regulatory profiles. Food packaging remains the largest application driver, supported by the need for barrier protection, clarity, and compatibility with flexible packaging formats. Pharmaceutical packaging demands high consistency, integrity, and traceability, making film quality and process stability especially important. Industrial packaging adds another layer of requirements around puncture resistance, durability, and cost efficiency in heavier-duty uses.
What is changing is the way these demand segments evaluate film suppliers. Procurement decisions are increasingly multidimensional, weighing technical fit alongside availability, sustainability attributes, and total cost of ownership rather than unit price alone. This shift is especially visible in markets where brand owners and converters are seeking to reduce material intensity, improve recyclability outcomes, or align with corporate sustainability commitments. In that context, BOPA films that support ultra-thin constructions, recyclable laminate designs, or carbon footprint reduction become more commercially attractive, even if they carry a premium relative to baseline alternatives.
Supply Chain and Cost Structure Dynamics
Cost structures across the BOPA value chain are being redefined by several simultaneous forces. Energy prices, resin availability, logistics, and regional manufacturing footprints all influence competitive positioning. At the same time, some producers are pursuing lower-cost manufacturing models for food and industrial packaging, while others are emphasizing high-performance grades for demanding applications. This bifurcation creates a market where cost leadership and technology leadership are not always pursued by the same players, and where the strategic challenge is to avoid being trapped in the middle of a segment that is simultaneously price-sensitive and performance-driven.
Certification and sustainability investments are adding a new layer to cost structure considerations. Obtaining environmental certifications for production facilities and rolling out lower-carbon grades requires upfront investment and disciplined execution. Yet these capabilities can also become durable advantages when customers begin to prioritize verifiable claims and supply assurance over spot-market pricing alone. The result is a market in which cost discipline and positioning clarity are both necessary, and in which the most resilient firms are those that can select the segments where their cost model and capabilities are best aligned.
Competitive Landscape and Strategic Positioning
The BOPA film competitive field includes globally established specialty producers, regionally focused manufacturers, and firms that balance cost efficiency with targeted performance differentiation. Several Japanese and Korean companies occupy a prominent role in high-quality sequential BOPA films, particularly where pharmaceutical packaging, high-barrier applications, and demanding food packaging formats are involved. Their positioning tends to emphasize sequential and simultaneous orientation expertise, consistent gauge control, and specialized barrier and mechanical attributes. This enables them to compete on reliability and application support, not only on price.
European participants contribute another dimension to the landscape. Certain manufacturers have focused on sustainable grades, recyclable laminate compatibility, and ultra-thin options that align with packaging 경량화 and environmental goals. Others have expanded sustainability credentials through ISCC PLUS certification and lower-carbon product claims, linking production credentials directly to customer-facing value propositions. In this group, the strategic emphasis is often on demonstrating measurable environmental improvement while maintaining the performance required by converters and end users.
In Asia, a broader set of producers supports regional and export demand across food, industrial, and specialty packaging. Some companies emphasize cost-effective manufacturing for high-volume applications, while others concentrate on PA6-based solutions or enhanced barrier and mechanical performance. This diversity creates a competitive environment in which regional price dynamics, local content expectations, and application specialization all matter. It also means that trade measures and regional certification requirements can quickly alter the relative attractiveness of different sourcing options.
Beyond firm-level positioning, the market is exhibiting several structural trends:
- Consolidation pressure in specialty segments. Where performance, compliance, and technical service are critical, larger or more integrated players can gain share by offering consistent supply, multi-grade portfolios, and stronger application support.
- Segmentation between cost-driven and value-driven production. Not all BOPA films compete in the same decision framework. High-barrier and pharmaceutical-oriented films reward precision and certification; certain industrial and food packaging applications remain more sensitive to cost and local availability.
- Growing relevance of sustainability as a competitive attribute. Lower-carbon grades, certified feedstocks, and recyclable laminate alignment are becoming part of the value proposition in select markets, especially where brand owners and converters are building sustainability into purchasing criteria.
- Regional reconfiguration of supply patterns. Trade measures and certification expectations are encouraging buyers to diversify supply sources or localize production where feasible, increasing the strategic importance of regional manufacturing and compliance readiness.
Taken together, these trends suggest a market that is moving toward greater segmentation and more explicit differentiation. The firms most likely to sustain favorable positioning are those that can define their competitive lane clearly, whether that lane is high-performance specialty films, cost-efficient regional supply, or sustainability-linked product architecture, and then execute with discipline in that lane.
Forward-Looking Trends and Commercial Implications
Trend 1: Sustainability Moves from Differentiator to Procurement Filter
Over the next three to five years, environmental criteria are likely to become more deeply embedded in BOPA film purchasing decisions, particularly in segments connected to consumer-facing brands and regulated packaging ecosystems. This does not mean every buyer will require the same standard, but it does mean that verifiable sustainability attributes, including certified feedstocks and product carbon footprint reductions, will increasingly influence supplier shortlists.
The commercial opportunity lies in linking sustainability claims to real performance and supply reliability. Films that combine lower carbon intensity with acceptable barrier, clarity, and mechanical properties can capture premium positioning in applications where environmental alignment matters. The risk is greenwashing exposure if claims are not substantiated or if sustainability improvements undermine the functional requirements that customers depend on. Firms will need to manage this balance carefully, with transparent documentation and product design that integrates sustainability without sacrificing performance.
Trend 2: Input Volatility Will Reward Integrated Strategy and Grade Architecture
Raw material and energy volatility are expected to remain features of the operating environment, not temporary disruptions. This will continue to pressure margins and elevate the importance of procurement strategy, hedging approaches, product mix management, and operational efficiency. In this context, the most resilient BOPA businesses are likely to be those that can adjust grade architecture to emphasize higher-value applications when cost pressure intensifies, while maintaining reliable supply for cost-sensitive segments.
The opportunity here is partly defensive and partly offensive. Defensively, stronger supply relationships and flexible sourcing can reduce exposure to spot-market shocks. Offensively, firms that can sustain consistent quality and performance despite input volatility can strengthen customer trust and justify more stable pricing relationships. The uncertainty is the pace and direction of feedstock and energy price movements, which can differ by region and shift quickly in response to broader market conditions.
Trend 3: Regionalization and Trade Policy Will Reshape Sourcing Maps
Trade measures, local content expectations, and certification requirements are likely to continue encouraging regionalization in BOPA supply chains. Buyers may increasingly prefer regional production or diversified sourcing to reduce exposure to duties, logistics risk, and compliance complexity. This favors producers with flexible manufacturing footprints, strong regional compliance capabilities, and the ability to serve local demand with consistent quality.
The strategic opportunity is to position capacity and product portfolios where regulatory and trade dynamics are most favorable, while maintaining the ability to serve export demand where it remains viable. The risk is that protectionist measures and regulatory divergence could fragment what remains a global technology market, increasing complexity and reducing the efficiency of scale-based strategies in some geographies. Participants will need to monitor policy developments closely and align sourcing and capacity decisions with evolving market access conditions.
Thermoplastic Polyamide Market
Strategic Actions for Decision-Makers
For manufacturing and strategy leaders, the priority is to align product positioning with the segments where performance and sustainability can be monetized most effectively. This means resisting the temptation to compete uniformly across all applications and instead selecting where sequential or simultaneous orientation technologies, barrier performance, and certified sustainable grades create genuine value. It also means building procurement and supply resilience into the operating model, especially given raw material price movements and regional trade dynamics. Manufacturers that can offer reliable supply, clear documentation, and application-specific technical support will be better placed to preserve margins and customer relationships in a volatile environment.
For investors and corporate development teams, the key question is where value is likely to concentrate as the market matures. The most attractive exposures are probably in firms with clear competitive differentiation, credible sustainability capabilities, and positioning that matches regional demand growth rather than broad, undifferentiated capacity expansion. Equally important is the risk side: exposure to input cost shocks, trade barriers, and commoditization in price-sensitive segments can erode returns if not managed through portfolio design and segment selection. Due diligence should therefore focus not only on capacity and revenue trend, but also on certification readiness, feedstock strategy, regional market access, and the defensibility of technical differentiation.
PW Consulting
For procurement and sourcing professionals, the strategic shift is to evaluate BOPA films through a broader lens that includes sustainability documentation, supply continuity, and total cost of ownership rather than unit price alone. When films are critical to product integrity or brand positioning, the cost of inconsistency, supply disruption, or misalignment with sustainability expectations can outweigh modest price differences. Diversifying qualified suppliers by capability and region, understanding certification status, and clarifying performance requirements with converters and internal stakeholders can reduce exposure while creating room to capture value from specialized films where they are justified.
For all of these audiences, the practical takeaway is that BOPA film strategy is no longer solely about film properties or price. It is about aligning technology, compliance, sustainability, and regional supply dynamics with the specific applications that matter most to each business. The market’s growth trajectory provides room for value creation, but capturing that value will increasingly depend on precision in positioning and discipline in execution.
The dynamics described here are broad in scope, but their real impact is highly segment-specific and region-specific. Detailed segmentation data, regional revenue breakdowns, competitor benchmarking, and customized scenario analysis can materially sharpen strategic decisions, particularly for organizations evaluating capacity investments, supplier qualification, product roadmap planning, or market-entry timing. For teams that require a more granular view of segment growth paths, competitive positioning, and application-level demand shifts, PW Consulting’s full market research report provides deeper segmentation detail and tailored analytical frameworks to support concrete business decisions.
For detailed analysis of this topic, please visit the official page: Biaxially Oriented Polyamide (nylon) Film (BOPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Plasma Etch System Market: Strategic Trends and Commercial Opportunities Through 2032
The plasma etch system market has entered a phase of sustained expansion, driven by relentless demand for miniaturization, advanced packaging, and specialized surface engineering across multiple high-tech sectors. Historical data from 2020 through 2025 shows a market trajectory that has consistently outpaced broader semiconductor equipment cycles, with revenues climbing from approximately 163 million to 215 million over that span. The forward curve suggests continued momentum, with the market projected to exceed 344 million by 2032, reflecting a compound annual growth rate of roughly 13.5 percent. This expansion is not merely a function of cyclical upturns; it represents structural shifts in how manufacturers approach material removal, surface modification, and precision patterning at increasingly aggressive technology nodes.
Yet the headline growth figures only tell part of the story. Beneath the surface, the market is navigating a complex set of operational, regulatory, and competitive pressures that are reshaping how equipment suppliers design, sell, and support plasma etch platforms. For executives and investors evaluating exposure to this space, understanding the interplay between technology roadmaps, cost structures, and policy mandates is essential to positioning for the next phase of value creation.
Mapping the Current Landscape and Defining Constraints
The revenue distribution across regions highlights a globally dispersed but increasingly interconnected demand base, with Asia Pacific and North America together accounting for the largest share of system placements. Europe maintains a meaningful footprint, while Latin America and the Middle East and Africa represent smaller but steadily developing markets. This geographic spread matters because it means equipment suppliers cannot rely on a single demand engine; they must calibrate product portfolios, service networks, and application expertise to reflect regional priorities ranging from logic and memory scaling to specialty compound semiconductor processing.
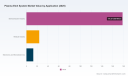
By technology type, inductively coupled plasma systems dominate the installed base, reflecting their versatility across a broad range of etching and surface treatment tasks. Reactive ion etching and deep reactive ion etching solutions occupy smaller but strategically important niches, particularly where vertical sidewall profiles, high aspect ratio features, or specialized throughput requirements dictate the choice of platform. On the application side, the semiconductor industry remains the dominant destination for plasma etch systems, with medical device manufacturing and electronics and microelectronics applications representing meaningful but comparatively smaller revenue pools. This concentration underscores a simple reality: semiconductor roadmaps continue to pull the bulk of investment and innovation, but adjacent sectors are increasingly willing to invest in tailored plasma processing capabilities when the performance argument is clear.
Dry Etching Equipment Market
Several structural challenges are testing the resilience of supplier strategies and buyer planning:
- Regulatory tightening around etch gases and chamber emissions. Environmental mandates are moving from aspirational targets to enforceable reduction pathways. In the United States, the EPA's AIM Act sets aggressive production and consumption reduction goals for hydrofluorocarbons over a fifteen-year horizon, directly affecting the use of gases common in plasma etch processes. In Europe, F-gas regulations are compressing allowable emissions of HFCs and hydrofluoroolefins, with targets to cut emissions to two-thirds of 2014 levels by 2030. These policies are not abstract: utilities and fabs are increasingly scrutinizing system-level emissions, and chamber clean configurations that reduce CF4 generation through remote plasma retrofits are already demonstrating measurable reductions against earlier emission factors.
- Specialty gas supply volatility and input cost pressure. High-purity specialty gases essential to plasma etch processes continue to face supply chain friction in key regions, where limited domestic production amplifies price sensitivity. Helium, a critical gas used in plasma etching, has experienced price volatility with costs rising by more than fifty percent over the past two years. For equipment and flip-to-play service providers, this translates into procurement risk and margin pressure that must be managed through contract structures, yield optimization, and system efficiency improvements rather than simple pass-through pricing.
- Performance expectations at advanced nodes and packaging complexity. As feature sizes continue to shrink and 3D architectures proliferate, etch systems must deliver tighter control over profile, selectivity, and variability while maintaining throughput. Buyers are increasingly unwilling to accept trade-offs that slow cycle time or compromise yield; at the same time, they demand greater flexibility to handle diverse materials, including compound semiconductors and advanced packaging substrates. This pushes suppliers to balance deep specialization with adaptable platform architectures.
These challenges are not isolated headwinds; they are reshaping the basis of competition. Suppliers that treat regulatory compliance and gas efficiency as afterthoughts risk being penalized by procurement criteria and operating economics. Conversely, those that embed low-emission chamber designs, robust gas management, and predictable consumable strategies into their platforms are creating a more durable value proposition.
Forces Shaping the Next Phase of Growth
Several drivers are converging to determine how the market expands over the forecast period, and each carries distinct implications for product roadmaps, customer engagement, and capital allocation.
Technology innovation and system-level differentiation. The pace of advancement in plasma etch tools is increasingly defined by how well platforms integrate precision, repeatability, and process flexibility. Recent product introductions point toward a clear emphasis on single-wafer capability, high-temperature processing, and surface treatment enhancements that address both front-end patterning and back-end passivation or cleaning. One notable example is the introduction of a single-wafer Aqua Plasma system alongside a 700°C high-temperature PECVD system for etch applications, signaling a push toward platforms that can support demanding thermal profiles and advanced surface engineering in tighter footprint configurations. Exhibit showcases at industry events further reinforce this trajectory, as suppliers highlight etching and surface treatment advancements that map directly to next-generation device architectures.
For buyers, the implication is that best-in-class is no longer a single metric; it is a combination of etch uniformity, sidewall quality, temperature control, and compatibility with a growing library of materials. Suppliers that can demonstrate measurable improvements in these dimensions, while minimizing rework and consumable consumption, are better positioned to command premium positioning and longer replacement cycles.
Policy and regulatory dynamics as a design constraint and differentiator. Environmental regulation is evolving from a compliance checkbox into a design parameter. The mandated reduction targets for HFCs and associated gases compel equipment developers to reconsider how chamber cleans, gas delivery, and remote plasma configurations affect both process performance and emissions. Practical experience already shows that retrofitting chamber cleans to remote plasma systems can reduce CF4 generation by more than thirty-five percent, providing a tangible example of how system design choices translate into regulatory alignment and potential total cost advantages over the lifecycle of the tool.
Semiconductor Etch Equipment Market
This matters for strategy because it creates two reinforcing opportunities: first, differentiation through lower-emission, more efficient plasma architectures that reduce operating risk for fabs; second, value creation through service models that help customers sustain compliance while maintaining throughput. Companies that treat these mandates as innovation drivers rather than constraints can convert regulatory pressure into competitive advantage, especially in markets where environmental due diligence is increasingly integrated into procurement decisions.
Demand-side shifts across semiconductor and adjacent applications. The semiconductor segment continues to be the central engine of demand, fueled by advanced logic and memory roadmaps and the expansion of advanced packaging. At the same time, medical and microelectronics applications are building their own cases for plasma processing, where surface modification, cleanliness, and reproducibility directly affect product quality and regulatory conformance. Demand is also becoming more application-specific: rather than uniform growth across all uses, certain workflows require tailored etch chemistries, smaller lot sizes, or pilot-line flexibility before commitment to full production. This is reshaping how suppliers think about platform modularity, service responsiveness, and application engineering support.
Supply chain and cost structure recalibration. The volatility in specialty gases, combined with the need for high-purity inputs and reliable consumables, is prompting a broader reckoning with cost structures. Equipment buyers are increasingly focused on total cost of ownership rather than sticker price, weighing factors such as gas utilization efficiency, uptime, chamber life, service coverage, and the predictability of consumables spend. Suppliers are responding with a mix of engineering improvements and commercial flexibility, including refurbished and custom configurations, pilot-line and production-oriented variants, and partnerships that extend capabilities across the value chain.
One relevant development is the collaboration between a leading plasma etch provider and a quantum manufacturing initiative to enable scalable quantum manufacturing via plasma processes. This kind of partnership illustrates how demand can emerge from new application domains and how incumbents can extend relevance by aligning process expertise with frontier fabrication needs, rather than relying solely on incremental improvements within established segments.
Competitive Positioning and the Evolution of the Field
The competitive landscape is a mix of specialized suppliers, regional experts, and large-scale equipment manufacturers, each pursuing different strategies to win share and defend positioning.
Niche and mid-tier specialists are leveraging deep application knowledge, customized configurations, and flexible commercial terms to serve customers with narrower process requirements or pilot-line needs. One U.S.-based manufacturer focused on plasma cleaning, etching, stripping, ashing, and reactive ion etching systems for surface preparation and modification, including custom and refurbished models, exemplifies a strategy built on applicability breadth and optionality. Another provider delivering premium wafer-based plasma etch, deposition, and advanced packaging equipment for microelectronics manufacturing emphasizes high-quality, application-focused platforms that map to demanding production requirements. A U.K.-based supplier known for advanced plasma etch systems including silicon, dielectric, and compound semiconductor etching and dicing platforms has built a reputation around specialized process capability and platform families tailored to specific materials and workflows. A Japanese developer and manufacturer of deposition, etching, and surface treatment systems, including plasma-enhanced ALD and high-temperature PECVD tools, has leaned into process integration and thermal capability as a point of differentiation. A U.S. manufacturer of plasma etch, strip, and deposition systems for semiconductor applications, and a French provider of plasma etch and deposition equipment with a focus on pilot-line and production systems, both reflect strategies oriented toward practical deployment flexibility and customer-specific adaptation. A Korean supplier of plasma etching equipment for semiconductor fabrication processes adds a regional processing strength, while the recent demonstration focus on etching and surface treatment advancements further signals continued investment in showcasing process maturity.
On the other side of the field, major equipment manufacturers with plasma etch systems integrated into advanced node fabrication lines and global chip fabrication and advanced packaging portfolios bring scale, broad material coverage, and deep integration with overall manufacturing ecosystems. A global supplier with plasma etch systems for chip fabrication and advanced packaging, and a developer of dry etch systems for advanced logic and memory device fabrication, illustrate how scale players compete on breadth, roadmap alignment, and the ability to support high-volume manufacturing with consistent process control. A Japanese producer whose equipment is integrated into advanced node fabrication lines underscores the importance of alignment with leading-edge ramp scenarios and yield-critical processing.
The resulting competitive dynamics are evolving along several axes:
- Differentiation through application depth. Specialists are competing on process fit, customization, and responsive engineering for specific materials and workflows, which can be especially valuable in compound semiconductors, advanced packaging, and smaller-volume medical or microelectronics applications.
- Differentiation through scale and integration. Large players are competing on platform reliability, throughput, global service footprint, and the ability to address the most demanding high-volume logic and memory production environments.
- Commercial flexibility as a strategic lever. Refurbished and custom models, pilot-line configurations, and partnership-enabled expansions are increasingly used to broaden addressable demand and reduce barriers to adoption, particularly in cost-sensitive or emerging application segments.
- Ecosystem alignment and new application gateways. Collaborations aimed at scalable quantum manufacturing and other frontier domains indicate that incumbents are seeking growth vectors beyond traditional semiconductor etch, using process expertise to enter adjacent high-value fabrication domains.
Market concentration, as measured by leading competitor shares, remains moderate, reflecting a field where value is distributed across multiple capable suppliers rather than dominated by a single platform family. This is important because it means competitive outcomes will be determined less by raw scale alone and more by how effectively each supplier can match product, service, and commercial flexibility to customer needs across a widening set of applications and geographies.
Looking Ahead: Three Trends Shaping the 2026 to 2032 Horizon
Based on the interplay of technology roadmaps, regulatory trajectories, and cost dynamics, several forward-looking trends are likely to define the next phase of market development.
Trend one: process efficiency and emissions control become core purchasing criteria. As regulatory reduction pathways tighten and input costs remain sensitive, buyers will increasingly evaluate plasma etch platforms on lifecycle emissions, gas utilization, chamber clean efficiency, and serviceability, alongside traditional metrics of profile quality and throughput. Systems that demonstrably lower emissions, reduce specialty gas dependence, and simplify compliance maintenance will gain traction, particularly in regions with strict environmental frameworks and in fabs managing multiple process gases across demanding schedules. The commercial opportunity here is twofold: for suppliers, it opens the door to design-led differentiation and value-added service packages; for buyers, it can translate into lower operating risk and more predictable long-term economics.
Trend two: platform modularity and application breadth will determine addressable demand. The widening range of applications, from advanced node patterning to compound semiconductors, advanced packaging, medical devices, and emerging fabrication domains, rewards suppliers that can offer adaptable architectures without abandoning process quality. Flexibility in configuration, the availability of pilot-line and production variants, and the ability to provide custom or refurbished options will become important enablers of market entry and expansion. Suppliers that combine a credible core process capability with a modular approach to add-ons, chamber options, and service modules are better positioned to capture demand from customers who need to de-risk scaling before committing to full production systems.
Trend three: partnerships and ecosystem extensions will create new growth vectors. The emergence of collaborations focused on scalable quantum manufacturing and other frontier processing needs suggests that plasma etch expertise is increasingly relevant beyond the traditional semiconductor core. For established players, partnerships can extend reach into high-value domains that demand specialized plasma control, while for suppliers with deep application knowledge, alignment with new fabrication initiatives can open routes to participate in next-generation technology scaling. This trend carries the potential for incremental revenue growth and brand reinforcement, but it also introduces execution risk: new applications require rapid learning, rigorous process validation, and close alignment with customer roadmaps that may still be evolving.
These trends imply both opportunity and uncertainty. On the upside, demand for higher-performance, lower-emission, and more flexible plasma etch systems is broad-based and likely to persist as technology nodes advance and new application sets mature. On the downside, policy implementation pace, gas supply conditions, and the timing of technology ramps can shift the rate of adoption. Buyers and suppliers alike should therefore plan for a market that is growing strongly over the horizon but where the timing and mix of demand are sensitive to external factors beyond any single company's control.
Strategic Actions for Executives, Investors, and Procurement Teams
For manufacturers and equipment suppliers, the priority is to convert regulatory and cost pressures into design and service advantages. This means continuing to invest in chamber and gas management architectures that reduce emissions and improve consumable efficiency, while building flexible product lines that span pilot-line, production, custom, and refurbished configurations. Equally important is service and application engineering: customers will increasingly choose platforms based on predictable uptime, compliance support, and the ability to adapt processes to new materials and workflows. Suppliers that align their commercial models with total cost of ownership, rather than unit price alone, will be better placed to defend margins and extend replacement cycles.
For investors, the key is to differentiate between cyclical demand and structural tailwinds. The broader market trajectory remains robust, but the distribution of value will likely skew toward suppliers that demonstrate process differentiation, regulatory alignment, and commercial agility across multiple applications and regions. Attention should be paid to signs of successful entry into adjacent application domains, evidence of emissions-reducing platform features, and the ability to manage specialty gas exposure through engineering and contractual mechanisms. Portfolio positioning should account for both the strong headline growth and the possibility that regional and application-level demand will shift at different rates.
For procurement and operations leaders evaluating plasma etch systems, the focus should broaden from specification sheets to lifecycle economics and risk management. Evaluate platforms for gas utilization efficiency, emissions profile, chamber clean strategy, service coverage, and the supplier's ability to support custom or pilot requirements without sacrificing process quality. Where feasible, structure engagements to test performance under real production conditions, and negotiate terms that align consumable and service costs with actual usage patterns. In an environment where input volatility and regulatory requirements are not going away, the most resilient buying decisions are those that balance performance with long-term operating predictability.
The strategic stakes in this market are rising as growth continues but the basis of competition becomes more demanding. Decision-makers who pair a clear understanding of the regulatory and cost environment with rigorous evaluation of process fit, flexibility, and supplier capabilities will be best positioned to extract value as the market moves toward 2032. For those seeking fully segmented data, regional and application-level detail, and customized recommendations aligned to specific investment or operational objectives, a comprehensive research report can provide the deeper granularity needed to inform precise decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Plasma Etch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vacuum Suction Cups Market: How 6.5% CAGR and 253.5M Scale Redefine Growth
By pmarketresearch, 2026-09-21
Vacuum Suction Cups Market: Strategic Trends and Business Opportunities in Automation-Driven Handling
The global vacuum suction cups market has entered a phase of steady, technology-led expansion, underpinned by consistent compound annual growth of 6.5 percent between 2020 and 2032. After a baseline period shaped by industrial recalibration and supply chain adjustments, revenue growth accelerated through the mid-2020s as automation adoption matured across discrete and process manufacturing. The market trajectory reflects a structural shift rather than a cyclical recovery: vacuum handling is increasingly integrated into core production workflows, with demand concentrated in high-throughput environments where precision, repeatability, and material compatibility are non-negotiable. This expansion is not evenly distributed across applications or materials. Instead, it is shaped by the intersection of product design innovation, regulatory expectations, and regional manufacturing priorities, creating a landscape where differentiation depends on how well suppliers align with application-specific requirements.
Beneath this growth narrative, several structural challenges define the current inflection point. First, performance expectations are rising faster than standardization, forcing suppliers to respond to highly variable surface conditions, material sensitivities, and cycle-time demands without sacrificing reliability. Second, compliance and hygiene requirements are becoming embedded in procurement decisions, particularly in food, packaging, and electronics handling, where material certification and process validation carry increasing weight. Third, the supply base is expanding in capability and geography, which intensifies competition on price and lead times while simultaneously raising the bar for technical support, customization, and integration services. These dynamics mean that market success is increasingly determined by application expertise, material science, and the ability to deliver repeatable performance in demanding environments.
Key Drivers Shaping Market Direction
Technology Innovation and Material-Specific Performance
Innovation in suction cup design and material composition is one of the most influential drivers of demand segmentation. Buyers are moving beyond generic handling components toward solutions engineered for specific substrates, surface textures, and process conditions. This is especially visible in electronics, precision assembly, and sheet handling, where mark-free contact, controlled pressure distribution, and static discharge protection are becoming baseline expectations. The expansion of specialized product families—such as ESD-focused designs for sensitive components and single-lip configurations for heavy flat objects—reflects a broader industry shift toward application-tailored handling rather than universal parts.
Worldwide Cupping Therapy Kits Market
Material selection is also shaping adoption patterns. Suction cups manufactured from silicone and nitrile-based compounds account for a substantial share of production, with silicone-based models representing a significant portion of domestic demand. Bellows-style designs remain widely used for uneven surface handling, highlighting the continued importance of geometry in achieving reliable grip across variable contours. At the same time, material grades that satisfy hygiene and process standards are gaining prominence in packaging environments, where cleanliness and compliance directly influence line design choices.
Regulatory and Hygiene Standards as Purchasing Filters
Regulatory expectations and food-safety standards have become practical filters in procurement, particularly in automated packaging lines. FDA-compliant, food-grade suction cups are no longer treated as niche accessories; they are increasingly specified where hygienic handling is essential. In meat and dairy packaging, a meaningful share of automated lines now relies on suction cups made from compliant materials, reflecting the growing importance of contamination control, cleanability, and material traceability. In packaging operations more broadly, compliance-oriented suction solutions contribute to a notable portion of consumption where hygiene requirements shape equipment specification.
This regulatory influence does more than expand a product category; it changes the buying process. Procurement teams increasingly evaluate material certifications, chemical compatibility, clean-in-place compatibility, and documentation alongside mechanical performance. Suppliers that can provide verified material compliance and application guidance gain an advantage in environments where downtime, audit risk, and line validation are costly.
Demand-Side Shifts in Automation and Line Throughput
Demand is being reshaped by the expansion of automated pick-and-place, transfer, and assembly operations across multiple sectors. Automotive assembly remains a significant application anchor, but the market is increasingly diversified by woodworking and furniture production, general industrial handling, and specialized material transfer. Two forces are especially important. The first is the push for faster cycle times with less manual intervention, which increases the share of handling tasks assigned to vacuum-based systems. The second is the need for gentler, more consistent handling of fragile or sensitive materials, which favors purpose-built geometries and material grades over generic components.
These demand-side changes are also changing how end users evaluate performance. Reliability across shift patterns, ease of integration with existing vacuum systems, and consistency across production batches are becoming as important as unit cost. As a result, buyers are increasingly willing to differentiate by specification when the application justifies it, rather than defaulting to the lowest-priced option.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures in this market are influenced by raw material availability, manufacturing precision, and the level of customization required. While commodity-style components remain price-sensitive, higher-specification solutions—especially those involving specialized materials, smaller diameters for delicate handling, or certifications for regulated environments—command different value logic. This creates a two-tier competitive environment: one shaped by volume and cost efficiency, and another shaped by technical value, integration support, and application reliability.
At the same time, suppliers are responding to lead-time and service expectations by expanding configurable options, standardizing core families, and reserving customization for cases where performance or compliance demands it. This approach helps balance flexibility with manufacturing efficiency, an important consideration in markets where demand is broad but application requirements vary sharply.
Competitive Landscape and Leading Strategies
Strategic Positioning Across the Supply Base
The competitive field includes established European and North American manufacturers, Asian suppliers with expanding configuration options, and automation-focused providers that emphasize modular integration. Leadership in this market is not defined solely by scale; it is increasingly defined by how clearly a company positions itself against application needs. Some manufacturers compete through broad reference libraries and highly configurable product ranges, enabling them to serve diverse industrial handling requirements. Others compete through specialization, such as ESD protection for electronics, food-grade compliance for packaging, or geometries designed for heavy flat objects and demanding surfaces.
This differentiation matters because buyers often evaluate suction cups not as standalone parts but as part of a handling solution. Companies that offer clear material categorization, application-specific series, and integration-friendly designs are better positioned to capture demand in environments where handling consistency and process compatibility determine purchasing decisions.
Recent Product Activity as a Signal of Direction
Recent product activity highlights where innovation is concentrated. In early to mid-2026, several suppliers introduced or expanded lines intended for sensitive handling, surface complexity, and heavy flat objects. One notable development was the introduction of an ESD-focused suction cup material designed for sensitive electronics handling, with emphasis on minimized marking and maximized static protection. This aligns with demand in battery, fuel cell, and electronic component handling, where surface integrity and electrostatic control are critical.
At the same time, a major supplier expanded its mini ESD suction cup range with smaller diameters aimed at battery, fuel cell, and electronic components, while also launching new families for demanding surface handling and single-lip designs for flat heavy objects such as glass and sheet metal. These moves indicate a dual trajectory: one toward finer handling of sensitive components, and another toward robust handling of large or irregular surfaces. The pattern suggests that product strategy is becoming more application-specific, with material and geometry treated as enablers of performance rather than interchangeable specifications.
Market Structure and Evolutionary Trends
The market remains moderately concentrated, with the largest players holding a meaningful but not dominant share of total revenue. This structure creates room for both differentiation and selective consolidation. Larger suppliers benefit from broader portfolios, integration capabilities, and established distribution relationships, while smaller or regionally focused manufacturers can compete through specialization, responsiveness, and niche application expertise.
Bra Cups Market
Looking ahead, the competitive landscape is likely to evolve along three paths. First, differentiation will increasingly depend on material certification, ESD and hygiene capabilities, and application documentation, especially in regulated or high-value handling environments. Second, integration and modularity will become more important as buyers seek components that fit cleanly into automated systems and simplify changeover. Third, regional supply dynamics will continue to shape competition, with buyers weighing local support, lead times, and configuration flexibility against price. New entrants may find opportunities in specialized materials, smaller-component handling, or regional service models, while incumbents will need to keep expanding application coverage without diluting manufacturing efficiency.
Future Trends and Commercial Opportunities
Trend One: Application-Tailored Solutions Will Outperform Generic Components
Over the next three to five years, demand is likely to shift further toward suction cups designed for specific materials, surface conditions, and compliance contexts. Generic handling components will continue to serve cost-sensitive or lower-specification applications, but higher-value demand will favor solutions that reduce mark formation, improve grip on variable surfaces, and meet electrostatic or hygiene requirements. For suppliers, this creates an opportunity to build value around application series, material grades, and configuration support rather than competing solely on volume pricing.
Trend Two: Regulated and Sensitive Handling Will Expand as a Strategic Segment
Food-grade, ESD-safe, and otherwise compliance-oriented suction solutions are expected to remain important growth vectors, particularly where automated lines must satisfy hygiene, safety, or component-integrity standards. This trend favors manufacturers that can provide verified materials, clear certification pathways, and application guidance. It also increases the strategic importance of technical sales and integration support, since specification choices often depend on line design, cleaning protocols, and handling risk.
Trend Three: Integration and Modularity Will Redefine Supplier Value
As handling systems become more tightly integrated into automated workflows, buyers will increasingly evaluate suction cups alongside connectors, mounting options, vacuum circuit compatibility, and changeover efficiency. Suppliers that design for modular integration and offer consistent families across sizes and materials can reduce engineering friction and improve total cost of ownership perceptions. The commercial opportunity lies in shifting from component sales to solution enablement, where performance, compatibility, and documentation collectively justify specification choices.
These trends carry risks. Demand may fragment across more application categories, raising complexity for manufacturers that over-standardize. Regulatory expectations may continue to evolve, requiring ongoing material validation and documentation. In addition, regional cost pressures and expanding supplier options may intensify price competition in commoditized segments, squeezing margins for players that lack application differentiation or service depth.
Strategic Actions for Decision-Makers
For Manufacturers and Product Leaders
Focus product roadmaps on application differentiation rather than broad catalog expansion alone. Prioritize material grades and geometries that address high-value handling needs, including ESD-sensitive components, heavy flat surfaces, and hygienic packaging environments. Balance configurable standard families with targeted customization to preserve manufacturing efficiency while meeting specialized demand. Equally important, strengthen application documentation and technical support so specification decisions are easier to justify inside end-user engineering and procurement processes.
For Investors and Corporate Development Teams
Evaluate opportunities based on application specificity, certification readiness, and integration capability rather than volume alone. Companies with strong positions in sensitive handling, food-grade compliance, or demanding surface applications may offer more resilient value propositions than those competing primarily on price in commoditized segments. Watch for consolidation patterns among suppliers with complementary portfolios, especially where product breadth, regional support, or material expertise can be combined to serve broader handling requirements.
For Procurement and Operations Teams
Treat specification as a risk and performance decision, not just a cost decision. Where handling involves sensitive surfaces, food contact, or high variability, prioritize material certification, mark-free performance, and compatibility with existing vacuum infrastructure. Standardize where possible to reduce changeover complexity, but preserve the ability to specify application-specific designs when process requirements justify them. Build internal evaluation criteria that include cleanability, compliance documentation, and integration fit alongside mechanical performance and unit price.
For organizations seeking a more granular view of market size by segment, regional dynamics, material and application splits, and company-level positioning, a full market research report can provide the detailed data and custom perspective needed for planning. Detailed breakdowns, scenario-based sizing, and supplier benchmarking can help translate the strategic themes outlined here into procurement decisions, product priorities, and investment theses aligned with specific operational goals.
For detailed analysis of this topic, please visit the official page: Vacuum Suction Cups Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Autonomous Drilling Robots: How 16.25% CAGR Reshapes Mining and Energy Markets
By pmarketresearch, 2026-09-18
Navigating the Autonomous Drilling Robots Market: Strategic Trends and Commercial Opportunities Through 2032
Market Momentum and Defining Challenges The worldwide autonomous drilling robots market has entered a phase of accelerated expansion, with revenue scaling from approximately 450.4 million USD in 2020 to an estimated 945.5 million USD by 2025. Projections indicate the market will surpass 1.1 billion USD in 2026 and continue its upward trajectory, reaching roughly 2.7 billion USD by 2032. At a compound annual growth rate of 16.25 percent across the forecast period, the sector reflects a structural shift rather than a cyclical uptick. This growth is underpinned by the maturation of sensing technologies, tighter safety mandates, and the escalating complexity of extraction and construction operations in remote or hazardous environments. Despite the compelling demand signals, the industry is navigating several critical junctures. First, the transition from semi-autonomous to fully autonomous systems demands a convergence of hardware reliability, real-time geotechnical feedback, and fleet-level orchestration that remains unevenly distributed across regions and applications. Operators are weighing the operational benefits of removing personnel from high-risk drilling zones against the capital intensity of sensor fusion suites, positioning systems, and adaptive control algorithms. Second, standardization and interoperability are emerging as practical bottlenecks. As drilling fleets grow more automated, the ability to integrate disparate rig platforms, data pipelines, and remote command centers becomes a decisive factor in realizing the promised productivity gains. Fragmented data architectures can slow deployment and dilute the return on automation investments. Third, the talent equation is reshaping procurement and deployment strategies. Persistent shortages of skilled drill operators in isolated mining and energy locations are pushing organizations toward continuous, automated operations, yet integrating these systems requires new competencies in remote supervision, maintenance, and data interpretation. Companies that treat autonomy as a standalone equipment purchase often underestimate the change-management and training requirements that determine long-term adoption success.
Key Drivers Reshaping the Autonomous Drilling Landscape
Technological innovation remains the central catalyst, but the nature of the advancement is evolving from isolated automation features to integrated, fleet-capable intelligence. Modern autonomous drill rigs increasingly rely on advanced sensor fusion, high-resolution positioning, and AI-driven algorithms that provide real-time geotechnical feedback and obstacle detection. These components enable machines to adjust drilling parameters on the fly, maintain consistent hole quality, and operate with minimal human intervention. Recent deployments illustrate how this technology is moving from pilot environments into production settings. A collaborative effort between a leading tool brand and an autonomous mobile robot specialist introduced a downward-drilling, fleet-capable concrete drilling robot designed for data center construction. Pilot programs demonstrated high accuracy across tens of thousands of holes, signaling that autonomous precision is now viable for large-scale floor preparation where consistency and speed directly affect downstream construction schedules. In parallel, mining equipment manufacturers have advanced autonomous surface drilling systems that combine fleet management with real-time optimization, while others have introduced electric autonomous variants and collaborative automation projects targeting fully autonomous face drilling and boom recovery functions. These developments show a clear trajectory: autonomy is being embedded into the core operating logic of the rig, not bolted on as an add-on module. Policy and regulatory momentum is reinforcing this technological shift. Safety mandates and industry standards are increasingly emphasizing the reduction of human exposure to hazardous environments, creating a regulatory tailwind for zero-entry or reduced-entry drilling operations. In mining, autonomous drilling systems align with broader safety objectives by keeping personnel away from active drilling faces and heavy equipment movement zones. In energy and infrastructure, automation is being evaluated not only for efficiency but also for consistency, documentation, and risk mitigation across complex well construction and foundation work. Public and private funding initiatives are also accelerating the maturation of adaptive automation and advanced recovery functions, particularly in academic and industry partnerships that focus on refining autonomous behaviors in variable ground conditions. This combination of safety-driven policy and targeted research support is helping lower the practical barriers to broader deployment. Demand-side behavior is changing as well, driven by project complexity and workforce constraints. The rapid global expansion of data center construction is creating a surge in demand for precise, repeatable floor preparation work, where autonomous concrete drilling robots can accelerate progress while improving accuracy and safety. At the same time, labor shortages and the difficulty of attracting and retaining skilled operators in remote mining locations are encouraging organizations to pursue continuous operations enabled by autonomous drilling technologies. This is not simply a cost equation; it is an operational resilience strategy. Companies are increasingly evaluating autonomy as a way to stabilize production, reduce variability, and maintain output when skilled labor is scarce or difficult to deploy. As a result, demand is spreading beyond traditional reserves into aggregates, quarries, and infrastructure projects where consistent performance and reduced operational risk justify the investment. Supply chain and cost structure dynamics are influencing how quickly organizations can adopt autonomous systems. The reliance on sophisticated sensors, high-resolution positioning hardware, and AI-based control software means that component availability, integration expertise, and software lifecycle management are becoming strategic considerations. Cost structures are also shifting as electric and autonomous variants gain traction, changing the calculus around fuel consumption, maintenance intervals, and emissions compliance. For many operators, the business case increasingly hinges on total cost of ownership over the life of the equipment rather than upfront purchase price. This favors suppliers that can offer integrated solutions, predictable software updates, and service models aligned with continuous, remote-operated workflows. As supply chains for advanced electronics and precision components stabilize and scale, the economics of autonomous drilling are expected to improve further, broadening access beyond early-adopter segments.
Competitive Landscape and Leadership Strategies
The competitive environment is defined by a mix of established equipment manufacturers, energy services companies, and specialized robotics developers, with a meaningful concentration of market share among a limited group of leaders. Incumbents in mining equipment have built strong positions by offering autonomous-ready drill rigs and surface drilling automation platforms that integrate fleet management and real-time optimization. Their advantage lies in decades of domain expertise, extensive field service networks, and the ability to embed autonomy into familiar rig architectures. Recent activity underscores this strategy: one manufacturer delivered an autonomous-ready rotary drill rig to a copper operation and partnered to implement surface drilling automation, while another secured a large order for autonomous and electric blasthole drill rigs in Africa, to be operated fully autonomously with zero exhaust emissions. These moves highlight a dual focus on performance and sustainability, as well as a willingness to commit to large-scale deployments in demanding environments. Energy services companies are pursuing a different but complementary angle, emphasizing drill automation software, directional drilling consistency, and integrated workflows across rig types. Their offerings target the repeatability and precision required in well construction, often pairing automation with geosteering and operational analytics. By focusing on software-defined drilling and service-integrated automation, these players are positioning autonomy as a way to reduce variability in complex wells and improve consistency across campaigns. This software-centric approach expands the definition of autonomous drilling beyond hardware, creating opportunities for companies that can orchestrate data, drilling parameters, and field execution in a unified workflow. A notable dynamic in the landscape is the emergence of specialized robotics and automation collaborators that bring new capabilities into established application areas. A robotics company focused on autonomous mobile platforms and fleet orchestration has partnered to power a downward-drilling concrete robot designed for data center construction, achieving high accuracy in pilot programs and targeting commercial availability in the near term. Another specialist has developed autonomous reverse circulation drill rigs for mining and exploration, with a clear emphasis on removing operators from hazardous manual operations. These entrants illustrate how the market is being shaped not only by traditional equipment rivalry but also by cross-industry partnerships that combine drilling expertise with advanced robotics, fleet management, and application-specific engineering. The result is a more pluralistic competitive field in which differentiation comes from application fit, integration depth, and the ability to deliver measurable accuracy and productivity gains. Market structure appears to be evolving along several axes simultaneously. Consolidation remains a plausible path as larger players seek to broaden their automation portfolios through acquisitions or strategic partnerships, particularly in software, sensing, and fleet orchestration. At the same time, segmentation is intensifying, with companies increasingly specializing by application, region, or level of autonomy. Some competitors are focusing on fully autonomous systems for defined use cases, while others continue to advance semi-autonomous solutions that offer incremental automation for organizations not yet ready for full removal of human operators. New entrants are gaining traction where they can solve a specific operational pain point with a clearly demonstrated accuracy or safety benefit, especially in construction and infrastructure segments that have historically seen less drilling automation. The most successful players are those that can articulate a clear path from installation to sustained operational value, supported by service, training, and data-driven optimization.
Future Trends and Commercial Implications
Over the next three to five years, one of the most consequential trends will be the shift from standalone autonomous rigs to coordinated, fleet-level automation. As more operations deploy multiple automated drill units, the value proposition will increasingly depend on orchestration, task allocation, and centralized monitoring rather than the capabilities of any single machine. Organizations that invest early in data standards, interoperable control architectures, and remote supervision capabilities are likely to extract more value from their automation investments and adapt more quickly as fleets expand. A second trend is the broadening of autonomy beyond traditional mining and energy applications into construction and infrastructure, particularly where precision, repeatability, and labor constraints intersect. Data center construction and large-scale floor preparation are already illustrating how autonomous concrete drilling can improve accuracy and throughput in high-volume projects. This application expansion opens commercial opportunities for suppliers that can tailor autonomy to different substrate conditions, site layouts, and project schedules, while also creating new demand for integration with broader construction workflows. A third trend is the continued coupling of autonomy with electrification and emissions reduction goals, especially in regions and sectors where sustainability requirements and operating costs are moving in tandem. Electric autonomous drill rigs and zero-emission operation concepts are gaining visibility in mining and quarry settings, and this convergence is likely to influence procurement criteria, site planning, and vendor selection. Companies that can offer autonomous performance alongside favorable emissions profiles may find stronger positioning in tenders and long-term partnerships. These trends carry commercial opportunities, but also uncertainty. Adoption velocity will depend on how quickly integration challenges are resolved, how consistently accuracy and reliability hold up across diverse site conditions, and whether organizations can build the internal capabilities needed to manage automated fleets. Economic fluctuations, changes in project pipelines, and evolving safety or emissions regulations could also alter deployment timelines. The most resilient strategies will treat autonomy as a long-term operating model transformation, not a one-time equipment upgrade.
Strategic Recommendations for Decision-Makers
For manufacturers and technology providers, the priority is to deepen application-specific value rather than compete solely on automation features. Differentiation will increasingly come from proven accuracy, fleet orchestration, service and software support, and the ability to demonstrate measurable improvements in safety, consistency, and throughput. Investing in interoperability, remote supervision tools, and clear upgrade paths can help products remain relevant as operations scale from single-rig deployments to coordinated fleets. Partnerships that combine drilling domain expertise with robotics, AI, and fleet management capabilities are likely to accelerate time to value and expand addressable use cases. For investors, the opportunity set is expanding but unevenly distributed. Segments with clear labor constraints, strong safety mandates, and high-volume precision requirements are showing particularly strong adoption logic, while broader market growth will depend on how quickly integration and standardization issues are resolved. Evaluating companies on their ability to deliver total cost of ownership benefits, sustain software and service ecosystems, and expand into adjacent applications can provide a more reliable basis for assessing long-term positioning than headline automation claims alone. For procurement and operations leaders, the practical starting point is to align autonomy investments with operational priorities and site realities. Assessing where autonomy can reduce risk exposure, stabilize output, and improve repeatability should come before technology selection. Pilots should be structured to measure accuracy, downtime, maintenance demands, and supervisory workload, with attention to data integration and training requirements. Building internal capability for remote operation, analytics, and preventive maintenance will be as important as selecting the right equipment. Detailed segmentation data, company-level benchmarks, and application-specific deployment considerations can help translate these strategic themes into precise planning assumptions. For decision-makers seeking a deeper view of market sizing, regional dynamics, and vendor positioning, the full PW Consulting research report provides expanded detail and customizable analysis to support investment, procurement, and product strategy decisions.
PW Consulting
Directional Drilling Market
Worldwide Underwater Dredging Robot Market
For detailed analysis of this topic, please visit the official page: Worldwide Autonomous Drilling Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Market Intelligence: Strategic Trends in the Worldwide Receiving Optical Sub-Assembly Components Market
Market Snapshot: Scale, Momentum, and Structural Headwinds
The worldwide market for receiving optical sub-assembly (ROSA) components has transitioned from a specialized supplier niche into a foundational pillar of modern optical communications infrastructure. Valued at approximately $4.58 billion in 2025, the sector has expanded consistently from $2.45 billion in 2020, reflecting a compound annual growth rate of 13.48 percent through the forecast horizon extending to 2032. This trajectory underscores how rapidly receiver sub-assemblies have evolved from peripheral transceiver components to critical enablers of bandwidth scaling, low-latency connectivity, and energy-efficient data transmission. The market's expansion is not merely cyclical; it is structurally reinforced by the parallel growth of optical transceiver volumes, the migration toward coherent and direct-detection architectures at higher data rates, and the continuous densification of fiber-based networks across enterprise, carrier, and cloud environments.
Despite this robust headline growth, the industry is navigating a series of inflection points that will determine margin trajectories, supply chain resilience, and competitive positioning over the next several years. First, the rapid escalation of AI-driven data center workloads is compressing procurement cycles and demanding receiver components that deliver higher sensitivity, broader bandwidth, and tighter integration with transceiver packaging. Traditional ROSA designs optimized for legacy metro or access networks are increasingly misaligned with the performance and form-factor expectations of next-generation optical engines, forcing manufacturers to accelerate material science and packaging innovation while managing yield and cost constraints. Second, geopolitical decoupling and export controls around III-V compound materials and semiconductor manufacturing equipment are reshaping sourcing strategies. Producers reliant on concentrated substrate supply or legacy assembly footprints are encountering longer lead times, pricing volatility, and heightened compliance complexity, making supply chain diversification and regional capacity planning strategic imperatives rather than operational afterthoughts.
Third, the market is experiencing a performance-versus-cost tension that is redefining procurement behavior. As hyperscale operators and system integrators push for lower cost-per-bit and improved power efficiency, receiver suppliers must balance advanced photodiode architectures, amplifier integration, and precision optical alignment against aggressive margin expectations. This dynamic is simultaneously rewarding manufacturers with differentiated process capabilities and pressuring those locked into commoditized assembly models. The net effect is a market that is expanding rapidly in absolute terms but increasingly bifurcated in terms of value capture, where technological readiness, materials access, and integration sophistication determine which players can sustain premium positioning.
Key Drivers Reshaping the Receiving Optical Sub-Assembly Landscape
Technological Innovation and Architectural Shifts
The most immediate driver of market evolution is the convergence of higher data rates, tighter integration, and advanced packaging formats. Receiver sub-assemblies are no longer standalone optical-to-electrical conversion modules; they are increasingly co-designed with transceiver engines, leveraging chip-scale packaging, low-loss optical alignment, and embedded control functionality to meet the latency and power constraints of AI fabric interconnects and high-speed data center links. Innovations in PIN and avalanche photodiode architectures continue to expand the sensitivity and bandwidth envelope, enabling receivers to support emerging modulation formats and extended reach requirements without excessive digital signal processing overhead. At the same time, packaging techniques that improve thermal stability, reduce optical loss, and streamline assembly flow are becoming critical differentiators, allowing suppliers to deliver higher performance within tighter cost and size constraints. Companies that have introduced symmetric, lower-cost chipset approaches and integrated optical sub-assembly optics into broader network solutions illustrate how product portfolios are shifting from discrete component delivery to system-level value creation. Recognition of highly integrated chip-scale packaging and optical sub-assembly products for AI network applications further confirms that the industry is prioritizing compactness, scalability, and performance density over traditional discrete assembly paradigms.
Optical Transceivers Market
Policy, Funding, and Supply Chain Reshaping
Policy momentum is rewriting the geographic and operational calculus for ROSA suppliers. Strategic semiconductor funding initiatives are actively supporting the expansion of indium phosphide substrate and epitaxial wafer production, with investments targeting domestic capacity for lasers and photodetectors used in optical components. These programs are designed to strengthen supply chain resilience for critical optical materials and reduce dependence on concentrated sourcing models. Simultaneously, large-scale equipment orders for metal-organic chemical vapor deposition and related epitaxy systems from leading optical communications manufacturers signal a deliberate ramp in production capability for indium phosphide-based components tied to datacom optical assemblies. The combination of public funding, private capital deployment, and capacity expansion is gradually rewiring the upstream materials landscape, giving qualified suppliers access to more stable substrate pipelines while raising the barrier to entry for manufacturers lacking secure material relationships. However, ongoing export controls and tariff measures on critical materials and semiconductor equipment continue to inject complexity into cross-border sourcing, requiring players to maintain flexible qualification pathways and multi-region supplier strategies to avoid disruption.
Demand-Side Transformation Across Applications
Demand growth is increasingly anchored by application environments that prioritize throughput, reliability, and total cost of ownership. Data center expansion remains a dominant force, driven by cloud infrastructure scaling, AI training and inference clusters, and the need for high-density optical connectivity that can sustain bandwidth growth without proportional increases in power or footprint. Telecommunication networks are undergoing a parallel transformation, with carriers modernizing passive optical networks and metro backbones to support faster broadband delivery, lower latency, and more flexible service architectures. The emergence of chipset solutions designed for next-generation fiber-to-the-room and fiber-to-the-home architectures highlights how receiver sub-assembly design is being aligned with network-level cost reduction goals while preserving performance. Beyond carrier and cloud use cases, enterprise and industrial deployments are contributing incremental but strategically valuable demand, particularly where ruggedized optical links, precise analog reception, and low-noise operation are required for video distribution, voice infrastructure, and specialized sensing applications. Across these segments, buyers are increasingly evaluating receiver components not merely by optical performance specifications but by integration readiness, supply continuity, and lifecycle support, shifting procurement from transactional purchasing to relationship-driven sourcing.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The ROSA market remains moderately concentrated, with a handful of established players commanding meaningful share while a broader field of specialized manufacturers competes on performance, cost, and regional proximity. Leading organizations have built differentiation through a combination of proprietary packaging technologies, photodiode architecture expertise, and application-specific module configurations. Semtech Corporation has reinforced its position by combining receiver sub-assembly optics with broader chipset portfolios that target symmetric fiber architectures and cost-sensitive network deployments, demonstrating a strategy that extends beyond component sales into system-level economics. Eoptolink Technology Inc. has focused on scalable production of transmitter and receiver assemblies alongside indium gallium arsenide photodiodes tailored for digital data applications, emphasizing the ability to move from trial samples to volume manufacturing. Applied Optoelectronics, Inc. continues to supply receiver sub-assemblies across telecom, datacom, and sensing contexts, leveraging broad transceiver integration experience to address multiple end markets with a common technology foundation.
Vitex LLC competes on high-sensitivity photodiodes designed for precise optical-to-electrical conversion, an approach that aligns well with applications where signal integrity and noise performance are paramount. MACOM Technology Solutions has pushed toward high-speed receiver modules with avalanche and PIN photodiodes configured for bandwidth-intensive datacom and telecom requirements, positioning itself in the upper performance tier where speed and package flexibility matter. Agiltron Inc. emphasizes a transceiver platform that balances low cost and high bandwidth for indium gallium arsenide and silicon receiver configurations, appealing to cost-conscious deployments that still require dependable performance. In Asia, Liverage Technology Inc. has maintained a broad speed range covering receiver modules used in 5G, data center, and telecom environments, with both PIN and avalanche variants supporting diverse link budgets. Xiamen San-U Optronics Co., Ltd. has targeted specific form factors and sensitivity profiles for fiber optic applications, an approach that enables focused differentiation in niche receiver segments. Lasermate Group, Inc. integrates photodiodes and amplifiers within its broader fiber optical component portfolio, while EZconn Corporation emphasizes indium gallium arsenide PIN photodiodes for high-speed, low-noise analog use cases in voice, video, and fiber-to-the-home receivers.
The competitive trajectory is shifting from pure specification competition toward integration advantage and supply chain reliability. Market leaders are increasingly rewarded for package-level innovation, co-engineering with transceiver developers, and the ability to support rapid scaling without sacrificing yield. At the same time, recent recognition of highly integrated chip-scale packaging and optical sub-assembly products for AI networks indicates that design integration is becoming a new differentiator, particularly for machine-to-machine and high-performance compute interconnects. The broader pattern points to consolidation among suppliers that can secure stable indium phosphide materials access, advanced packaging capability, and multi-application qualification, while smaller players must either specialize in cost-optimized volume segments or carve out technical niches where sensitivity, bandwidth, or application fit provide defensible margins. New entrants face a steep learning curve because receiver performance depends on tight control over epitaxy, alignment, and packaging, but targeted innovation in chip-scale integration or application-specific receiver configurations can still open viable pathways in high-growth sub-markets.
Optical Circuit Switches Ocs Market
Forward Outlook: Trajectory, Opportunities, and Uncertainty
Over the next three to five years, the receiving optical sub-assembly market is likely to be defined by three interrelated trends. The first is the deepening integration of receiver components into optical engines and co-packaged architectures, driven by the need to reduce power, shrink form factors, and simplify interconnect design for AI and data center networks. Suppliers that can deliver receiver sub-assemblies with chip-scale compatibility, low-loss optical paths, and scalable manufacturing will be best positioned to capture value as transceiver architectures become more tightly coupled. The second trend is the gradual rebalancing of indium phosphide substrate and epitaxy capacity, supported by both public funding and private equipment investment. As domestic and regional production expands, supply chain volatility should moderate for qualified buyers, though pricing and allocation dynamics will remain sensitive to equipment lead times, yield ramp rates, and geopolitical trade conditions. The third trend is the continued bifurcation between performance-premium and cost-optimized receiver segments. High-speed, high-sensitivity, and integrated amplifier solutions will sustain margins in datacom and advanced telecom applications, while volume access, enterprise, and industrial deployments will reward suppliers capable of delivering dependable performance at competitive cost.
PW Consulting
These trends create tangible commercial opportunities. Manufacturers that align product roadmaps with AI-era interconnect requirements, invest in packaging and alignment processes that improve yield and repeatability, and build multi-source material strategies will have stronger negotiating leverage with system integrators and cloud operators. Investors should monitor companies with demonstrable access to indium phosphide substrate pipelines, expanding epitaxy or packaging capacity, and product lines tied to chip-scale or highly integrated optical engines, as these capabilities are increasingly correlated with long-term relevance. Procurement teams, meanwhile, will benefit from developing supplier relationships that extend beyond unit pricing to include qualification support, ramp predictability, and resilience against material or equipment constraints. The principal uncertainties are execution risk in capacity expansions, the pace at which export controls and trade policy might alter materials availability, and the possibility that rapid transceiver architecture shifts could change receiver integration requirements faster than suppliers can adapt. Markets that grow at double-digit rates can still produce uneven outcomes if technology transitions outpace process maturity or if supply chain re-engineering introduces unexpected delays.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align receiver roadmaps with where performance, packaging, and materials access converge most favorably. Investments in chip-scale compatibility, high-sensitivity photodiode variants, and process controls that improve yield and repeatability will be more valuable than incremental specification upgrades alone. Companies should also stress-test supplier relationships for indium phosphide substrates and epitaxy capacity, and qualify alternative sourcing where feasible to reduce exposure to concentrated material dependencies. Building application-specific receiver configurations for AI network interconnects, high-speed data center links, and modernized fiber access networks can open differentiated positioning without requiring platform-wide redesigns.
For investors, the most informative signals will come from capacity deployment, materials access, and integration strategy rather than headline growth alone. Companies with confirmed equipment orders for epitaxy systems, expanding domestic or regional indium phosphide production, and product portfolios tied to highly integrated optical engines warrant closer scrutiny, particularly when paired with demonstrated volume ramp capability. Equally important is assessing whether a player’s differentiation rests on proprietary process knowledge or on interchangeable assembly economics, since the latter tends to erode faster in competitive segments. Portfolio exposure should favor organizations that can translate materials and packaging advantages into recurring transceiver-related demand.
For procurement and supply chain leaders, the strategic shift is from price-only sourcing to resilience-weighted evaluation. Receiver components increasingly influence system-level power, latency, and integration complexity, which means qualification criteria should weigh performance stability, ramp predictability, packaging maturity, and continuity of critical materials. Developing multi-region supplier options and securing early engagement with vendors that are expanding InP-related capacity can reduce vulnerability to allocation shocks or trade-related disruption. For organizations that require deeper segmentation data, scenario modeling, or customized sourcing and investment guidance, a dedicated report provides the granular breakdowns and bespoke analysis needed to translate these market-level signals into operational decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Resceiving Optical Sub-Assembley Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Worldwide LED Panel Lights Market
Market Landscape and Core Challenges
The global LED panel lights market has matured into a multi-billion-dollar segment, with revenue climbing from approximately USD 18.5 billion in 2020 to an estimated USD 27.9 billion by 2025. The trajectory reflects sustained cumulative growth of over 50% across the five-year span, driven by structural replacements of legacy fluorescent and high-intensity discharge fixtures in both commercial and residential settings. Looking ahead, the market is projected to expand from roughly USD 30.5 billion in 2026 toward USD 49.3 billion by 2032, sustaining a compound annual growth rate near 8.5% through the forecast period. This expansion is not merely a continuation of replacement cycles; it signals an inflection point where lighting transitions from a purely utilitarian component to a platform for energy optimization, space reconfiguration, and human-centric environment design.
Several structural challenges are reshaping how participants navigate the next phase of growth. First, regulatory efficacy thresholds are tightening globally, forcing manufacturers to reconcile performance requirements with cost constraints and design trade-offs. As standards evolve, products that once qualified as efficient are being outclassed by newer benchmarks, pushing continuous R&D investment and rendering legacy SKUs obsolete faster than in prior cycles. Second, the supply chain for key semiconductor and rare-earth materials remains exposed to geopolitical friction and licensing adjustments. Export controls and tariff frameworks affecting gallium, germanium, and certain processed critical minerals have introduced intermittent cost volatility and sourcing complexity, particularly for manufacturers reliant on specific regional component pipelines. Third, price compression in LED chips and core components continues to reshape margin dynamics. Capacity expansions and the transition to larger wafer formats have lowered input costs, but they simultaneously intensify competition on price, shifting the battleground toward differentiation in optics, controls integration, and application-specific engineering rather than raw lumen output alone.
The market also exhibits moderate concentration, with the top three firms capturing roughly 18.5% of revenue and the top five approaching 28.4%. This fragmented yet increasingly consolidated structure indicates that scale advantages exist, but regional expertise, application specialization, and channel relationships still determine competitive outcomes in many geographies. For decision-makers, the central challenge is to balance volume efficiency with the innovation required to stay ahead of tightening standards and shifting buyer expectations.
Key Drivers of Market Change
Technological Innovation and Performance Breakpoints
Advances in LED chip architecture, thermal management, and optical extraction are redefining what a panel light can deliver. The shift toward higher-efficacy packages and improved luminaire-level designs is enabling installations that meet tighter energy codes while reducing the number of fixtures needed for a given illuminance target. Manufacturers are increasingly building panels with tunable-white capabilities, enhanced glare control, and integrated sensing or communication features, transforming the product from a static light source into an active component of smart building ecosystems. These capabilities matter commercially because they allow facility operators to align lighting with occupancy patterns, daylight availability, and wellness objectives without separate retrofit hardware.
Policy and Regulatory Momentum
Government and standards-body initiatives continue to accelerate adoption by raising minimum performance bars and incentivizing commercial retrofits. Updated efficacy requirements for solid-state lighting took effect in early 2026, raising minimum thresholds across categories by roughly 14% and effectively resetting the baseline for compliant products. Alongside these mandates, public and utility-led programs continue to support energy-efficient upgrades in offices, institutions, and industrial facilities. The practical effect is twofold: buyers face stronger reasons to replace aging fixtures now rather than defer upgrades, and suppliers must ensure their portfolios meet or exceed revised benchmarks to remain eligible for incentive-driven procurement.
Demand-Side Behavior Shifts
Buyers are increasingly evaluating lighting as part of a broader total-cost-of-ownership calculation rather than as a standalone commodity. Commercial operators prioritize long lifespans, maintenance reductions, and compatibility with building management systems. Healthcare and institutional purchasers focus on visual comfort, circadian-supportive tuning, and reliable performance in sensitive environments. Residential demand, while smaller in absolute revenue contribution, is growing as homeowners and multi-family developers standardize on flat-panel forms for renovation and new construction, especially where ceiling heights and aesthetic preferences favor low-profile solutions. This diversified demand mix encourages manufacturers to tailor product lines rather than push a uniform offering across segments.
Supply Chain and Cost Structure Evolution
On the input side, the LED component market has experienced sustained price compression as capacity expands and manufacturers transition to larger wafer formats such as 8-inch GaN-on-Si. This shift supports lower assembly costs and enables more aggressive pricing in volume segments. At the same time, sourcing of critical materials remains sensitive to trade policy and licensing conditions, creating pockets of uncertainty for product lines heavily dependent on specific raw-material pathways. The net result is a market where cost advantages from components can be partially offset by geopolitical and logistics variability, reinforcing the value of diversified sourcing and forward hedging for larger producers. Recent trade-show presentations have highlighted energy efficiency and human-centric design as recurring themes, reflecting how suppliers are positioning these cost and performance dynamics as competitive differentiators.
Competitive Landscape and Leading Strategies
The competitive field includes established global players with broad portfolios and strong channel presence, alongside regional manufacturers that compete on price, responsiveness, and localized application support. Global leaders with heritage in lighting and component systems emphasize integrated smart controls, high efficacy, and application-optimized designs for offices, retail, and institutional environments. These firms often leverage brand trust, regulatory-compliance track records, and building-system integration capabilities to secure large commercial accounts. Component-oriented suppliers contribute high-performance LED modules and finished panels focused on reliability and commercial/industrial use, while North American manufacturers have built strong positions through established brand portfolios tailored to commercial, institutional, and architectural specifications.
LED Grow Lights Market
In the premium tier, some participants differentiate through advanced optics, tunable white, and human-centric lighting features, targeting architects and design-led projects where visual quality and flexibility carry premium value. Other manufacturers concentrate on energy-efficient solutions for both commercial and residential markets, emphasizing quality, longevity, and integration with building systems. Large industrial and electrical groups extend their reach through dedicated lighting portfolios that serve commercial, industrial, and hazardous-location applications, using existing distribution relationships and engineering support networks to win specification work. In Asia and export markets, cost-effective and mid-tier manufacturers have expanded their footprint by combining affordable pricing with broad product ranges, and specialized producers have carved out niches with customizable high-lumen panels, dimming options, and certification-ready configurations for commercial projects. Others focus on ceiling panel lights and linear systems for architectural and commercial work, maintaining visibility through trade-show participation and international distribution.
The landscape is evolving through a mix of consolidation and differentiation. Larger incumbents are strengthening portfolios through brand breadth, controls integration, and reliability credentials, while regional players compete by aligning product specifications closely with local code requirements, price sensitivity, and application needs. New entrants tend to succeed when they address specific gaps rather than attempting head-on competition across the entire spectrum. Recent market activity illustrates how firms are positioning themselves: one manufacturer emphasized energy efficiency and human-centric design in panel and linear solutions at a major Frankfurt fair, signaling an industry-wide pivot toward performance-plus-wellness narratives. Simultaneously, updated technical requirements for solid-state lighting raised efficacy thresholds by approximately 14%, compelling portfolio upgrades and creating a natural filter that favors suppliers with stronger R&D and faster compliance cycles. For buyers, the implication is that specification value increasingly resides in verified performance, interoperability, and documentation quality, not just initial price.
Future Outlook: Three Trends Shaping the Next 3–5 Years
The first trend is mainstream human-centric and tunable lighting. As circadian-supportive features and daylight-aligned tuning move from niche to standard expectations in commercial, healthcare, and higher-end residential projects, manufacturers that can deliver reliable color consistency, intuitive controls, and documented visual-comfort benefits will capture premium specifications. The commercial opportunity lies in bundled offerings that pair panels with sensing, scheduling, and integration tools, reducing the need for separate retrofit layers.
The second trend is controls and interoperability as a core product attribute rather than an add-on. Building operators increasingly want lighting that communicates with energy-management platforms, occupancy sensors, and daylight-harvesting systems. Products designed from the outset for interoperability will gain preference in specification work, particularly where efficiency mandates and operational cost pressures make integrated automation attractive. The opportunity is to streamline commissioning and data visibility so that lighting contributes measurable savings and maintenance intelligence.
The third trend is regional diversification of supply and product strategy. Given continued sensitivity around critical materials and shifting trade frameworks, participants are likely to expand multi-source procurement, adjust regional assembly footprints, and tailor portfolios to local code trajectories. For manufacturers, this creates opportunities in application-specific designs and localized compliance documentation. For buyers, it rewards suppliers with transparent sourcing and resilient delivery models. The principal risk is that tighter standards and material constraints could compress margins for undifferentiated products, while rapid product cycles may challenge inventory planning if demand shifts faster than forecasts anticipate.
PW Consulting
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with revised efficacy benchmarks and application-specific value propositions. Investing in optics, thermal design, and controls-ready architectures will protect eligibility for incentive-driven commercial work and support premium positioning where visual quality and wellbeing matter. Diversifying component sourcing and locking in compliant SKU transitions will reduce exposure to material and regulatory friction.
For investors, the most durable opportunities sit with suppliers that combine verified performance, interoperability, and regional execution capability. Preference should be given to businesses that can demonstrate repeatable compliance, clear differentiation beyond price, and the ability to serve both broad commercial accounts and specialized application niches. Monitoring portfolio refresh cycles and certification readiness is a useful leading indicator of resilience.
OLED Lighting Panels Market
For procurement and specification teams, the practical value lies in evaluating total cost of ownership, including energy performance, maintenance intervals, and integration effort, rather than minimizing upfront unit price. Verifying documentation, interoperability claims, and warranty terms will reduce long-term operational risk. Given the pace of regulatory change and portfolio evolution, maintaining access to detailed segment-level data and tailored procurement guidance can materially improve specification choices and budget planning, particularly when projects span multiple codes and application requirements.
Detailed breakdowns by region, product type, application, and competitive positioning can help translate these market-level dynamics into project-level decisions. Comprehensive research covering submarket sizes, adoption trajectories, and company-specific positioning is available for teams that need granular inputs for budgeting, sourcing, and strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide LED Panel Lights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Beauty Hyaluronic Acid Injection Market: 9.4% CAGR and Strategic Shifts Redefining Global Growth
By pmarketresearch, 2026-09-18
The Worldwide Medical Beauty Hyaluronic Acid Injection Market: Strategic Trends and Commercial Opportunities
At $6.45 billion in 2025, the global medical beauty hyaluronic acid injection market has transitioned from a niche aesthetic niche to a core pillar of the broader wellness and anti-aging economy. Over the past five years, steady expansion has been driven by rising disposable incomes, aging demographics, and the normalization of minimally invasive procedures. Forward projections indicate the market will approach $12.08 billion by 2032, reflecting a compound annual growth rate of 9.38 percent. This trajectory signals sustained demand, but it also underscores a landscape that is maturing rapidly. Growth is no longer solely a function of volume; it is increasingly shaped by product differentiation, regulatory navigation, and the ability to balance clinical performance with patient expectations. For executives and investors, the next phase will reward those who can read structural shifts rather than simply track headline numbers.
Navigating the Current Landscape: Scale, Shifts, and Pressures
The market today operates at a scale that commands strategic attention across multiple geographies and business models. Growth has been broad-based, but the composition of that growth is uneven. Regions with established aesthetic treatment cultures continue to anchor demand, while emerging markets are accelerating adoption through expanding clinic networks, rising middle-class spending, and greater access to trained practitioners. At the same time, the competitive field is consolidating around a small group of companies that collectively hold a majority share of the market. This concentration reflects the capital intensity of development, the importance of regulatory track records, and the value of established distribution relationships. Yet concentration does not guarantee uniform success; it raises the bar for differentiation and operational execution.
Three structural pressures are reshaping how companies compete and how purchasers evaluate options. First, the distinction between clinical credibility and aesthetic preference is narrowing. Patients and providers increasingly expect injectables that deliver visible results while preserving natural movement and minimizing downtime. Products that cannot articulate a clear positioning around longevity, integration, or dynamic tissue compatibility face margin pressure and substitution risk. Second, regulatory pathways are becoming more granular. Approval in one market does not automatically translate into commercial traction in another, and indications, labeling, and post-market expectations vary enough to affect launch sequencing and inventory strategy. Third, the raw material layer is tightening. Medical-grade hyaluronic acid is no longer a commodity input; pricing dispersion, availability, and quality thresholds are reshaping cost structures and forcing manufacturers to make deliberate choices about sourcing, formulation, and scale.
These pressures are not abstract. They influence pricing power, portfolio design, channel strategy, and the pace at which new entrants can establish a foothold. The market is large enough to absorb multiple winners, but it is also selective enough to marginalize undifferentiated offerings. The companies that thrive will be those that treat these dynamics as design constraints rather than background noise.
Core Drivers Reshaping the Market
Several forces are converging to redefine growth patterns and competitive advantage. The first is technical innovation in product architecture. The industry is moving beyond volume restoration alone toward formulations engineered for specific tissue environments and treatment goals. Differences in crosslinking, particle characteristics, and rheological behavior are increasingly used to signal fit for distinct clinical scenarios, from deep structural support to fine line correction and dynamic facial areas. This evolution is visible in how leading portfolios are positioned and in the scientific discourse at major aesthetic congresses, where manufacturers are emphasizing natural movement, integration, and long-term performance as key value propositions. The strategic implication is clear: innovation is shifting from broad claims to targeted clinical utility, and that shift changes how products are priced, prescribed, and adopted.
PW Consulting
The second driver is the regulatory and approval environment. Approval momentum has broadened the menu of available options and expanded the set of treatable indications. Recent approvals have included new hyaluronic acid gels for dynamic wrinkles and folds, as well as expanded indications for existing products in areas such as temple hollowing and infraorbital hollow. These developments matter because they do more than add SKUs; they alter treatment protocols, support practitioner education, and create new commercial pathways. For manufacturers, regulatory progress can unlock revenue faster than product development alone, but it also requires disciplined launch execution and clear communication around appropriate use. For clinics and buyers, a wider approved set of products can improve access and choice, while also increasing the need for training and protocol alignment.
The third driver is demand-side behavior. The consumer base has become more informed and more selective. Patients are comparing outcomes, longevity, downtime, and provider expertise rather than treating injectables as interchangeable commodities. This maturity is reinforced by the visibility of treatments on social platforms, the growth of reputable clinic networks, and a broader cultural shift toward preventative and maintenance-oriented aesthetics. For businesses, the implication is that marketing and sales cannot rely on category awareness alone. Differentiation must be supported by clinical data, consistent practitioner experience, and post-procedure credibility. Providers, in turn, are gravitating toward products and platforms that help them manage expectations, reduce complication risk, and maintain repeat demand.
The fourth driver is the supply-side and cost structure, especially around raw materials. Medical-grade hyaluronic acid now spans a wide price range depending on molecular weight, purity, and endotoxin limits, and the underlying raw material market is expanding as demand rises. In parallel, the commercial standard has shifted toward non-animal microbial fermentation-sourced HA for regulated applications, reducing variability and contamination risk but also consolidating the supplier base around manufacturers that can meet stringent quality requirements. This transition has two consequences. It raises the importance of supply reliability and technical control, and it gives an advantage to companies that can stabilize cost inputs while maintaining product performance. For vertically integrated players, raw material capability can become a source of margin resilience. For others, it becomes a negotiation and risk management priority.
Competitive Landscape and Leading Strategies
The market is anchored by a set of established companies that have built recognition around distinct product families, indications, and clinical narratives. AbbVie, through its JUVÉDERM collection, continues to use volume restoration and facial contouring as a foundation while pushing a more advanced narrative around undetectable, natural-looking outcomes in dynamic facial areas. Galderma has reinforced the Restylane portfolio with NASHA and OBT technology and has recently advanced syringe technology across facial and hand indications, improving handling and treatment consistency. Merz markets the Belotero range with an emphasis on integration into facial tissue for moderate to severe wrinkles and folds, while Teoxane has built its RHA collection around resilient formulations designed for natural movement. Each of these players has chosen a different point of emphasis, reflecting the reality that success depends on more than scale alone.
The field also includes companies using regulatory approvals and targeted launches to gain traction. Evolus introduced the Evolysse collection for dynamic facial wrinkles and folds after securing approval, creating an entry point into the U.S. market with a defined clinical focus. Hugel supplies fillers for global aesthetic markets and has continued to expand its international presence. Bloomage and LG Chem represent manufacturers with strong material and product capabilities, while Shanghai Haohai, HTL Biotechnology, and several other suppliers contribute to a broader ecosystem spanning raw material production and finished devices. This mix shows that the market supports both brand-led portfolio strategies and material-focused supply models, depending on capital, regulatory readiness, and geographic ambition.
Latest developments reinforce how competitive dynamics are playing out. At the 2026 Aesthetic & Anti-Aging Medicine World Congress, AbbVie framed the next phase of HA injectables around an “Undetectable Era,” signaling a shift toward outcomes that resist visible overcorrection. Galderma secured approvals across the EU, U.S., and Canada for a new Restylane syringe for use with its NASHA lidocaine range, an operational improvement that can affect clinician adoption and treatment workflow. Separately, Waldencast entered the U.S. market after FDA approval of Obagi saypha MagIQ, and Evolus launched Evolysse Form and Smooth following FDA approval, illustrating how approvals and launches are opening entry points even in a concentrated market. These moves suggest that incumbents are defending share through evolution and that new entrants are pursuing focused, indication-led openings rather than broad disruption.
The landscape is likely to continue splitting between consolidation and specialized entry. Consolidation favors companies that can combine regulatory credibility, distribution reach, and portfolio breadth. But it also creates room for specialized players if they can demonstrate a clear clinical fit, manage supply and quality, and build practitioner trust. The differentiating factors will increasingly be formulation intelligence, indication alignment, delivery experience, and the ability to support training and consistent outcomes. In that environment, broad presence is useful, but precise positioning is decisive.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape strategy. The first is the continued shift from generalized fillers to indication-specific and movement-aware products. As practitioners become more selective and patients more educated, formulations that align with tissue behavior and treatment zones will gain preference. This creates opportunities for companies that can demonstrate differentiated performance in defined clinical scenarios and that can support training, labeling, and protocol design accordingly.
The second trend is regulatory-driven expansion of usable indications and product formats. As approvals add new treatment areas and as delivery features improve, the addressable use cases will widen. That growth is commercially valuable, but it also introduces complexity in education, inventory planning, and post-market compliance. Businesses that can synchronize product launches with practitioner education and clear usage guidance are more likely to convert approval momentum into sustained adoption.
The third trend is supply-side refinement. As medical-grade HA continues to move toward fermentation-based sourcing and stricter purity standards, procurement resilience and cost discipline will become more important. Companies with stable material access and consistent quality will have an advantage in pricing and launch reliability, especially if raw material pricing remains variable. This also means that vertical integration, long-term supplier relationships, and formulation control will be increasingly strategic rather than optional.
These trends carry both opportunity and risk. Demand appears durable, but growth can be uneven across markets, indications, and provider types. Regulatory success does not guarantee commercial success if launch execution, education, and distribution are weak. And while innovation creates premium positioning potential, over-segmentation can complicate supply and slow scale if portfolios become too fragmented. The most resilient strategies will balance clinical specificity with operational simplicity.
Hyaluronic Acid Market
Strategic Actions for Decision-Makers
For manufacturers and brand owners, the priority is to sharpen product positioning around clear clinical use cases and to align formulation, delivery, and education with those use cases. A focused portfolio that maps to practitioner needs and patient expectations is more likely to defend pricing and build repeat use than an undifferentiated expansion strategy. Equally important is supply resilience: securing predictable access to medical-grade raw materials and maintaining quality control should be treated as a competitive capability, not just a procurement task.
For investors, the opportunity lies in identifying companies with credible regulatory records, defensible formulation or delivery advantages, and realistic launch execution plans. Market growth is strong, but returns will depend on execution quality, concentration dynamics, and the ability to convert approvals into uptake. Due diligence should therefore weigh indication strategy, supply security, and go-to-market discipline as closely as headline market size.
For clinics, procurement teams, and treatment providers, the practical imperative is to standardize evaluation around outcomes, safety, handling, and indication fit rather than price alone. Selecting products that match the intended treatment zone and supporting them with consistent training can reduce variability and improve patient satisfaction. On the purchasing side, building relationships with suppliers that demonstrate quality consistency and launch reliability will help manage supply risk as the market matures.
Hyaluronic Acid Dermal Filler Market
As the market scales toward the $12 billion range by 2032, the strategic edge will belong to organizations that can integrate technical differentiation, regulatory execution, and supply discipline into a coherent commercial model. For decision-makers seeking deeper segmentation data, competitor benchmarks, and tailored planning inputs, the full PW Consulting research report provides the detailed breakdown needed to translate these trends into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Beauty Hyaluronic Acid Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Far Infrared Fabric Revolution: Strategic Trends and Commercial Opportunities in a $1.3 Billion Market
Market Overview: Growth Trajectory and Structural Challenges
The global far infrared (FIR) fabric market has evolved from a niche experimental segment into a substantial commercial category, demonstrating consistent expansion over the past half-decade. Valued at approximately $540 million in 2020, the market crossed the $785 million threshold in 2025 and is projected to reach $1.35 billion by 2032, reflecting a compound annual growth rate of roughly 8 percent. This trajectory signals that infrared-integrated textiles are no longer confined to emerging wellness trends but have established themselves as a viable functional material category across multiple consumer and industrial verticals.
Despite this momentum, the sector faces structural friction that separates sustainable growth from speculative hype. One pressing challenge revolves around claim validation and regulatory fragmentation. Far infrared textiles operate through emissivity mechanisms that depend on ceramic nanoparticle integration, mineral compounding, or graphene loading, but translating laboratory emissivity results into reproducible end-user performance remains difficult. Standards such as GB/T 30127-2013 are referenced in select markets, yet buyers encounter divergent certification requirements across regions. A product validated for temporary local circulation support in one jurisdiction may face entirely different claim constraints in another, forcing manufacturers to navigate multiple compliance pathways before scaling commercial rollouts.
A second challenge lies in balancing functional efficacy with cost structures. Graphene-enhanced variants and high-loading ceramic composites typically command price premiums of fifteen to forty percent over conventional performance fabrics. While melt-spinning processes can maintain mechanical stability across more than one hundred fifty wash cycles, achieving that durability requires precise compounding control and consistent polymer integration. Fabricators that underinvest in production discipline risk losing the thermal and circulatory benefits that justify the premium in the first place, eroding customer trust and margin resilience over time.
A third issue concerns market concentration and competitive differentiation. The top three participants collectively account for approximately thirty-two percent of global revenue, while the top five reach just under half of total market value. This distribution indicates a landscape where established players hold meaningful share but still leave considerable room for regional specialists and innovators. The strategic risk for incumbents is complacency in product iteration, while newer entrants must differentiate beyond ingredient marketing and prove that their FIR yarns or finished fabrics deliver measurable benefits in real-world use cases such as active recovery, thermal comfort, or sleep support.
Key Drivers Shaping the FIR Fabric Landscape
Technological Innovation and Material Breakthroughs
Materials science continues to reshape what far infrared textiles can deliver. Ceramic-infused polyester remains the dominant fiber architecture, while carbon and graphene-infused variants and bio-ceramic nylon are expanding the functional envelope. Advances in polymer nanotechnology allow manufacturers to refine mineral powders derived from gemstones, volcanic mud, or engineered ceramics and embed them more uniformly within base fibers during melt-spinning or polymerization. The result is a set of yarns and fabrics that can absorb body heat or ambient energy and re-emit it within the eight-to-twelve micrometer range, supporting perceived improvements in circulation, recovery, and thermal comfort.
Recent commercial activity underscores how material innovation is moving from R&D benches into branded product lines. In April 2025, The LYCRA Company promoted its THERMOLITE® FAR INFRARED technology for socks and legwear, emphasizing lightweight hollow fibers with permanent ceramic pigments designed to harness body infrared energy for gentle warming. This launch intersected with broader retail collaborations involving NEXT jeans and H&M collections featuring related infrared technologies, illustrating how fiber-level innovation is being translated into mainstream apparel categories rather than remaining confined to specialty therapeutic products.
Regulatory Clarity and Claim Environments
The regulatory landscape is increasingly shaping how FIR fabrics are positioned and sold. CELLIANT® infrared technology, for instance, has been determined as a general wellness product and reviewed under the FDA 513(g) process for appropriate claims regarding temporary increase in local circulation in healthy individuals. In parallel, the technology has been designated a Class 1 Medical Device in multiple markets including the EU, Japan, the UK, and Australia, with additional clearance pathways pursued in regions such as China. This layered classification structure creates both opportunity and complexity. Manufacturers that proactively align product claims with recognized regulatory categories can build stronger credibility with retailers, healthcare-adjacent buyers, and performance-focused consumers.
Simultaneously, the emphasis on third-party lab certifications and emissivity testing is becoming a differentiator in buyer evaluation. As markets reference testing protocols such as GB/T 30127-2013 and require documented emissivity performance, suppliers that invest in transparent validation can separate themselves from competitors relying on vague wellness assertions. This shift favors companies capable of supporting marketing narratives with repeatable test data and consistent production quality.
Demand-Side Shifts Across Consumer and Institutional Channels
Demand for far infrared fabrics is expanding through converging consumer and institutional behaviors. Performance-oriented consumers increasingly look for apparel that supports circulation, recovery, and thermal comfort without adding bulk or sacrificing breathability. In healthcare and therapeutic settings, textile buyers are exploring functional fabrics that can complement rest, rehabilitation, and patient comfort protocols. At the same time, home textiles and sleep-focused products are drawing interest from shoppers seeking non-invasive comfort enhancement in bedding and loungewear.
This demand diversification is visible in how manufacturers are broadening their SKU and service offerings. In May 2025, Sportingtex highlighted customizable FIR fabric options with certified technology for sportswear, health tech, and apparel, stressing OEM/ODM capabilities, sustainable production practices, and proven wellness benefits. Earlier catalog activity from other players reflects similar positioning, with FIR yarns being adapted for athletic wear, medical care, pet apparel, equestrian gear, and bedding. The practical implication is clear: FIR fabrics are crossing from single-purpose therapeutic niches into multi-category functional textiles, which expands total addressable demand but also raises the bar for category-specific performance validation.
Worldwide Heated Fabric Market
Supply-Side and Cost Structure Dynamics
Supply chain considerations are becoming more decisive as the market scales. Far infrared fabrics commonly incorporate ceramic nanoparticles, mineral powders, or graphene into polyester or nylon via melt-spinning or polymerization. The quality of this integration directly affects emissivity consistency, wash durability, and end-product cost. Suppliers that master compounding uniformity and process control can maintain mechanical properties across repeated laundering while preserving functional claims, whereas weaker process discipline leads to variability that undermines performance reliability.
Cost structure dynamics are also evolving as premium materials become more embedded in mainstream categories. Graphene-enhanced variants can add a substantial price premium, so commercial success depends on pairing the material upgrade with defensible value: thermal retention in cold-weather apparel, recovery support in activewear, or comfort benefits in sleep and therapeutic products. At the same time, sustainability pressures are encouraging EcoMade variants and resource-efficient manufacturing approaches, which can be leveraged as secondary differentiators when positioned carefully alongside functional performance rather than as standalone marketing claims.
PW Consulting
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field in far infrared fabrics is diverse, spanning medical-device-aligned innovators, performance fiber specialists, and regional textile manufacturers with strong OEM/ODM capabilities. Hologenix, LLC, through its CELLIANT® technology, occupies a distinctive position by embedding a proprietary blend of natural minerals into fibers, yarns, and fabrics and by pursuing regulatory recognition across multiple markets. Its status as a Class 1 Medical Device in the EU, Japan, the UK, and other regions provides a credibility anchor, while its focus on performance, recovery, and sleep applications gives it relevance in both wellness and athletic recovery segments.
The LYCRA Company differentiates through THERMOLITE® FAR INFRARED fiber and technology, using lightweight hollow fibers with permanent ceramic pigments to deliver gentle warmth in legwear, socks, hosiery, activewear, denim, and outerwear. Its emphasis on permanent warming performance and sustainability-oriented EcoMade variants reflects a strategy that pairs functional benefits with mainstream apparel compatibility. Hitek Textile Co., Ltd. takes a different approach, specializing in SiTEX® FIR Yarn and related jacquard, lace, and tricot knit fabrics that use over twenty natural minerals refined with polymer nanotechnology for energized resonance effects, while offering patented yarn and OEM/ODM services for global brands.
Regional manufacturers such as NUREL Synthetic Fibers, Sportingtex, Acelon, and FIRBEST Co., Ltd. illustrate how localized expertise can translate into strong category niches. NUREL produces NERIDE FIR PA6 nylon yarn with gemstone mineral additives aimed at sportswear, therapeutic clothing, sleepwear, and cold-weather use. Sportingtex manufactures far infrared thermal fabrics using ceramic nanoparticles with emissivity values in the 0.83–0.92 range, serving sportswear, medical care, petswear, equestrian applications, and bedding. Acelon supplies AceVitality® medical yarn with far-infrared microelements for healthcare, sports, and rehabilitation textiles with antibacterial and FIR benefits, while FIRBEST produces KODENSHI® functional material with patented compounding technology across multiple countries.
Larger industrial players also participate in the space. Hyosung Corporation develops aerogear far-infrared yarn with embedded minerals for blood circulation benefits, combined with moisture management in polyester yarns. RadiciGroup offers Radilon® Enjoy polyamide fabrics with far-infrared emission properties for energy and wellness benefits, and Energy Textiles, LLC manufactures Radiance™ far-infrared textiles using ceramic particles in yarn to recycle body energy and support performance, recovery, and sleep products.
The strategic pattern across leading players is divergence in how they convert material science into commercial trust. Some emphasize regulatory alignment and medical-device-adjacent positioning, others prioritize fiber architecture and wash durability, and still others lean on OEM/ODM agility and application breadth. This fragmentation is likely to evolve in two directions. First, consolidation may accelerate as larger textile and fiber groups seek to internalize FIR capabilities and reduce reliance on single-source specialty suppliers. Second, new entrants may continue to emerge around specific applications such as athletic recovery, sleep comfort, therapeutic textiles, or even pet and equine segments, where narrower use cases allow faster proof-of-value. The winners will be those that combine reproducible emissivity performance, credible claim management, and reliable production scale rather than ingredient novelty alone.
Future Outlook: Trends and Commercial Implications for the Next Three to Five Years
One defining trend over the next several years will be the migration of far infrared fabrics from specialty wellness products toward broader functional textiles with more rigorous claim discipline. As buyers in apparel, home textiles, and therapeutic channels demand third-party validation and repeatable emissivity performance, the market will likely reward suppliers that can standardize testing, documentation, and production controls across SKUs. This creates commercial opportunities for manufacturers that can offer certified, application-specific fabric systems rather than generic “infrared” labels, especially in activewear, sleep products, and medical-adjacent textiles.
A second trend is the increasing layering of functional benefits. Far infrared is rarely evaluated in isolation anymore; it is being combined with moisture management, thermal regulation, antibacterial properties, and sustainability-oriented fiber choices. This convergence opens doorways for differentiated product architectures, such as hollow-fiber warming platforms paired with FIR emissivity, or polyamide systems that blend circulation-support benefits with rehabilitation and cold-weather performance. Companies that design around benefit stacking and category-specific use cases are better positioned to command price premiums without relying solely on raw material cost justification.
A third trend involves geographic and channel expansion, particularly where regulatory pathways and testing practices are becoming more defined. Markets that emphasize emissivity standards and recognize wellness or Class 1 device frameworks can provide faster routes to retail and institutional adoption, while regions with less harmonized claim environments may require longer education cycles. The strategic opportunity lies in matching product positioning to the destination market’s validation expectations early rather than retooling claims after launch. Still, uncertainty remains. Overstatement of health benefits, inconsistent wash durability, and fluctuating raw material costs can all weaken category credibility if not managed carefully. Premium pricing also introduces exposure to consumer sensitivity in cost-conscious segments, meaning that value communication must be precise and evidence-aligned.
Strategic Recommendations for Decision Makers
For manufacturers and fabric developers, the immediate priority is to make emissivity performance and wash durability measurable, repeatable, and transparent across product lines. Investing in compounding control, third-party validation, and application-specific testing will do more to protect margins than expanding ingredient claims. Where premium materials such as graphene or high-loading ceramics are used, the value proposition should be tied to clearly defined benefits in the target application, whether that is thermal warmth in legwear, recovery support in activewear, or comfort in sleep textiles.
For investors, the most attractive opportunities are likely to emerge where companies combine credible regulatory or validation positioning with scalable production and a diversified application base. Pure ingredient novelty is increasingly insufficient; commercial resilience depends on documentation, OEM/ODM flexibility, and the ability to serve multiple channels without diluting performance consistency. Due diligence should therefore focus on testing discipline, claim management, and the durability of differentiating technologies under repeated use and laundering.
For procurement and sourcing teams, the practical move is to evaluate FIR suppliers against reproducibility and compliance readiness rather than marketing language alone. Request emissivity data, wash-cycle performance evidence, and regulatory or certification alignment relevant to the end market. Where customization matters, prioritize partners with proven OEM/ODM capabilities and a track record of maintaining functional properties across batches. Given the pace of product launches, catalog expansions, and regulatory developments across the category, timely access to detailed segmentation data, competitive benchmarks, and market-specific entry information can materially improve sourcing and investment decisions. Readers seeking deeper segmentation detail, company-level comparisons, and region-level market data may find value in the full PW Consulting market report, which provides the supporting structure needed to translate these strategic themes into operational choices.
Worldwide Infrared Massage Therapy Bed Market
For detailed analysis of this topic, please visit the official page: Worldwide Far Infrared Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com