

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Air Beds Market Hits $340M in 2025: 7.9% CAGR and Asia Pacific Reshaping Revenue by 2032

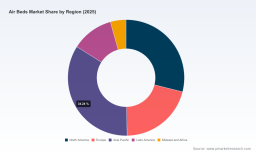
Strategic Trends and Commercial Opportunities in the Air Beds Market
Market Overview: Scale, Trajectory, and Structural Realities
The global air beds market has evolved from a niche hospitality and camping accessory into a diversified commercial category shaped by shifting sleep preferences, flexible accommodation models, and incremental engineering improvements. Between 2020 and 2025, the market expanded from roughly 230 million USD to 340 million USD, reflecting a compound annual growth rate of 7.9 percent over the broader forecast window through 2032. By the end of the projection period, revenue is expected to approach 575 million USD, indicating sustained demand expansion rather than a temporary post-pandemic rebound. This trajectory suggests that air beds are no longer treated as disposable substitutes but are increasingly evaluated against conventional foam, innerspring, and hybrid sleep surfaces on the basis of portability, space efficiency, and targeted comfort performance.
The composition of demand reveals a market in transition. Household applications continue to anchor the majority of revenue, driven by guest accommodation, apartment living, and multi-purpose room setups where floor space is at a premium. Commercial deployments represent a meaningful secondary channel, with hospitality operators, event organizers, and emergency housing providers leveraging air beds for rapid scalability and reconfiguration. The product mix remains bifurcated: one segment emphasizes consumer-grade mattresses designed for prolonged home or guest use, while the other focuses on traditional air beds optimized for temporary deployment, travel, and outdoor recreation. This divergence matters because each segment faces distinct performance expectations, margins, and replacement cycles.
Concentration levels underscore the strategic importance of brand position and distribution reach. A small group of established players controls a substantial share of revenue, particularly in the consumer category, where repeat purchases, retail visibility, and brand trust heavily influence category growth. At the same time, the market has not reached full consolidation, leaving room for specialized manufacturers, regional distributors, and performance-oriented entrants to carve out defensible niches. The reality on the ground is therefore one of measured expansion layered with structural friction: strong top-line growth coexists with pricing pressure, substitutability concerns, and uneven channel performance across segments.
PW Consulting
Key Challenges and Inflection Points
The most pressing challenge is the tension between convenience and long-term performance perception. Air beds have historically been associated with temporary use, and many buyers still hesitate to treat them as primary sleep surfaces. This perception cap limits penetration in households seeking durable, everyday comfort solutions. Overcoming it requires more than incremental softness improvements; it demands demonstrable durability, stable support under repeated inflation cycles, and clear differentiation from low-cost, short-lived alternatives that damage category credibility.
A second inflection point involves channel fragmentation and the shifting economics of trial and return. In online-first retail, buyers increasingly expect easy testing, clear product descriptions, and reasonable return policies. For bulky or inflatable products, logistics costs and return rates can erode margins quickly, especially when specifications are ambiguous or when products are positioned too close to conventional mattresses without clear justification. Companies that cannot align product messaging, packaging, and fulfillment with digital purchasing behavior risk losing share to brands that make the buying decision simpler and more predictable.
The third challenge is regulatory and sustainability scrutiny around materials and end-of-life handling. As consumer awareness of product composition grows, manufacturers face increased pressure to justify material choices, reduce environmental footprints, and avoid over-reliance on formulations that invite reputational or compliance risk. This is not yet a uniform market requirement, but it is becoming a differentiator in premium segments and in procurement environments where sustainability criteria influence vendor selection. Companies that address this proactively can use it as an entry point into higher-margin channels, while laggards may find themselves excluded from bids or retail listings that increasingly factor in material transparency.
Core Drivers Shaping Market Direction
Technological Advancements and Performance Engineering
The most tangible driver of category evolution is engineering progress in support stability, air retention, and integrated convenience features. Modern designs increasingly combine internal coil structures, layered fiber or fabric systems, and refined valve or pump mechanisms to address long-standing complaints about sagging, leakage, and uneven pressure distribution. These improvements matter because they shift the product narrative from temporary convenience to viable comfort support, especially for guest rooms, multi-use spaces, and short-term lodging. Pumping technology has also become more integrated and quieter, reducing friction in setup and improving usability for both consumer and commercial settings.
Several established manufacturers illustrate this trajectory. Intex Recreation Corp. has emphasized fiber-tech construction and high air retention in consumer-oriented lines, reinforcing the idea that air-based products can deliver more consistent comfort over repeated use. Coleman has focused on leak-resistant airbed cots and raised designs with coil support, targeting outdoor and guest applications where durability and quick deployment are critical. Sound Asleep Products has built its Dream Series around internal pump integration and eco-friendly PVC construction, reflecting a broader move toward convenience and material-conscious positioning. King Koil Airbeds has pursued a luxury-leaning angle with enhanced coil technology and built-in pumps for guest and home use, demonstrating how elevated support claims can support higher price points. These product directions are not isolated; together they signal a market that is rewarding precision, reliability, and clearer use-case positioning.
Policy, Regulation, and Procurement Standards
Policy and procurement environments are becoming more influential as buying decisions move beyond pure price comparison. In commercial and institutional settings, procurement teams increasingly evaluate durability, maintenance requirements, and material documentation alongside upfront cost. Where public or large-scale private buyers incorporate sustainability, safety, or vendor qualification criteria, air bed suppliers that can provide consistent specifications and reliable compliance narratives gain an advantage. This does not mean regulation is changing the market overnight, but it is raising the floor for what qualifies as an acceptable commercial product in certain channels.
At the same time, labeling and material disclosure expectations are gradually shaping consumer confidence. Buyers are more likely to engage with brands that communicate construction details clearly, especially when a product is positioned as suitable for longer-term guest or household use. This trend favors companies that invest in straightforward product storytelling and consistent quality control, while penalizing those that rely on vague comfort claims without supporting design or manufacturing discipline.
Hospital Beds Market
Demand-Side Shifts in Consumer and Commercial Behavior
Demand is increasingly shaped by space constraints, flexible living arrangements, and the normalization of temporary or multi-purpose furniture. In urban and rental-heavy housing markets, consumers value products that can be stored compactly, deployed quickly, and repurposed across guests, travel, or seasonal needs. This supports continued household demand, particularly where bedrooms are shared or where a secondary sleeping surface must be available on demand. At the same time, consumer expectations for comfort have risen, meaning that basic inflatable products face tougher competition from designs that approximate the feel of more traditional sleep surfaces.
On the commercial side, the relevance of air beds depends on operational flexibility. Hospitality operators, event providers, and overflow accommodation managers value products that can be installed rapidly, sanitized or replaced with minimal downtime, and adapted to varying occupancy patterns. This creates recurring demand in settings where speed and reconfigurability matter more than permanent bed infrastructure. Glamping and outdoor lodging concepts have also expanded the commercial-use conversation, with brands such as Zempire emphasizing durable bases and stretch fabrics for outdoor and renovated camping environments. Such use cases illustrate how commercial demand can stretch beyond traditional hospitality and into experience-led accommodation models.
Air Springs Market
Supply Chain and Cost Structure Dynamics
Cost structures remain sensitive to materials, manufacturing consistency, and outbound logistics. Inflationary pressure on components and freight has periodically squeezed margins, especially for lower-priced products where cost differentiation is already narrow. In response, manufacturers have leaned more heavily on design efficiency, localized product variation, and packaging optimization to protect viability without undermining perceived value. Supply chain resilience has also become a strategic consideration, as disruptions can quickly affect retail availability and commercial replenishment cycles.
For both consumer and commercial players, the practical implication is that total cost of ownership is increasingly important. A cheaper unit with higher failure or replacement frequency may be less attractive than a slightly more expensive option with better durability and lower service burden. This shifts attention toward engineering consistency, quality assurance, and after-sale support, especially for commercial buyers managing multiple units across locations.
Competitive Landscape and Strategic Positioning
The market is anchored by a set of recognizable manufacturers with distinct positioning. Intex Recreation Corp. maintains a strong consumer-facing presence through product lines that emphasize comfort features and practical inflation performance, supported by broad retail familiarity. Coleman leverages its outdoor and seasonal brand equity to compete in recreational and guest-use segments, where leak resistance and straightforward setup are valuable selling points. Sound Asleep Products and King Koil Airbeds both pursue more comfort-oriented narratives, but with different emphases: one leans into integrated convenience and material-conscious construction, while the other targets a higher-end feel with enhanced coil support and built-in pumps for home and guest applications.
Beyond the consumer core, specialized players add differentiation through use-case focus. Zempire has positioned itself in glamping and outdoor applications with durable bases and stretch fabrics, an approach that aligns with experience-led lodging and camping demand. Pittman Outdoors has built relevance through vehicle-specific and truck bed air mattress solutions, an example of how niche adjacency can create defensible demand where general-purpose products are less optimized. Together, these companies illustrate that competitive advantage in this market is rarely about scale alone; it is often about how precisely a brand aligns product design, messaging, and distribution with a defined purchasing context.
Looking forward, the competitive landscape is likely to evolve along two parallel tracks. One track involves continued brand consolidation among broad consumer manufacturers that can compete across retail channels, manage product complexity, and sustain visibility in high-traffic categories. The other track favors targeted entrants and regional players that serve specific applications well enough to command better margins and stronger buyer loyalty. There is also room for private-label and procurement-oriented supply relationships, especially where commercial buyers prioritize specification consistency over brand recognition. The market is therefore unlikely to become monochromatic; instead, it will probably become more segmented, with winners defined by application fit as much as by product features.
Future Trends and Commercial Opportunities
Performance-Driven Premiumization in Household Use
One of the clearest medium-term trends is the gradual push toward more performance-oriented household products. As buyers become more comfortable evaluating air-based sleep surfaces for guest rooms and secondary bedrooms, manufacturers that can deliver stable support, low maintenance burden, and credible durability will have an opening to expand into higher-value positions. This trend creates opportunities for products that combine inflatable convenience with more conventional comfort expectations, particularly where integrated pumps, reinforced support structures, and clearer warranty or quality messaging reduce purchase risk. The commercial implication is straightforward: brands that can convincingly bridge the gap between temporary use and everyday comfort can capture willingness to pay that basic models cannot.
Expansion of Commercial, Experience-Led, and Flexible Accommodation Demand
Commercial demand is expected to remain important, but its composition may shift toward experience-led and flexible lodging contexts. Glamping, boutique outdoor retreats, event overflow, and short-term accommodation operators all value products that are quick to deploy, easy to maintain, and adaptable to changing occupancy. This creates opportunities for suppliers that can package products with operational reliability in mind, including consistent specifications, manageable storage profiles, and designs suited to repeated use. The broader opportunity lies in serving buyers who need sleep infrastructure that behaves more like flexible furniture than permanent fixtures, especially in settings where space and turnover are central constraints.
Material, Sustainability, and Procurement-Aligned Product Narratives
A third trend is the growing importance of material transparency and procurement-friendly positioning. As buying committees and retail gatekeepers pay closer attention to product composition, manufacturing consistency, and end-of-life considerations, companies that communicate clearly and maintain disciplined quality standards will be better placed to access premium retail listings and institutional buyers. This does not require dramatic reformulation across the board, but it does reward coherent product stories, controlled sourcing, and evidence-based claims. Businesses that treat sustainability and documentation as strategic assets rather than compliance overhead may find new access points in channels where trust and traceability increasingly influence purchasing decisions.
Risks and Uncertainties
Several uncertainties could shape how these trends play out. Consumer willingness to pay for upgraded air beds may stall if broader inflation or housing cost pressures tighten discretionary budgets, particularly in segments where air beds compete with lower-cost furniture alternatives. Substitution risk also remains relevant, as improved foam, hybrid, and modular sleep products continue to evolve and may capture buyers seeking permanent solutions. In commercial settings, demand can be sensitive to occupancy cycles, event activity, and procurement budget shifts, making revenue less predictable than in steady-state household use. Finally, any erosion in perceived product durability or inconsistent quality across batches could quickly weaken category confidence, especially in online channels where reviews and returns amplify negative experiences.
Strategic Implications for Decision-Makers
For Manufacturers
Product strategy should begin with use-case clarity rather than feature stacking. The most defensible positions emerge when a product is designed for a specific purchasing context, whether that is guest-room comfort, outdoor deployment, vehicle compatibility, or institutional repeated use. Once the application is defined, engineering priorities become easier to set: support stability, air retention, pump usability, material consistency, and packaging efficiency can all be tuned to the target buyer instead of diluted across competing demands. Manufacturing discipline matters as much as design ambition, because inconsistent quality in inflatable products quickly undermines trust and increases returns. Brands that invest in clear specifications, repeatable production, and reliable after-sale support will be better positioned to defend margins and expand into higher-value channels.
For Investors
Investment attention should focus on the segments where value creation is most sustainable. Broad consumer exposure can offer scale, but differentiation and channel fit often determine whether a player can maintain pricing power. Smaller, application-focused manufacturers may present more attractive operating leverage if they serve a defined niche with limited direct competition and clear procurement or retail gatekeeper alignment. Commercial-oriented supply relationships can also be attractive where recurring demand, specification reliability, and operational convenience create stickier customer relationships. At the same time, investors should monitor substitution risk and consumer sentiment, because the category's growth depends on continued acceptance of air-based sleep surfaces as more than temporary conveniences. Due diligence should therefore emphasize product consistency, channel economics, and the credibility of performance claims rather than headline category growth alone.
For Procurement and Commercial Buyers
Buying decisions should weigh total cost of ownership alongside upfront price. For household and guest applications, the practical question is whether a product will deliver consistent comfort and acceptable durability over its expected use life, not just whether it is inexpensive at checkout. For commercial deployments, the deciding factors often include storage efficiency, setup speed, sanitation or replacement feasibility, and the ability to standardize units across locations. Buyers benefit from demanding clearer product documentation, consistent specifications, and realistic warranty or replacement expectations, especially when purchasing at volume. Where sustainability or material transparency is relevant to internal procurement standards, it can be used as a screening criterion that narrows the field to suppliers with stronger operational discipline and more reliable documentation.
The air beds market is not expanding simply because consumers are buying more inflatable products; it is expanding because a growing set of households, lodging operators, and experience-driven businesses see air-based sleep surfaces as practical answers to space, flexibility, and deployment constraints. The next phase of value creation will belong to players who make those answers more credible, more durable, and more clearly aligned with real purchasing contexts. For decision-makers seeking to act on these dynamics with segment-level sizing, channel comparisons, and customized positioning guidance, the full research report is available for review.
For detailed analysis of this topic, please visit the official page: Air Beds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com