

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Why ROSA Components Hit $11.1B by 2032: 13.48% CAGR Shifts

Global Market Intelligence: Strategic Trends in the Worldwide Receiving Optical Sub-Assembly Components Market
Market Snapshot: Scale, Momentum, and Structural Headwinds
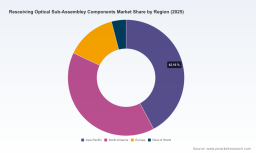
The worldwide market for receiving optical sub-assembly (ROSA) components has transitioned from a specialized supplier niche into a foundational pillar of modern optical communications infrastructure. Valued at approximately $4.58 billion in 2025, the sector has expanded consistently from $2.45 billion in 2020, reflecting a compound annual growth rate of 13.48 percent through the forecast horizon extending to 2032. This trajectory underscores how rapidly receiver sub-assemblies have evolved from peripheral transceiver components to critical enablers of bandwidth scaling, low-latency connectivity, and energy-efficient data transmission. The market's expansion is not merely cyclical; it is structurally reinforced by the parallel growth of optical transceiver volumes, the migration toward coherent and direct-detection architectures at higher data rates, and the continuous densification of fiber-based networks across enterprise, carrier, and cloud environments.
Despite this robust headline growth, the industry is navigating a series of inflection points that will determine margin trajectories, supply chain resilience, and competitive positioning over the next several years. First, the rapid escalation of AI-driven data center workloads is compressing procurement cycles and demanding receiver components that deliver higher sensitivity, broader bandwidth, and tighter integration with transceiver packaging. Traditional ROSA designs optimized for legacy metro or access networks are increasingly misaligned with the performance and form-factor expectations of next-generation optical engines, forcing manufacturers to accelerate material science and packaging innovation while managing yield and cost constraints. Second, geopolitical decoupling and export controls around III-V compound materials and semiconductor manufacturing equipment are reshaping sourcing strategies. Producers reliant on concentrated substrate supply or legacy assembly footprints are encountering longer lead times, pricing volatility, and heightened compliance complexity, making supply chain diversification and regional capacity planning strategic imperatives rather than operational afterthoughts.
Third, the market is experiencing a performance-versus-cost tension that is redefining procurement behavior. As hyperscale operators and system integrators push for lower cost-per-bit and improved power efficiency, receiver suppliers must balance advanced photodiode architectures, amplifier integration, and precision optical alignment against aggressive margin expectations. This dynamic is simultaneously rewarding manufacturers with differentiated process capabilities and pressuring those locked into commoditized assembly models. The net effect is a market that is expanding rapidly in absolute terms but increasingly bifurcated in terms of value capture, where technological readiness, materials access, and integration sophistication determine which players can sustain premium positioning.
Key Drivers Reshaping the Receiving Optical Sub-Assembly Landscape
Technological Innovation and Architectural Shifts
The most immediate driver of market evolution is the convergence of higher data rates, tighter integration, and advanced packaging formats. Receiver sub-assemblies are no longer standalone optical-to-electrical conversion modules; they are increasingly co-designed with transceiver engines, leveraging chip-scale packaging, low-loss optical alignment, and embedded control functionality to meet the latency and power constraints of AI fabric interconnects and high-speed data center links. Innovations in PIN and avalanche photodiode architectures continue to expand the sensitivity and bandwidth envelope, enabling receivers to support emerging modulation formats and extended reach requirements without excessive digital signal processing overhead. At the same time, packaging techniques that improve thermal stability, reduce optical loss, and streamline assembly flow are becoming critical differentiators, allowing suppliers to deliver higher performance within tighter cost and size constraints. Companies that have introduced symmetric, lower-cost chipset approaches and integrated optical sub-assembly optics into broader network solutions illustrate how product portfolios are shifting from discrete component delivery to system-level value creation. Recognition of highly integrated chip-scale packaging and optical sub-assembly products for AI network applications further confirms that the industry is prioritizing compactness, scalability, and performance density over traditional discrete assembly paradigms.
Optical Transceivers Market
Policy, Funding, and Supply Chain Reshaping
Policy momentum is rewriting the geographic and operational calculus for ROSA suppliers. Strategic semiconductor funding initiatives are actively supporting the expansion of indium phosphide substrate and epitaxial wafer production, with investments targeting domestic capacity for lasers and photodetectors used in optical components. These programs are designed to strengthen supply chain resilience for critical optical materials and reduce dependence on concentrated sourcing models. Simultaneously, large-scale equipment orders for metal-organic chemical vapor deposition and related epitaxy systems from leading optical communications manufacturers signal a deliberate ramp in production capability for indium phosphide-based components tied to datacom optical assemblies. The combination of public funding, private capital deployment, and capacity expansion is gradually rewiring the upstream materials landscape, giving qualified suppliers access to more stable substrate pipelines while raising the barrier to entry for manufacturers lacking secure material relationships. However, ongoing export controls and tariff measures on critical materials and semiconductor equipment continue to inject complexity into cross-border sourcing, requiring players to maintain flexible qualification pathways and multi-region supplier strategies to avoid disruption.
Demand-Side Transformation Across Applications
Demand growth is increasingly anchored by application environments that prioritize throughput, reliability, and total cost of ownership. Data center expansion remains a dominant force, driven by cloud infrastructure scaling, AI training and inference clusters, and the need for high-density optical connectivity that can sustain bandwidth growth without proportional increases in power or footprint. Telecommunication networks are undergoing a parallel transformation, with carriers modernizing passive optical networks and metro backbones to support faster broadband delivery, lower latency, and more flexible service architectures. The emergence of chipset solutions designed for next-generation fiber-to-the-room and fiber-to-the-home architectures highlights how receiver sub-assembly design is being aligned with network-level cost reduction goals while preserving performance. Beyond carrier and cloud use cases, enterprise and industrial deployments are contributing incremental but strategically valuable demand, particularly where ruggedized optical links, precise analog reception, and low-noise operation are required for video distribution, voice infrastructure, and specialized sensing applications. Across these segments, buyers are increasingly evaluating receiver components not merely by optical performance specifications but by integration readiness, supply continuity, and lifecycle support, shifting procurement from transactional purchasing to relationship-driven sourcing.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The ROSA market remains moderately concentrated, with a handful of established players commanding meaningful share while a broader field of specialized manufacturers competes on performance, cost, and regional proximity. Leading organizations have built differentiation through a combination of proprietary packaging technologies, photodiode architecture expertise, and application-specific module configurations. Semtech Corporation has reinforced its position by combining receiver sub-assembly optics with broader chipset portfolios that target symmetric fiber architectures and cost-sensitive network deployments, demonstrating a strategy that extends beyond component sales into system-level economics. Eoptolink Technology Inc. has focused on scalable production of transmitter and receiver assemblies alongside indium gallium arsenide photodiodes tailored for digital data applications, emphasizing the ability to move from trial samples to volume manufacturing. Applied Optoelectronics, Inc. continues to supply receiver sub-assemblies across telecom, datacom, and sensing contexts, leveraging broad transceiver integration experience to address multiple end markets with a common technology foundation.
Vitex LLC competes on high-sensitivity photodiodes designed for precise optical-to-electrical conversion, an approach that aligns well with applications where signal integrity and noise performance are paramount. MACOM Technology Solutions has pushed toward high-speed receiver modules with avalanche and PIN photodiodes configured for bandwidth-intensive datacom and telecom requirements, positioning itself in the upper performance tier where speed and package flexibility matter. Agiltron Inc. emphasizes a transceiver platform that balances low cost and high bandwidth for indium gallium arsenide and silicon receiver configurations, appealing to cost-conscious deployments that still require dependable performance. In Asia, Liverage Technology Inc. has maintained a broad speed range covering receiver modules used in 5G, data center, and telecom environments, with both PIN and avalanche variants supporting diverse link budgets. Xiamen San-U Optronics Co., Ltd. has targeted specific form factors and sensitivity profiles for fiber optic applications, an approach that enables focused differentiation in niche receiver segments. Lasermate Group, Inc. integrates photodiodes and amplifiers within its broader fiber optical component portfolio, while EZconn Corporation emphasizes indium gallium arsenide PIN photodiodes for high-speed, low-noise analog use cases in voice, video, and fiber-to-the-home receivers.
The competitive trajectory is shifting from pure specification competition toward integration advantage and supply chain reliability. Market leaders are increasingly rewarded for package-level innovation, co-engineering with transceiver developers, and the ability to support rapid scaling without sacrificing yield. At the same time, recent recognition of highly integrated chip-scale packaging and optical sub-assembly products for AI networks indicates that design integration is becoming a new differentiator, particularly for machine-to-machine and high-performance compute interconnects. The broader pattern points to consolidation among suppliers that can secure stable indium phosphide materials access, advanced packaging capability, and multi-application qualification, while smaller players must either specialize in cost-optimized volume segments or carve out technical niches where sensitivity, bandwidth, or application fit provide defensible margins. New entrants face a steep learning curve because receiver performance depends on tight control over epitaxy, alignment, and packaging, but targeted innovation in chip-scale integration or application-specific receiver configurations can still open viable pathways in high-growth sub-markets.
Optical Circuit Switches Ocs Market
Forward Outlook: Trajectory, Opportunities, and Uncertainty
Over the next three to five years, the receiving optical sub-assembly market is likely to be defined by three interrelated trends. The first is the deepening integration of receiver components into optical engines and co-packaged architectures, driven by the need to reduce power, shrink form factors, and simplify interconnect design for AI and data center networks. Suppliers that can deliver receiver sub-assemblies with chip-scale compatibility, low-loss optical paths, and scalable manufacturing will be best positioned to capture value as transceiver architectures become more tightly coupled. The second trend is the gradual rebalancing of indium phosphide substrate and epitaxy capacity, supported by both public funding and private equipment investment. As domestic and regional production expands, supply chain volatility should moderate for qualified buyers, though pricing and allocation dynamics will remain sensitive to equipment lead times, yield ramp rates, and geopolitical trade conditions. The third trend is the continued bifurcation between performance-premium and cost-optimized receiver segments. High-speed, high-sensitivity, and integrated amplifier solutions will sustain margins in datacom and advanced telecom applications, while volume access, enterprise, and industrial deployments will reward suppliers capable of delivering dependable performance at competitive cost.
PW Consulting
These trends create tangible commercial opportunities. Manufacturers that align product roadmaps with AI-era interconnect requirements, invest in packaging and alignment processes that improve yield and repeatability, and build multi-source material strategies will have stronger negotiating leverage with system integrators and cloud operators. Investors should monitor companies with demonstrable access to indium phosphide substrate pipelines, expanding epitaxy or packaging capacity, and product lines tied to chip-scale or highly integrated optical engines, as these capabilities are increasingly correlated with long-term relevance. Procurement teams, meanwhile, will benefit from developing supplier relationships that extend beyond unit pricing to include qualification support, ramp predictability, and resilience against material or equipment constraints. The principal uncertainties are execution risk in capacity expansions, the pace at which export controls and trade policy might alter materials availability, and the possibility that rapid transceiver architecture shifts could change receiver integration requirements faster than suppliers can adapt. Markets that grow at double-digit rates can still produce uneven outcomes if technology transitions outpace process maturity or if supply chain re-engineering introduces unexpected delays.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align receiver roadmaps with where performance, packaging, and materials access converge most favorably. Investments in chip-scale compatibility, high-sensitivity photodiode variants, and process controls that improve yield and repeatability will be more valuable than incremental specification upgrades alone. Companies should also stress-test supplier relationships for indium phosphide substrates and epitaxy capacity, and qualify alternative sourcing where feasible to reduce exposure to concentrated material dependencies. Building application-specific receiver configurations for AI network interconnects, high-speed data center links, and modernized fiber access networks can open differentiated positioning without requiring platform-wide redesigns.
For investors, the most informative signals will come from capacity deployment, materials access, and integration strategy rather than headline growth alone. Companies with confirmed equipment orders for epitaxy systems, expanding domestic or regional indium phosphide production, and product portfolios tied to highly integrated optical engines warrant closer scrutiny, particularly when paired with demonstrated volume ramp capability. Equally important is assessing whether a player’s differentiation rests on proprietary process knowledge or on interchangeable assembly economics, since the latter tends to erode faster in competitive segments. Portfolio exposure should favor organizations that can translate materials and packaging advantages into recurring transceiver-related demand.
For procurement and supply chain leaders, the strategic shift is from price-only sourcing to resilience-weighted evaluation. Receiver components increasingly influence system-level power, latency, and integration complexity, which means qualification criteria should weigh performance stability, ramp predictability, packaging maturity, and continuity of critical materials. Developing multi-region supplier options and securing early engagement with vendors that are expanding InP-related capacity can reduce vulnerability to allocation shocks or trade-related disruption. For organizations that require deeper segmentation data, scenario modeling, or customized sourcing and investment guidance, a dedicated report provides the granular breakdowns and bespoke analysis needed to translate these market-level signals into operational decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Resceiving Optical Sub-Assembley Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com