

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
The Real Drivers Behind BOPA Film’s 5.8% Market Growth Through 2032

Strategic Imperatives in the Biaxially Oriented Polyamide (Nylon) Film Market: Navigating Growth, Volatility, and Sustainability
The biaxially oriented polyamide (BOPA) film market stands at a critical inflection point where traditional growth trajectories intersect with transformative pressure from raw material volatility, sustainability mandates, and shifting end-user expectations. Over the 2020–2025 historical period, the global BOPA film revenue expanded from approximately $1,170 million to $1,430 million, reflecting an average annual growth rate of roughly 4.2% in absolute terms. As the market enters the 2026–2032 forecast window, industry momentum is expected to accelerate, with a projected compound annual growth rate of 5.8%, pushing total revenue toward $2,088 million by the end of the decade. This expansion is not merely a continuation of historical demand patterns. It reflects a structural reconfiguration of how packaging, pharmaceutical, and industrial supply chains value barrier performance, mechanical durability, transparency, and increasingly, the carbon footprint embedded in film production.
For executives and strategic planners, this trajectory presents both a sizable addressable market and a complex operating environment. Growth is broad-based but uneven, shaped by regional manufacturing capabilities, regulatory divergence, and the concentration of value creation among a cohort of globally active producers. The following analysis examines the market’s current architecture, the forces reshaping its dynamics, the strategic positioning of leading participants, and the actionable implications for manufacturers, investors, and procurement teams navigating the next five years.
Market Architecture and Core Challenges
The BOPA film market operates within a moderately concentrated structure where scale, technology access, and application specialization determine competitive advantage. Revenue distribution spans multiple geographies and value chains, with Asia Pacific accounting for the largest share of global revenue, followed by Europe and North America. Latin America and the Middle East & Africa represent smaller but strategically relevant demand pools, often characterized by cost-sensitive industrial applications and emerging packaging consumption. Rather than competing purely on price, participants are increasingly differentiating through sequential versus simultaneous orientation technologies, gauge control, clarity, puncture resistance, and compatibility with laminates and heat-seal systems. The market’s oligopolistic tilt means that margin preservation depends on technical service, supply reliability, and the ability to anticipate downstream requirements in food safety, pharmaceutical compliance, and industrial durability.
Biaxially Oriented Polyamide (BOPA) Films Market
Despite the favorable growth backdrop, three structural challenges are reshaping the operating logic of the BOPA film sector:
- Raw material price sensitivity and input volatility. BOPA production depends on polyamide resins whose pricing is closely tied to caprolactam and adiponitrile dynamics, energy costs, and regional supply balances. Recent price adjustments in the nylon value chain have increased pressure on converters and film manufacturers, squeezing margins unless absorbed through product premiumization, contract structuring, or efficiency gains.
- Regulatory fragmentation and trade barriers. Divergent packaging regulations, anti-dumping measures, and evolving sustainability certification expectations are fragmenting what was once a relatively standardized export market. Producers now face a patchwork of obligations that affect cost, eligibility, and time-to-market for new grades.
- Sustainability expectations as a procurement imperative. End users are increasingly embedding environmental criteria into supplier selection, not simply as compliance but as part of brand positioning and risk management. Films with lower carbon intensity, recyclability alignment, and certified sustainable feedstocks are moving from niche differentiators to baseline requirements in certain segments.
These challenges are not isolated. They interact with one another, creating a landscape where cost, compliance, and customer expectations must be managed simultaneously. The firms that navigate this triad most effectively will be those that treat sustainability and regulatory adaptation as design parameters rather than afterthoughts, and that use technical differentiation to justify price realizations in a rising-cost environment.
Key Drivers Reshaping the BOPA Film Market
Technology Innovation and Performance Differentiation
Performance advancement remains the central engine of value creation in BOPA films. Sequential and simultaneous orientation processes continue to evolve, enabling tighter control over dimensional stability, barrier properties, and optical clarity. For pharmaceutical packaging and specialty high-barrier applications, this translates into films that maintain integrity under strict processing conditions and extended shelf-life requirements. For food packaging, improvements in tensile strength, sealability, and moisture resistance support thinner gauges and more flexible laminates without compromising protection. The strategic significance of these advances lies in their ability to shift competition away from commodity substitution and toward application-specific value. When a film can enable lighter structures, reduce waste in downstream converting, or improve reliability in sensitive applications, it becomes a strategic input rather than a replaceable component.
Recent dynamics underscore the importance of feedstock reliability in supporting these technical goals. In North America, price adjustments for caprolactam and polyamide grades have been announced for 2026, reflecting evolving conditions across the nylon value chain. At the same time, spot pricing for caprolactam has shown month-over-month increases in both North American and European markets. For BOPA producers, this environment rewards integrated planning, long-term supply agreements, and grade architectures that maintain performance even as input economics fluctuate. It also elevates the strategic importance of alternative feedstocks and certified sustainable options, particularly where customers view supply continuity and environmental credentials as linked priorities.
Policy, Trade, and Certification Shifts
The regulatory environment is becoming a more active determinant of market access and competitive positioning. Trade measures have already begun to reshape regional dynamics. For example, Indonesia has imposed anti-dumping duties on nylon film imports from China, Thailand, and Taiwan, with a multi-year validity period. Such measures influence not only the cost structure of imported films but also the broader pattern of regional sourcing, inventory positioning, and local manufacturing incentives. In parallel, certification frameworks are gaining commercial relevance. ISCC PLUS certification and product carbon footprint disclosures are increasingly referenced in customer evaluations, especially where end brands are under pressure to communicate environmental progress credibly.
These policy and certification developments have a dual effect. They raise the bar for market entry and expansion in affected geographies, but they also reward firms that can demonstrate verifiable sustainability claims and adapt their supply footprint to regional trade realities. For BOPA manufacturers, the implication is that geographic strategy can no longer be separated from compliance strategy. Production capacity, feedstock sourcing, and documentation capability are now part of the same commercial equation.
Demand-Side Evolution Across Packaging Ecosystems
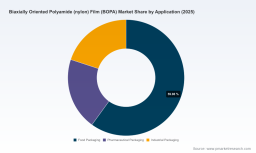
Demand for BOPA films continues to be anchored by food packaging, pharmaceuticals, and industrial applications, each with distinct performance and regulatory profiles. Food packaging remains the largest application driver, supported by the need for barrier protection, clarity, and compatibility with flexible packaging formats. Pharmaceutical packaging demands high consistency, integrity, and traceability, making film quality and process stability especially important. Industrial packaging adds another layer of requirements around puncture resistance, durability, and cost efficiency in heavier-duty uses.
What is changing is the way these demand segments evaluate film suppliers. Procurement decisions are increasingly multidimensional, weighing technical fit alongside availability, sustainability attributes, and total cost of ownership rather than unit price alone. This shift is especially visible in markets where brand owners and converters are seeking to reduce material intensity, improve recyclability outcomes, or align with corporate sustainability commitments. In that context, BOPA films that support ultra-thin constructions, recyclable laminate designs, or carbon footprint reduction become more commercially attractive, even if they carry a premium relative to baseline alternatives.
Supply Chain and Cost Structure Dynamics
Cost structures across the BOPA value chain are being redefined by several simultaneous forces. Energy prices, resin availability, logistics, and regional manufacturing footprints all influence competitive positioning. At the same time, some producers are pursuing lower-cost manufacturing models for food and industrial packaging, while others are emphasizing high-performance grades for demanding applications. This bifurcation creates a market where cost leadership and technology leadership are not always pursued by the same players, and where the strategic challenge is to avoid being trapped in the middle of a segment that is simultaneously price-sensitive and performance-driven.
Certification and sustainability investments are adding a new layer to cost structure considerations. Obtaining environmental certifications for production facilities and rolling out lower-carbon grades requires upfront investment and disciplined execution. Yet these capabilities can also become durable advantages when customers begin to prioritize verifiable claims and supply assurance over spot-market pricing alone. The result is a market in which cost discipline and positioning clarity are both necessary, and in which the most resilient firms are those that can select the segments where their cost model and capabilities are best aligned.
Competitive Landscape and Strategic Positioning
The BOPA film competitive field includes globally established specialty producers, regionally focused manufacturers, and firms that balance cost efficiency with targeted performance differentiation. Several Japanese and Korean companies occupy a prominent role in high-quality sequential BOPA films, particularly where pharmaceutical packaging, high-barrier applications, and demanding food packaging formats are involved. Their positioning tends to emphasize sequential and simultaneous orientation expertise, consistent gauge control, and specialized barrier and mechanical attributes. This enables them to compete on reliability and application support, not only on price.
European participants contribute another dimension to the landscape. Certain manufacturers have focused on sustainable grades, recyclable laminate compatibility, and ultra-thin options that align with packaging 경량화 and environmental goals. Others have expanded sustainability credentials through ISCC PLUS certification and lower-carbon product claims, linking production credentials directly to customer-facing value propositions. In this group, the strategic emphasis is often on demonstrating measurable environmental improvement while maintaining the performance required by converters and end users.
In Asia, a broader set of producers supports regional and export demand across food, industrial, and specialty packaging. Some companies emphasize cost-effective manufacturing for high-volume applications, while others concentrate on PA6-based solutions or enhanced barrier and mechanical performance. This diversity creates a competitive environment in which regional price dynamics, local content expectations, and application specialization all matter. It also means that trade measures and regional certification requirements can quickly alter the relative attractiveness of different sourcing options.
Beyond firm-level positioning, the market is exhibiting several structural trends:
- Consolidation pressure in specialty segments. Where performance, compliance, and technical service are critical, larger or more integrated players can gain share by offering consistent supply, multi-grade portfolios, and stronger application support.
- Segmentation between cost-driven and value-driven production. Not all BOPA films compete in the same decision framework. High-barrier and pharmaceutical-oriented films reward precision and certification; certain industrial and food packaging applications remain more sensitive to cost and local availability.
- Growing relevance of sustainability as a competitive attribute. Lower-carbon grades, certified feedstocks, and recyclable laminate alignment are becoming part of the value proposition in select markets, especially where brand owners and converters are building sustainability into purchasing criteria.
- Regional reconfiguration of supply patterns. Trade measures and certification expectations are encouraging buyers to diversify supply sources or localize production where feasible, increasing the strategic importance of regional manufacturing and compliance readiness.
Taken together, these trends suggest a market that is moving toward greater segmentation and more explicit differentiation. The firms most likely to sustain favorable positioning are those that can define their competitive lane clearly, whether that lane is high-performance specialty films, cost-efficient regional supply, or sustainability-linked product architecture, and then execute with discipline in that lane.
Forward-Looking Trends and Commercial Implications
Trend 1: Sustainability Moves from Differentiator to Procurement Filter
Over the next three to five years, environmental criteria are likely to become more deeply embedded in BOPA film purchasing decisions, particularly in segments connected to consumer-facing brands and regulated packaging ecosystems. This does not mean every buyer will require the same standard, but it does mean that verifiable sustainability attributes, including certified feedstocks and product carbon footprint reductions, will increasingly influence supplier shortlists.
The commercial opportunity lies in linking sustainability claims to real performance and supply reliability. Films that combine lower carbon intensity with acceptable barrier, clarity, and mechanical properties can capture premium positioning in applications where environmental alignment matters. The risk is greenwashing exposure if claims are not substantiated or if sustainability improvements undermine the functional requirements that customers depend on. Firms will need to manage this balance carefully, with transparent documentation and product design that integrates sustainability without sacrificing performance.
Trend 2: Input Volatility Will Reward Integrated Strategy and Grade Architecture
Raw material and energy volatility are expected to remain features of the operating environment, not temporary disruptions. This will continue to pressure margins and elevate the importance of procurement strategy, hedging approaches, product mix management, and operational efficiency. In this context, the most resilient BOPA businesses are likely to be those that can adjust grade architecture to emphasize higher-value applications when cost pressure intensifies, while maintaining reliable supply for cost-sensitive segments.
The opportunity here is partly defensive and partly offensive. Defensively, stronger supply relationships and flexible sourcing can reduce exposure to spot-market shocks. Offensively, firms that can sustain consistent quality and performance despite input volatility can strengthen customer trust and justify more stable pricing relationships. The uncertainty is the pace and direction of feedstock and energy price movements, which can differ by region and shift quickly in response to broader market conditions.
Trend 3: Regionalization and Trade Policy Will Reshape Sourcing Maps
Trade measures, local content expectations, and certification requirements are likely to continue encouraging regionalization in BOPA supply chains. Buyers may increasingly prefer regional production or diversified sourcing to reduce exposure to duties, logistics risk, and compliance complexity. This favors producers with flexible manufacturing footprints, strong regional compliance capabilities, and the ability to serve local demand with consistent quality.
The strategic opportunity is to position capacity and product portfolios where regulatory and trade dynamics are most favorable, while maintaining the ability to serve export demand where it remains viable. The risk is that protectionist measures and regulatory divergence could fragment what remains a global technology market, increasing complexity and reducing the efficiency of scale-based strategies in some geographies. Participants will need to monitor policy developments closely and align sourcing and capacity decisions with evolving market access conditions.
Thermoplastic Polyamide Market
Strategic Actions for Decision-Makers
For manufacturing and strategy leaders, the priority is to align product positioning with the segments where performance and sustainability can be monetized most effectively. This means resisting the temptation to compete uniformly across all applications and instead selecting where sequential or simultaneous orientation technologies, barrier performance, and certified sustainable grades create genuine value. It also means building procurement and supply resilience into the operating model, especially given raw material price movements and regional trade dynamics. Manufacturers that can offer reliable supply, clear documentation, and application-specific technical support will be better placed to preserve margins and customer relationships in a volatile environment.
For investors and corporate development teams, the key question is where value is likely to concentrate as the market matures. The most attractive exposures are probably in firms with clear competitive differentiation, credible sustainability capabilities, and positioning that matches regional demand growth rather than broad, undifferentiated capacity expansion. Equally important is the risk side: exposure to input cost shocks, trade barriers, and commoditization in price-sensitive segments can erode returns if not managed through portfolio design and segment selection. Due diligence should therefore focus not only on capacity and revenue trend, but also on certification readiness, feedstock strategy, regional market access, and the defensibility of technical differentiation.
PW Consulting
For procurement and sourcing professionals, the strategic shift is to evaluate BOPA films through a broader lens that includes sustainability documentation, supply continuity, and total cost of ownership rather than unit price alone. When films are critical to product integrity or brand positioning, the cost of inconsistency, supply disruption, or misalignment with sustainability expectations can outweigh modest price differences. Diversifying qualified suppliers by capability and region, understanding certification status, and clarifying performance requirements with converters and internal stakeholders can reduce exposure while creating room to capture value from specialized films where they are justified.
For all of these audiences, the practical takeaway is that BOPA film strategy is no longer solely about film properties or price. It is about aligning technology, compliance, sustainability, and regional supply dynamics with the specific applications that matter most to each business. The market’s growth trajectory provides room for value creation, but capturing that value will increasingly depend on precision in positioning and discipline in execution.
The dynamics described here are broad in scope, but their real impact is highly segment-specific and region-specific. Detailed segmentation data, regional revenue breakdowns, competitor benchmarking, and customized scenario analysis can materially sharpen strategic decisions, particularly for organizations evaluating capacity investments, supplier qualification, product roadmap planning, or market-entry timing. For teams that require a more granular view of segment growth paths, competitive positioning, and application-level demand shifts, PW Consulting’s full market research report provides deeper segmentation detail and tailored analytical frameworks to support concrete business decisions.
For detailed analysis of this topic, please visit the official page: Biaxially Oriented Polyamide (nylon) Film (BOPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com