

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Autonomous Drilling Robots: How 16.25% CAGR Reshapes Mining and Energy Markets

Navigating the Autonomous Drilling Robots Market: Strategic Trends and Commercial Opportunities Through 2032
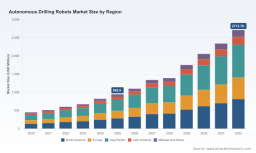
Market Momentum and Defining Challenges The worldwide autonomous drilling robots market has entered a phase of accelerated expansion, with revenue scaling from approximately 450.4 million USD in 2020 to an estimated 945.5 million USD by 2025. Projections indicate the market will surpass 1.1 billion USD in 2026 and continue its upward trajectory, reaching roughly 2.7 billion USD by 2032. At a compound annual growth rate of 16.25 percent across the forecast period, the sector reflects a structural shift rather than a cyclical uptick. This growth is underpinned by the maturation of sensing technologies, tighter safety mandates, and the escalating complexity of extraction and construction operations in remote or hazardous environments. Despite the compelling demand signals, the industry is navigating several critical junctures. First, the transition from semi-autonomous to fully autonomous systems demands a convergence of hardware reliability, real-time geotechnical feedback, and fleet-level orchestration that remains unevenly distributed across regions and applications. Operators are weighing the operational benefits of removing personnel from high-risk drilling zones against the capital intensity of sensor fusion suites, positioning systems, and adaptive control algorithms. Second, standardization and interoperability are emerging as practical bottlenecks. As drilling fleets grow more automated, the ability to integrate disparate rig platforms, data pipelines, and remote command centers becomes a decisive factor in realizing the promised productivity gains. Fragmented data architectures can slow deployment and dilute the return on automation investments. Third, the talent equation is reshaping procurement and deployment strategies. Persistent shortages of skilled drill operators in isolated mining and energy locations are pushing organizations toward continuous, automated operations, yet integrating these systems requires new competencies in remote supervision, maintenance, and data interpretation. Companies that treat autonomy as a standalone equipment purchase often underestimate the change-management and training requirements that determine long-term adoption success.
Key Drivers Reshaping the Autonomous Drilling Landscape
Technological innovation remains the central catalyst, but the nature of the advancement is evolving from isolated automation features to integrated, fleet-capable intelligence. Modern autonomous drill rigs increasingly rely on advanced sensor fusion, high-resolution positioning, and AI-driven algorithms that provide real-time geotechnical feedback and obstacle detection. These components enable machines to adjust drilling parameters on the fly, maintain consistent hole quality, and operate with minimal human intervention. Recent deployments illustrate how this technology is moving from pilot environments into production settings. A collaborative effort between a leading tool brand and an autonomous mobile robot specialist introduced a downward-drilling, fleet-capable concrete drilling robot designed for data center construction. Pilot programs demonstrated high accuracy across tens of thousands of holes, signaling that autonomous precision is now viable for large-scale floor preparation where consistency and speed directly affect downstream construction schedules. In parallel, mining equipment manufacturers have advanced autonomous surface drilling systems that combine fleet management with real-time optimization, while others have introduced electric autonomous variants and collaborative automation projects targeting fully autonomous face drilling and boom recovery functions. These developments show a clear trajectory: autonomy is being embedded into the core operating logic of the rig, not bolted on as an add-on module. Policy and regulatory momentum is reinforcing this technological shift. Safety mandates and industry standards are increasingly emphasizing the reduction of human exposure to hazardous environments, creating a regulatory tailwind for zero-entry or reduced-entry drilling operations. In mining, autonomous drilling systems align with broader safety objectives by keeping personnel away from active drilling faces and heavy equipment movement zones. In energy and infrastructure, automation is being evaluated not only for efficiency but also for consistency, documentation, and risk mitigation across complex well construction and foundation work. Public and private funding initiatives are also accelerating the maturation of adaptive automation and advanced recovery functions, particularly in academic and industry partnerships that focus on refining autonomous behaviors in variable ground conditions. This combination of safety-driven policy and targeted research support is helping lower the practical barriers to broader deployment. Demand-side behavior is changing as well, driven by project complexity and workforce constraints. The rapid global expansion of data center construction is creating a surge in demand for precise, repeatable floor preparation work, where autonomous concrete drilling robots can accelerate progress while improving accuracy and safety. At the same time, labor shortages and the difficulty of attracting and retaining skilled operators in remote mining locations are encouraging organizations to pursue continuous operations enabled by autonomous drilling technologies. This is not simply a cost equation; it is an operational resilience strategy. Companies are increasingly evaluating autonomy as a way to stabilize production, reduce variability, and maintain output when skilled labor is scarce or difficult to deploy. As a result, demand is spreading beyond traditional reserves into aggregates, quarries, and infrastructure projects where consistent performance and reduced operational risk justify the investment. Supply chain and cost structure dynamics are influencing how quickly organizations can adopt autonomous systems. The reliance on sophisticated sensors, high-resolution positioning hardware, and AI-based control software means that component availability, integration expertise, and software lifecycle management are becoming strategic considerations. Cost structures are also shifting as electric and autonomous variants gain traction, changing the calculus around fuel consumption, maintenance intervals, and emissions compliance. For many operators, the business case increasingly hinges on total cost of ownership over the life of the equipment rather than upfront purchase price. This favors suppliers that can offer integrated solutions, predictable software updates, and service models aligned with continuous, remote-operated workflows. As supply chains for advanced electronics and precision components stabilize and scale, the economics of autonomous drilling are expected to improve further, broadening access beyond early-adopter segments.
Competitive Landscape and Leadership Strategies
The competitive environment is defined by a mix of established equipment manufacturers, energy services companies, and specialized robotics developers, with a meaningful concentration of market share among a limited group of leaders. Incumbents in mining equipment have built strong positions by offering autonomous-ready drill rigs and surface drilling automation platforms that integrate fleet management and real-time optimization. Their advantage lies in decades of domain expertise, extensive field service networks, and the ability to embed autonomy into familiar rig architectures. Recent activity underscores this strategy: one manufacturer delivered an autonomous-ready rotary drill rig to a copper operation and partnered to implement surface drilling automation, while another secured a large order for autonomous and electric blasthole drill rigs in Africa, to be operated fully autonomously with zero exhaust emissions. These moves highlight a dual focus on performance and sustainability, as well as a willingness to commit to large-scale deployments in demanding environments. Energy services companies are pursuing a different but complementary angle, emphasizing drill automation software, directional drilling consistency, and integrated workflows across rig types. Their offerings target the repeatability and precision required in well construction, often pairing automation with geosteering and operational analytics. By focusing on software-defined drilling and service-integrated automation, these players are positioning autonomy as a way to reduce variability in complex wells and improve consistency across campaigns. This software-centric approach expands the definition of autonomous drilling beyond hardware, creating opportunities for companies that can orchestrate data, drilling parameters, and field execution in a unified workflow. A notable dynamic in the landscape is the emergence of specialized robotics and automation collaborators that bring new capabilities into established application areas. A robotics company focused on autonomous mobile platforms and fleet orchestration has partnered to power a downward-drilling concrete robot designed for data center construction, achieving high accuracy in pilot programs and targeting commercial availability in the near term. Another specialist has developed autonomous reverse circulation drill rigs for mining and exploration, with a clear emphasis on removing operators from hazardous manual operations. These entrants illustrate how the market is being shaped not only by traditional equipment rivalry but also by cross-industry partnerships that combine drilling expertise with advanced robotics, fleet management, and application-specific engineering. The result is a more pluralistic competitive field in which differentiation comes from application fit, integration depth, and the ability to deliver measurable accuracy and productivity gains. Market structure appears to be evolving along several axes simultaneously. Consolidation remains a plausible path as larger players seek to broaden their automation portfolios through acquisitions or strategic partnerships, particularly in software, sensing, and fleet orchestration. At the same time, segmentation is intensifying, with companies increasingly specializing by application, region, or level of autonomy. Some competitors are focusing on fully autonomous systems for defined use cases, while others continue to advance semi-autonomous solutions that offer incremental automation for organizations not yet ready for full removal of human operators. New entrants are gaining traction where they can solve a specific operational pain point with a clearly demonstrated accuracy or safety benefit, especially in construction and infrastructure segments that have historically seen less drilling automation. The most successful players are those that can articulate a clear path from installation to sustained operational value, supported by service, training, and data-driven optimization.
Future Trends and Commercial Implications
Over the next three to five years, one of the most consequential trends will be the shift from standalone autonomous rigs to coordinated, fleet-level automation. As more operations deploy multiple automated drill units, the value proposition will increasingly depend on orchestration, task allocation, and centralized monitoring rather than the capabilities of any single machine. Organizations that invest early in data standards, interoperable control architectures, and remote supervision capabilities are likely to extract more value from their automation investments and adapt more quickly as fleets expand. A second trend is the broadening of autonomy beyond traditional mining and energy applications into construction and infrastructure, particularly where precision, repeatability, and labor constraints intersect. Data center construction and large-scale floor preparation are already illustrating how autonomous concrete drilling can improve accuracy and throughput in high-volume projects. This application expansion opens commercial opportunities for suppliers that can tailor autonomy to different substrate conditions, site layouts, and project schedules, while also creating new demand for integration with broader construction workflows. A third trend is the continued coupling of autonomy with electrification and emissions reduction goals, especially in regions and sectors where sustainability requirements and operating costs are moving in tandem. Electric autonomous drill rigs and zero-emission operation concepts are gaining visibility in mining and quarry settings, and this convergence is likely to influence procurement criteria, site planning, and vendor selection. Companies that can offer autonomous performance alongside favorable emissions profiles may find stronger positioning in tenders and long-term partnerships. These trends carry commercial opportunities, but also uncertainty. Adoption velocity will depend on how quickly integration challenges are resolved, how consistently accuracy and reliability hold up across diverse site conditions, and whether organizations can build the internal capabilities needed to manage automated fleets. Economic fluctuations, changes in project pipelines, and evolving safety or emissions regulations could also alter deployment timelines. The most resilient strategies will treat autonomy as a long-term operating model transformation, not a one-time equipment upgrade.
Strategic Recommendations for Decision-Makers
For manufacturers and technology providers, the priority is to deepen application-specific value rather than compete solely on automation features. Differentiation will increasingly come from proven accuracy, fleet orchestration, service and software support, and the ability to demonstrate measurable improvements in safety, consistency, and throughput. Investing in interoperability, remote supervision tools, and clear upgrade paths can help products remain relevant as operations scale from single-rig deployments to coordinated fleets. Partnerships that combine drilling domain expertise with robotics, AI, and fleet management capabilities are likely to accelerate time to value and expand addressable use cases. For investors, the opportunity set is expanding but unevenly distributed. Segments with clear labor constraints, strong safety mandates, and high-volume precision requirements are showing particularly strong adoption logic, while broader market growth will depend on how quickly integration and standardization issues are resolved. Evaluating companies on their ability to deliver total cost of ownership benefits, sustain software and service ecosystems, and expand into adjacent applications can provide a more reliable basis for assessing long-term positioning than headline automation claims alone. For procurement and operations leaders, the practical starting point is to align autonomy investments with operational priorities and site realities. Assessing where autonomy can reduce risk exposure, stabilize output, and improve repeatability should come before technology selection. Pilots should be structured to measure accuracy, downtime, maintenance demands, and supervisory workload, with attention to data integration and training requirements. Building internal capability for remote operation, analytics, and preventive maintenance will be as important as selecting the right equipment. Detailed segmentation data, company-level benchmarks, and application-specific deployment considerations can help translate these strategic themes into precise planning assumptions. For decision-makers seeking a deeper view of market sizing, regional dynamics, and vendor positioning, the full PW Consulting research report provides expanded detail and customizable analysis to support investment, procurement, and product strategy decisions.
PW Consulting
Directional Drilling Market
Worldwide Underwater Dredging Robot Market
For detailed analysis of this topic, please visit the official page: Worldwide Autonomous Drilling Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com