

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Blood Collection Tubes Market: Why the 7.2% CAGR Trajectory Changes Everything
By pmarketresearch, 2026-09-21
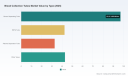
Beyond the Vacuum: Strategic Trajectories and Commercial Opportunities in the Blood Collection Tubes Market
The blood collection tube market has reached an inflection point where steady growth intersects with intensified regulatory scrutiny and evolving clinical demands. Revenue across the sector climbed from approximately 163.15 million in 2020 to an estimated 215.0 million in 2025, with the trajectory projected to reach 344.8 million by 2032. The forward compound annual growth rate stands at 7.2 percent, signaling sustained expansion rather than a temporary surge. This growth is not merely a function of volume; it reflects a structural shift in how samples are collected, stabilized, and managed within diagnostic and therapeutic workflows.
Despite the upward curve, the market faces a set of challenges that will define competitive positioning in the coming years. First, the margin between clinical performance and compliance risk is narrowing. Devices that appear functionally identical on paper can diverge sharply in quality control maturity, and recent enforcement actions have made that divergence costly. Second, the preanalytical phase remains the largest source of variability in laboratory results, yet standardization across collection environments, operator training, and tube chemistry continues to lag. Third, regional demand is accelerating in emerging markets while mature markets are squeezing efficiency, creating a dual mandate: scale without sacrificing quality, and differentiation without over-engineering.
These dynamics reshape how leaders should think about opportunity. The market is no longer a commodity contest around evacuation mechanics and additive chemistry alone; it is a reliability contest around consistency, traceability, and regulatory readiness. Growth will favor organizations that can convert operational discipline into commercial advantage, particularly as procurement teams, regulators, and clinical stakeholders align around sample integrity as a non-negotiable baseline.
The Core Growth Engines Redefining Value Creation
Three forces are driving the market’s trajectory and redefining where value is created. The first is technological innovation in tube chemistry, materials, and workflow integration. Advances in separator gel formulations, anticoagulant precision, and material biocompatibility are enabling tighter control over sample stability, shorter turnaround windows, and broader utility across diagnostic and therapeutic applications. At the same time, manufacturers are pushing toward designs that simplify handling and reduce user variability. The impact extends beyond product features: better chemistry and materials reduce preanalytical error, which in turn improves laboratory throughput and trust in downstream results.
The second force is a tightening regulatory and quality environment. Blood collection tubes are classified under FDA product code JKA and require 510(k) clearance for marketing, while evacuated, sterile, single-use devices must comply with biocompatibility and purity standards for metal additives. The regulatory perimeter has become more visible in day-to-day operations. Quality system expectations, corrective action rigor, and supplier management requirements now directly influence market access and brand credibility. This matters commercially because compliance is increasingly a differentiator rather than a baseline checkbox.
PW Consulting
The third force is demand-side evolution across the care continuum. Diagnostic testing continues to be the dominant pull, but the broader application base is diversifying as point-of-care needs, monitoring workflows, and specialized therapeutic programs increase the volume and variety of sample collection. Clinicians and laboratorians are prioritizing tubes that support consistent results across multiple settings, while procurement groups are weighing total cost of ownership rather than unit price alone. That shift favors suppliers that can demonstrate reliability, reduce error-related rework, and integrate smoothly into existing collection protocols.
A fourth force, often underappreciated, is the changing cost and supply chain structure. Materials, manufacturing consistency, and supplier oversight all affect margin and resilience. Because tubes are single-use devices with stringent purity and performance expectations, disruptions in raw material sourcing or component quality can cascade quickly into clinical risk and commercial exposure. Firms that invest in transparent supplier governance, robust design controls, and predictable production quality are better positioned to protect both margins and reputation.
Recent market events illustrate how these forces interact in practice. Regulatory enforcement actions in 2025 highlighted how quickly quality and documentation gaps can alter market access. A warning letter related to capillary blood collection tubes underscored the consequences of quality system and reporting deficiencies, resulting in an import alert that restricted U.S. entry. At the same time, Class 2 recalls involving labeling and gel separator omissions, as well as a recall tied to supplier management weaknesses, demonstrated that even established product lines can face disruption when change control, supplier oversight, or corrective action processes fall short. These episodes reinforce a central insight: product capability must be matched by quality system maturity if growth is to remain durable.
Vacuum Blood Collection Tube Market
The practical implication is clear. Innovation that improves sample handling or broadens application fit will gain traction only when paired with disciplined execution. For commercial leaders, that means measuring success not just by launch velocity or feature checklists, but by the reliability of the entire collection-to-result chain and the strength of the quality infrastructure supporting it.
Competitive Positioning and the Evolving Landscape
The market remains moderately concentrated, with the top three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. That level of concentration indicates room for both consolidation and targeted disruption, depending on how companies leverage scale, portfolio breadth, and compliance capability. Several established players illustrate the strategic paths now shaping the field.
One large global player has built its position around a widely recognized evacuated tube system and a broad portfolio covering hematology, coagulation, chemistry, and therapeutic drug monitoring. Its emphasis on sample quality and analytical accuracy reflects a long-standing bet that consistency and clinical trust can sustain share even in a competitive category. The strategic message is straightforward: broad application coverage and a consistent quality narrative can create stickiness across laboratory and hospital channels.
A second major manufacturer has focused heavily on preanalytical safety and blood collection systems, including serum separator, gel separator, and safety-oriented models. This company’s trajectory suggests that differentiation through workflow safety, ease of use, and preanalytical reliability can be as valuable as chemistry alone. In practice, that positioning aligns well with institutions seeking to reduce handling risk and standardize collection across varied clinical environments.
A third contender has expanded through high-quality materials and chemistries, with a strong presence across Asia and global distribution for venous and capillary collection. Its strategy shows how geographic reach and material performance can combine to serve both mature and growth markets, especially where distribution logistics and product reliability are critical to winning procurement confidence.
A fourth established producer has emphasized flexibility and variety in its tube systems, aiming to suit different clinical environments and preanalytical applications. That flexibility-oriented approach reflects a pragmatic reality: no single tube design is optimal for every setting, and institutions often value suppliers that can adapt to local workflows without sacrificing standardization.
Taken together, these profiles point to a landscape that is neither fully consolidated nor fragmented beyond remedy. The more relevant trend is strategic differentiation around reliability, safety, workflow fit, and regulatory readiness. Leadership is increasingly defined by the ability to integrate product performance with quality systems, supplier governance, and clear documentation. This matters because recent recall and warning letter events have raised the cost of quality lapses, making execution a competitive weapon rather than a back-office function.
The market is also likely to see continued evolution in how value is captured. Some organizations will pursue integration through portfolio expansion and channel strength, using breadth to reduce customer switching and strengthen institutional relationships. Others will pursue niche positioning around specific applications, safety features, or regional distribution advantages. New entrants will face a steeper path if they cannot match the combination of product performance, regulatory compliance, and operational consistency, but they may still find openings where incumbents underinvest in particular applications, emerging-market distribution, or preanalytical innovation.
For decision-makers, the most useful conclusion is that competitive advantage in this market is becoming multidimensional. Price still matters, but it is no longer sufficient. Buyers and regulators are increasingly attentive to sample integrity, labeling control, supplier oversight, and documented quality processes. Companies that align their product roadmap with these expectations will be better positioned to defend share and expand into higher-value segments.
Where the Market Is Heading: Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape the market’s direction and the opportunities within it.
The first trend is the elevation of preanalytical quality from a technical concern to a commercial priority. As laboratories and health systems face continuing pressure to reduce errors, improve turnaround, and standardize results, tubes that support consistent fill, stable separation, and predictable anticoagulant performance will gain preference. This trend opens opportunities for suppliers that can document performance consistency, provide clear handling guidance, and design for reduced operator variability. It also raises the risk for products with ambiguous change control, weak supplier controls, or inconsistent labeling, since those weaknesses are increasingly exposed through regulatory and customer scrutiny.
The second trend is regulatory and quality maturity becoming a market access gate. With established classification and clearance expectations, as well as heightened attention to quality systems, medical device reporting, and supplier management, compliance will increasingly determine which products can enter or remain in key channels. The commercial opportunity lies in building trust through transparent documentation, repeatable production quality, and rapid corrective action capability. The risk is that companies treating compliance as a discretionary layer will face disruption not only from enforcement but also from procurement teams that now screen for quality readiness before volume commitments.
The third trend is demand diversification across diagnostic, therapeutic, and broader application needs, with regional growth uneven but meaningful. Mature markets will likely reward efficiency, integration, and reliability, while faster-growing regions will reward distribution strength, adaptability, and cost-conscious quality. This split creates an opportunity for companies to tailor portfolios by region and application rather than relying on a single global template. It also introduces uncertainty: demand patterns can shift with testing protocols, care delivery models, and procurement reforms, meaning that long-term plans should remain modular rather than overly rigid.
These trends converge on a shared commercial theme: the winners will be those who can pair product performance with operational credibility. For suppliers, that means investing in the full system around the tube, including design controls, supplier management, labeling discipline, and post-market responsiveness. For buyers, it means weighting total reliability more heavily than sticker price. For investors, it means looking beyond top-line growth to assess the quality infrastructure and regulatory posture that sustain it.
Blood Tubing Set Market
Actionable Priorities for Different Decision-Makers
Manufacturers and product leaders should treat quality system strength as a core product attribute. Prioritize design controls, change control discipline, supplier management, and labeling accuracy with the same rigor applied to chemistry and materials. Where possible, align innovation with preanalytical reliability and usability improvements that reduce variability in the field. Build post-market surveillance and corrective action processes that can detect and resolve issues quickly, because responsiveness now directly affects market access and customer confidence. In parallel, develop portfolio strategies that recognize regional and application differences instead of assuming one configuration will fit all channels.
Investors and strategic financiers should focus on execution risk as much as growth potential. Top-line projections and category tailwinds are important, but the durability of those projections depends on regulatory readiness, quality culture, and supply chain discipline. Diligence should examine not only product features and distribution reach, but also documentation practices, supplier oversight, recall history, and the organization’s ability to manage change control without compromising consistency. Companies that can demonstrate both growth ambition and operational maturity are better positioned to convert market expansion into sustainable returns.
Procurement and supply chain leaders should move beyond unit cost comparisons and evaluate the total reliability of collection systems. That includes consistency of fill and separator performance, clarity of labeling, supplier governance, and the supplier’s track record in managing quality issues. Where possible, establish criteria that reward transparency, documented process control, and corrective action responsiveness. The goal is to reduce downstream laboratory variability and operational risk, not simply to minimize purchase price. Contracts and supplier reviews should reflect this broader value lens, especially as regulatory and clinical stakeholders place greater weight on sample integrity.
Across all three audiences, the common thread is the need for current, granular intelligence. Broad category trends provide direction, but the decisions that matter most—portfolio prioritization, channel strategy, supplier selection, diligence framing, and risk mitigation—require detailed segmentation, regional nuance, and updated regulatory and competitive context. Leaders who incorporate that depth into planning can act faster and with more confidence than those relying on aggregate narratives alone.
For teams seeking a sharper view of where value is accumulating and where risk is building, the full research report offers a closer look at segmentation dynamics, regional demand patterns, and company-level positioning. It is designed to support practical decisions in portfolio strategy, procurement, and investment diligence by pairing market context with detailed, actionable breakdowns. The deeper the intelligence, the more precisely a business can align its next move with the market’s actual shape rather than its anticipated shape.
For detailed analysis of this topic, please visit the official page: Blood Collection Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Niacin (Vitamin B3) Market: Why Asia Pacific’s 6.65% CAGR Reshapes Global Growth
By pmarketresearch, 2026-09-21
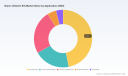
Strategic Shifts in the Niacin (Vitamin B3) Market: Navigating Growth, Consolidation, and Sustainable Innovation
The global niacin market has solidified its position as a high-growth specialty ingredient segment, driven by expanding applications across nutrition, pharmaceuticals, and personal care. With revenues reaching approximately 676 million USD in 2025 and a projected compound annual growth rate of 6.65 percent through 2032, the market is on a clear upward trajectory. This expansion is not merely a function of population growth or traditional feed demand; it reflects deeper structural changes in how formulators approach metabolic health, skin barrier function, and clean-label supply chains. For executives and investors, the niacin space presents a compelling balance of established demand drivers and emerging differentiation fronts. Understanding where value is created—and where margin pressure or regulatory friction will intensify—requires moving beyond headline figures and examining the interplay of feedstock dynamics, certification barriers, and strategic repositioning by leading suppliers.
Market Snapshot and the Anatomy of Growth
Growth in the niacin market has been steady rather than explosive, with annual revenue climbing from roughly 490 million USD in 2020 to the mid-670 million USD range by 2025. The forward curve points toward a market approaching 1.06 billion USD by 2032, indicating that incremental demand will be supported by both volume expansion and value migration toward higher-specification grades. The trajectory suggests that the next phase of growth will be less about raw volume and more about grade premiumization, application diversification, and regional production realignment.
Several structural characteristics define the current market environment. Demand is distributed across multiple end-use channels, with animal nutrition and human nutraceuticals representing the largest demand pools, while personal care and pharmaceutical applications serve as higher-margin, specification-driven niches. On the supply side, synthetic production dominates, reflecting the maturity of chemical synthesis routes and the scalability of established manufacturing hubs. Form factor preferences continue to favor dry formats for bulk handling and feed integration, while liquid variants maintain a differentiated role in formulation flexibility and specific cosmetic or pharmaceutical workflows.
PW Consulting
The market also exhibits a high degree of supplier concentration, with a small group of large-scale producers accounting for the majority of global capacity. This concentration has historically provided pricing stability and supply reliability for bulk grades, but it also concentrates risk around feedstock access, regulatory compliance pathways, and geopolitical exposure. As downstream customers increasingly demand traceability, sustainability credentials, and grade-specific documentation, the competitive frontier is shifting from pure cost leadership to capability-based differentiation.
Key Challenges and Inflection Points
Despite a favorable demand outlook, the niacin market faces several concurrent challenges that will shape investment decisions and sourcing strategies over the next few years.
- Feedstock volatility and petrochemical linkage. The primary precursor for niacinamide synthesis is tightly coupled to petrochemical market cycles. Price oscillations in this feedstock create margin variability for manufacturers and complicate long-term contract planning for buyers. Because a significant share of precursor supply and intermediate processing is concentrated in specific geographic regions, geopolitical disruptions or trade policy shifts can transmit quickly through the value chain.
- Regulatory and certification complexity. Pharmaceutical and nutraceutical grades require rigorous documentation, including pharmacopeial compliance and bioequivalence records at multiple production nodes. Regulatory frameworks across major markets mandate certifications that extend lead times and increase the cost of qualification. For animal feed and food applications, certifications related to quality management, food safety, and religious or dietary compliance have become baseline expectations rather than differentiators.
- Inventory cycles and qualification friction. In high-specification segments, extended lead times are increasingly tied to documentation and approval workflows rather than pure physical production constraints. Buyers in pharmaceutical and personal care channels must manage longer qualification cycles, which affects inventory planning and responsiveness to demand spikes. This dynamic rewards suppliers with integrated quality systems and penalizes those reliant on fragmented compliance processes.
These challenges do not undermine the market outlook; instead, they redefine where competitive advantage is earned. Suppliers that reduce qualification friction, stabilize feedstock exposure, and embed sustainability credentials into their operating models are better positioned to capture premium demand and defend margins.
Worldwide Cosmetic Grade Niacinamide Market
Core Growth Drivers: Innovation, Regulation, Demand, and Supply Chain Realignment
The niacin market is being reshaped by four interlocking drivers that will determine the pace and composition of growth through the late 2020s and into the early 2030s.
Technological Innovation and Specification Premiumization
Innovation in niacin and niacinamide is increasingly oriented around purity, sustainability, and application-specific performance rather than generic volume expansion. Bio-based feedstock approaches are gaining traction as formulators seek to align ingredient sourcing with broader environmental goals and consumer-facing sustainability narratives. In personal care, advanced niacinamide formats are being positioned around skin barrier support, redness reduction, and tolerability, which creates room for premium positioning when supported by robust documentation and stability data.
On the manufacturing side, process optimization and high-purity production capabilities are becoming important differentiators. Suppliers that can deliver consistent pharmaceutical-grade material with minimal batch variability and streamlined certification documentation are capturing share in higher-margin segments. This shift is especially pronounced where downstream brands are under pressure to reduce time-to-market while meeting stringent quality standards.
Policy, Regulation, and Certification as Commercial Gateways
Regulatory expectations are no longer a back-office compliance issue; they are a commercial gateway that shapes market access and supplier selection. Pharmaceutical and nutraceutical channels require pharmacopeial-grade compliance and documentation that supports bioequivalence and traceability. Food and feed channels increasingly treat certifications related to quality systems, food safety, and dietary compliance as standard procurement prerequisites. In practice, certification readiness determines which suppliers can enter tenders, which can scale with key accounts, and which can respond quickly to reformulation requests.
This environment favors scaled producers with established regulatory infrastructure, but it also creates opportunities for specialized manufacturers that can offer targeted grade solutions with faster qualification cycles. For buyers, the implication is clear: supplier selection should weigh not only unit cost but also the speed and reliability of documentation, the breadth of certification coverage, and the supplier’s ability to support regional regulatory variations.
Demand-Side Evolution: Nutrition, Personal Care, and Formulation Trends
Demand is being reshaped by two broad consumer and industry trends. In human nutrition, interest in metabolic health, B-vitamin supplementation, and functional ingredients continues to support steady demand for niacin in dietary supplement formats. In personal care, niacinamide remains a cornerstone ingredient for skin health formulations, and the rise of sensitive-skin positioning, barrier-focused skincare, and clean-label ingredient narratives creates additional demand pull. These channels are not growing at the same rate, but together they diversify the demand base and reduce dependence on any single end-use cycle.
Animal nutrition remains a large demand anchor, particularly where feed fortification and livestock productivity considerations support consistent volume. However, growth in this channel is more cyclical and cost-sensitive than in nutraceuticals or personal care. The differing demand characteristics across channels mean that successful suppliers often need segment-specific commercial models rather than a single one-size-fits-all approach.
Supply Chain Structure and Cost Dynamics
The supply chain for niacin is characterized by concentrated precursor access, regional production hubs, and grade-specific logistics requirements. Feedstock price movements translate directly into cost variability, and because precursor sourcing is exposed to petrochemical cycles and regional supply risks, manufacturers must manage both price and availability simultaneously. The result is that contract structures, inventory positioning, and multi-source strategies matter as much as production capacity.
At the same time, grade differentiation is reshaping logistics and lead times. Pharmaceutical-grade workflows require more rigorous documentation at each production node, which extends qualifying lead times and influences inventory strategy. For buyers, this creates a trade-off between responsiveness and compliance assurance. Suppliers that can compress qualification timelines without compromising documentation integrity will gain commercial leverage, particularly in fast-moving personal care and supplement channels.
Nicotinamide (NAA) (aka Niacinamide) Market
Competitive Landscape: Concentration, Differentiation, and Strategic Realignment
The niacin market is defined by a concentrated group of large-scale producers alongside specialized manufacturers that compete on grade, purity, and application focus. The leading players span chemical synthesis expertise, life sciences orientation, and contract manufacturing capabilities, creating a diversified competitive field in which companies differentiate through distinct value propositions rather than through undifferentiated capacity alone.
Several patterns stand out in the current landscape.
- Large-scale producers anchor bulk and feed demand. Established chemical synthesis capabilities support high-volume supply for animal nutrition, food, and industrial applications. These players compete on scale, reliability, and cost management, while increasingly adding grade-specific offerings to capture higher-margin demand.
- Life sciences and pharmaceutical-focused suppliers emphasize documentation and purity. Companies with strong pharmaceutical-grade infrastructure position around compliance, quality systems, and consistency. Their differentiation lies in the ability to meet rigorous pharmacopeial expectations and support bioequivalence and traceability requirements.
- Specialized and mid-sized manufacturers target niche grades and faster qualification. Some suppliers focus on personal care, supplement, or cosmetic-grade solutions, emphasizing flexibility, application support, and certification breadth. This positioning can be attractive to brands that value responsiveness and tailored technical support.
- Regional production dynamics create both opportunity and risk. With significant manufacturing capacity concentrated in specific regions, supply chain resilience depends on multi-source strategies, regional qualification readiness, and the ability to manage feedstock and logistics exposure.
The competitive field is also evolving through strategic realignment. Recent portfolio moves in the broader nutrition and health ingredients space illustrate how companies are reshaping their exposure to vitamin portfolios and adjacent businesses. Divestitures of animal nutrition and health-related assets by major players reflect a broader trend toward portfolio simplification and focus on higher-value or strategically aligned segments. At the same time, product-level innovation continues to expand the differentiation frontier. The introduction of bio-based niacinamide lines for personal care, combined with visible presence at regional industry events, signals that sustainability and application-specific messaging are becoming central to commercial positioning in cosmetics and skin health.
Taken together, these dynamics suggest a market that will continue to consolidate around capable, well-documented suppliers while also opening space for differentiated players in higher-specification niches. New entrants will face meaningful barriers in pharmaceutical and nutraceutical grades due to certification requirements, but may find more accessible pathways in cosmetic or supplement segments if they can demonstrate quality, consistency, and clear application value.
Looking Ahead: Three Trends Shaping the Next 3–5 Years
Based on current demand patterns, regulatory direction, and supplier behavior, three trends are likely to define the niacin market over the next several years.
Trend 1: Premium-grade migration and application diversification
As downstream brands seek differentiation, demand will increasingly shift toward grades that offer stronger documentation, consistent purity, and specific performance profiles. Pharmaceutical and nutraceutical channels will continue to reward suppliers with robust quality systems, while personal care and supplement segments will place greater emphasis on tolerability, stability, and sustainability narratives. This premium-grade migration creates margin opportunities for suppliers that can support higher specification requirements without sacrificing reliability.
Trend 2: Sustainable sourcing and bio-based differentiation
Sustainability credentials will move from baseline expectations to active commercial differentiators, especially in personal care and consumer-facing nutrition. Bio-based feedstock approaches, traceability improvements, and certifications aligned with dietary and religious requirements will matter more as brands use ingredient sourcing as part of their broader market positioning. Suppliers that can substantiate sustainability claims with verifiable processes and certifications will be better placed to capture preference-driven demand.
Trend 3: Supply chain resilience and qualification speed as core capabilities
Feedstock volatility, regional concentration, and documentation-heavy qualification workflows will make supply chain resilience a central competitive factor. Buyers will increasingly value suppliers that can offer predictable lead times, transparent compliance documentation, and flexible sourcing strategies. The ability to shorten qualification cycles while maintaining regulatory integrity will become a meaningful advantage, particularly for accounts that need to scale quickly or support reformulation programs.
These trends also carry risks. Feedstock price swings can compress margins if not managed through contract design or hedging approaches. Regulatory divergence across regions may increase complexity for globally distributed portfolios. And sustainability claims will face greater scrutiny, meaning that unsubstantiated positioning can create reputational and commercial exposure. The winners will be those who treat resilience, documentation, and credible sustainability as integrated capabilities rather than isolated initiatives.
Strategic Implications for Decision Makers
For executives, planners, and investors, the niacin market offers a mix of stable demand foundations and evolving differentiation opportunities. The strategic question is less whether the market will grow and more how to position for the kind of growth that will arrive.
For manufacturers and suppliers
Focus on grade-specific capability building. Invest in documentation infrastructure, pharmacopeial compliance readiness, and certification breadth that aligns with the channels you intend to serve. If sustainability is part of your positioning, ensure it is backed by verifiable processes and certification coverage that buyers can audit. Consider how feedstock exposure is managed in contracts and inventory planning, because cost variability will remain a persistent margin factor. Where possible, build segment-specific commercial models that match the purchasing logic of feed, supplements, personal care, and pharmaceutical customers rather than applying a single pricing and service model across all channels.
For investors
Evaluate exposure through the lens of grade mix and channel concentration. Businesses with stronger positioning in pharmaceutical, nutraceutical, or premium personal care segments may offer better margin resilience than those dependent primarily on cost-sensitive bulk channels. Pay attention to supply chain structure, regulatory readiness, and the credibility of sustainability claims, since these factors increasingly determine scalability and procurement preference. Also watch portfolio realignment activity across the larger nutrition and health ingredients space, as divestitures and refocusing can reshape competitive dynamics and create both acquisition and partnership opportunities.
For procurement and sourcing leaders
Treat supplier selection as a multi-dimensional decision. Unit price should be weighed against qualification speed, certification coverage, documentation reliability, and supply continuity. For pharmaceutical and supplement-grade procurement, the cost of delayed qualification or compliance gaps can exceed the apparent savings from lower-priced sources. Diversify sourcing where feasible to reduce exposure to feedstock and regional concentration risks, and align inventory strategies with the lead-time realities of higher-specification grades. Request clear evidence of certification status, traceability, and process consistency, especially when sustainability or grade claims are part of the sourcing decision.
Where deeper intelligence adds value
The niacin market is large enough to support multiple successful strategies, but the right strategy depends on segment-specific data that goes beyond aggregate growth figures. Detailed segmentation, regional demand intensity, grade-level margin structures, feedstock cost sensitivities, and competitor-specific capability maps can materially change sourcing, investment, and product roadmap decisions. For teams that need to move from broad market confidence to precise execution planning, deeper segmentation data and tailored competitive assessments provide the granularity required to prioritize capacity, negotiate contracts, and shape formulation strategies with greater confidence.
For detailed analysis of this topic, please visit the official page: Niacin (Vitamin B3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Brown Sugar Market 2026: Beyond the 7.4% CAGR Growth Trajectory and Strategic Shifts
By pmarketresearch, 2026-09-21
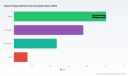
Strategic Trends and Commercial Opportunities in the Brown Sugar Market
The global brown sugar market demonstrates a trajectory of steady, quality-driven expansion as the industry transitions from a commoditized sweetener segment into a differentiated value category. In 2025, the market reached an estimated 2.39 billion USD in revenue, reflecting compounded growth from 1.88 billion USD in 2020. Looking ahead through 2032, the sector is projected to expand at a seven-point-four percent compound annual growth rate, crossing the 3.9 billion USD threshold by the end of the forecast window. This growth is not uniform across all categories; it is increasingly shaped by application-specific demand, regional consumption patterns, and a measurable shift toward premium and specialty formats. The market remains structurally fragmented, with the top three participants accounting for roughly twenty-five percent of total revenue and the top five capturing just under twenty-nine percent. Such concentration levels indicate that while scale advantages exist, competitive advantage is increasingly determined by formulation precision, sourcing reliability, and the ability to align product attributes with downstream manufacturing requirements.
Current Landscape and Critical Inflection Points
The brown sugar market sits at a notable intersection where volume growth, functional utility, and premiumization intersect. Historical volatility during the early part of the decade stabilized into a more predictable expansion curve, but that pattern is now being tested by a combination of supply-side constraints and demand-side recalibration. Industry participants are navigating an environment where raw material availability, trade policy adjustments, and formulation requirements intersect more frequently than in prior cycles.
Several structural challenges are actively shaping strategic decision-making. First, the sector faces ongoing sensitivity to input cost dynamics and sourcing stability. Sugar production is heavily influenced by seasonal conditions, regional cropping outcomes, and trade mechanism adjustments, all of which introduce variability into cost planning for industrial buyers. This is especially relevant for manufacturers that rely on consistent moisture content, molasses balance, and particle size to maintain product consistency across bakery lines, beverage formulations, and confectionery production.
Second, the market is confronting a divergence between traditional bulk demand and rising expectations for specification-grade, specialty-format products. While staple applications continue to drive baseline consumption, growth is increasingly tied to categories that require precise flavor profiles, clean-label alignment, and traceability. Suppliers that operate primarily in undifferentiated bulk segments are finding it harder to protect margins, whereas those capable of delivering consistent functional attributes and certification-backed positioning are capturing stronger downstream preference.
Third, regulatory and trade frameworks continue to shape regional accessibility and pricing stability. In major consuming markets, import mechanisms and domestic support arrangements influence the flow of raw and refined inputs, affecting both cost structures and supply planning. Companies that depend on cross-border sourcing must account for quota allocations, suspension agreements, and the periodic recalibration of trade thresholds, all of which can alter short-term availability and long-term procurement strategy.
Key Drivers Shaping Market Evolution
The expansion trajectory of the brown sugar market is not simply a function of population growth or broad sweetener consumption. It is being reshaped by a set of interacting drivers that reward operational precision and market-specific positioning.
One significant driver is the evolution of product formulation and process control. Producers are increasingly differentiating through controlled molasses integration, crystallization techniques, and variant consistency across light and dark formats. This matters because downstream users in bakery, beverage, and confectionery applications depend on predictable color, moisture, and flavor intensity to maintain line efficiency and product quality. Suppliers that invest in tighter specification control and flexible packaging formats are better positioned to serve industrial customers who require repeatability across batches and reduced rework.
A second driver is the alignment of product positioning with consumer-facing expectations around ingredient transparency. Clean-label considerations, non-genetically modified verification, vegan compatibility, and Kosher certification are no longer peripheral claims; they are becoming operational procurement criteria for food manufacturers that must meet retail and foodservice requirements. Offerings that combine domestically grown cane or beet inputs with verified certification structures are gaining traction, particularly in applications where label simplicity and ingredient sourcing are closely scrutinized.
A third driver is the structural shift in application demand. Brown sugar continues to hold relevance in bakery environments, where its moisture contribution and flavor depth support product differentiation in breads, pastries, and specialty doughs. At the same time, beverage and confectionery uses are expanding as formulators seek cost-effective yet distinctively flavored sweetening options. Dairy and adjacent applications remain smaller in relative scale but are becoming more relevant in flavored products and functional blends, where brown sugar’s organoleptic properties can be leveraged without requiring major formulation redesign.
A fourth driver is the interaction between supply-side planning and policy environment. Recent market intelligence from agricultural outlook agencies emphasizes continuing supply and utilization monitoring for U.S. sugar markets based on broader agricultural supply and demand estimates. At the same time, tariff-rate quota allocations for raw sugar are set annually to align with multilateral trade commitments, and domestic support mechanisms operate alongside suspension agreements with Mexico to stabilize input flows. These mechanisms do not merely influence pricing; they shape procurement timing, contract design, and the relative attractiveness of domestic versus imported sourcing strategies.
Taken together, these drivers create a market where competitive advantage is increasingly less about volume alone and more about the ability to deliver specification reliability, certification alignment, and procurement predictability. Companies that treat brown sugar as a functional ingredient rather than a passive sweetener are capturing stronger value capture across industrial and retail channels.
Competitive Landscape and Leading Strategies
The competitive environment in the brown sugar market is characterized by a mix of large diversified sugar producers, regional specialty manufacturers, and brand-focused refiners. No single entity dominates the category, and the moderately fragmented structure creates room for differentiation through crop origin, processing technology, and downstream application focus.
Among the most strategically visible participants, several patterns stand out. One major global food and agriculture company emphasizes a pure cane sugar base combined with molasses, supported by non-GMO verification, vegan-friendly positioning, and Kosher compliance. Its offering is structured to serve bakery, confectionery, sauce, and canned product production, with both bulk and retail packaging options. This model illustrates a broader competitive logic: pairing supply consistency with certification attributes that downstream food manufacturers can use as procurement assurance.
Another leading European producer focuses on crystalline and soft brown sugar produced by crystallizing beet or cane syrups with caramel syrup. Its dual-format approach enables participation across bakery, biscuit, cereal, sauce, and beverage segments, emphasizing formulation versatility. This flexibility is strategically important for industrial buyers that seek one supplier capable of meeting varied processing requirements without sacrificing specification consistency.
Regional processors also play a meaningful role. A U.S.-based beet sugar producer delivers liquid and brown sugars under a well-known regional brand, targeting industrial, commercial, and retail customers. Its relevance lies in localized sourcing and processing capabilities, which can reduce exposure to certain import-related variables and support steady supply for domestic food manufacturers. A major U.S. cane sugar refiner maintains strong brand recognition through established consumer and foodservice labels, while an Oregon-based cooperative and a Hong Kong-based cane sugar producer extend the competitive map across beet-and-cane portfolios and regional export markets.
In Southern Africa, a mill focused on high-quality VHP brown sugar illustrates how regional production can serve both local consumption and export-adjacent demand, particularly where quality consistency and processing standards are key to maintaining market access. Meanwhile, brand-oriented U.S. offerings in light and dark brown sugar continue to reinforce the importance of format clarity and application-specific naming for foodservice and retail buyers.
Across these participants, several strategic themes emerge. First, differentiation is increasingly achieved through a combination of sourcing origin, certification readiness, and format flexibility rather than price competition alone. Second, leading players are investing in the ability to serve industrial customers with reliable batch consistency and packaging options that match processing environments. Third, brand and label equity remains valuable in retail and foodservice channels, where recognition and compliance attributes streamline purchasing decisions.
The market structure also points to ongoing evolution rather than abrupt consolidation. While scale players benefit from procurement leverage and distribution breadth, smaller or regionally anchored producers can compete by specializing in specific formats, crop-based narratives, or application-focused solutions. New entry remains feasible in niche segments where certification, organic positioning, or regenerative agriculture credentials align with buyer requirements, but scaling such offerings typically depends on supply reliability and cost discipline.
Forward Outlook: Key Trends for the Next Three to Five Years
Looking toward the next several years, the brown sugar market is likely to be defined by three interrelated trends.
The first trend is continued premiumization within a still-substantial bulk baseline. Light and dark variants will remain core, but demand growth will increasingly concentrate in specification-managed products that offer predictable flavor intensity, controlled moisture, and certification support. Manufacturers that can standardize these attributes across batches will gain preference in bakery, confectionery, and beverage environments where formulation integrity is critical. This trend favors suppliers that can combine processing precision with transparent documentation and flexible pack sizes.
The second trend is deeper integration between sourcing strategy and regulatory awareness. Because trade mechanisms, quota allocations, and domestic support arrangements influence input availability and cost planning, procurement teams are likely to place greater emphasis on scenario-based sourcing, multi-origin flexibility, and contract structures that reduce exposure to short-term supply shocks. In practical terms, this means brown sugar procurement will become more strategic and less transactional, with buyers evaluating suppliers not only on price but also on reliability under changing trade conditions.
The third trend is the growing relevance of sustainability-linked sourcing narratives where they can be credibly documented and linked to buyer requirements. Organic certification, regenerative agriculture claims, and non-GMO verification are already present in portions of the market, and their commercial importance is likely to increase as food manufacturers seek to align ingredient sourcing with broader label and corporate expectations. The opportunity here is not simply in claims, but in the ability to provide traceable, repeatable sourcing that can withstand procurement scrutiny.
PW Consulting
These trends create tangible commercial opportunities. Suppliers that invest in specification control, certification readiness, and procurement transparency can capture stronger positioning with industrial buyers. Food manufacturers that align product development with brown sugar’s functional profile can use it as a differentiation lever in bakery and beverage portfolios. Investors and strategic planners can focus on the segments where application growth, certification alignment, and supply reliability intersect, rather than assuming uniform growth across all formats and regions.
At the same time, uncertainty remains. Input availability can shift with seasonal outcomes and trade policy adjustments. Certification and labeling requirements may evolve, affecting the cost and feasibility of certain positioning strategies. In addition, any broadening of tariff-rate quota constraints or changes to suspension agreements could alter the relative cost balance between domestic and imported supply in key markets. Companies that build flexibility into sourcing and product planning will be better positioned to navigate these variables.
Strategic Actions for Decision Makers
For manufacturers and brand owners, the priority is to treat brown sugar as a functional, specification-sensitive ingredient. This means aligning procurement with clear technical requirements for moisture, molasses balance, particle characteristics, and certification needs. Where possible, establish supplier relationships that provide batch consistency documentation and flexible packaging options suited to production environments. For product development teams, brown sugar can be used not only as a sweetener but also as a flavor and texture lever in bakery, beverage, and confectionery applications, provided formulation consistency is safeguarded.
For procurement and supply chain leaders, the emphasis should be on resilience and predictability. Evaluate sourcing options against not only unit cost but also supply reliability under changing trade and quota conditions. Consider multi-origin or mixed-format strategies where applicable, and structure contracts to reduce exposure to short-term input volatility. Maintain visibility into regulatory updates that affect import mechanisms and domestic support arrangements, since these can influence both availability and planning horizons.
Sugar Sphere Market
For investors and strategic planners, the opportunity lies in identifying participants and segments that combine scale, specification control, and credible certification or sourcing narratives. The market is large enough to support diverse models, but long-term outperformance is likely to favor those that can deliver consistent quality, serve industrial requirements efficiently, and adapt to evolving buyer expectations around transparency and sourcing. Monitoring application-side uptake, regional supply dynamics, and trade framework adjustments will be essential for anticipating shifts in competitive positioning.
For all of the above, the value of timely, granular intelligence is clear. Market-level projections provide useful direction, but operational decisions depend on detail: segment-by-segment demand patterns, specification preferences, sourcing constraints, certification adoption, and the cadence of regulatory and trade updates. Detailed reporting that breaks down these layers can support more precise planning, from product roadmap design to supplier selection and investment prioritization.
As the brown sugar market continues its transition toward more differentiated, specification-driven growth, the strategic question is no longer whether the category will expand, but how companies will position themselves to capture value within it. Those that combine process discipline, procurement awareness, and clear alignment with downstream application needs are best placed to convert market growth into durable commercial advantage.
Worldwide Brown Rice Market
For detailed analysis of this topic, please visit the official page: Brown Sugar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pressure Vessels Market Explores the 4.93% CAGR Growth Path Beyond 2026
By pmarketresearch, 2026-09-21
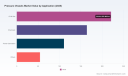
Pressure Vessels Market: Strategic Trends and Commercial Opportunities Through 2032
The global pressure vessels market has entered a phase of disciplined expansion, shaped by infrastructure reinvestment, evolving safety standards, and a gradual shift toward higher-specification equipment. Valued at approximately $422.4 million in 2020, the market reached $550.2 million in 2025 and is projected to grow to $769.0 million by 2032, reflecting a compound annual growth rate of 4.93 percent. This trajectory signals steady demand rather than explosive growth, with value increasingly concentrated in applications that demand tighter tolerances, advanced materials, and rigorous compliance. For executives and investors, the picture is one of a maturing industrial segment where margin differentiation, certification agility, and supply chain resilience matter more than volume alone.
PW Consulting
Market Snapshot and Structural Headwinds
The market’s growth path over the past five years reveals a sector that recovered from pandemic-era disruptions and then settled into a more predictable expansion rhythm. Revenue climbed from $431.72 million in 2021 to $473.83 million in 2022, pushed higher to $508.09 million in 2023, and reached $550.2 million in 2025 as capital spending in key end-use sectors stabilized. Forecasts extending to 2032 indicate a gradual acceleration in later years, with values moving from $578.92 million in 2026 toward $716.08 million in 2030 and $769.0 million by 2032. This pattern suggests that growth will be uneven across cycles, tied closely to project sanctioning timelines, regulatory adoption, and the pace of industrial modernization.
Despite the favorable top-line trajectory, the industry faces a set of structural challenges that will define competitive outcomes over the forecast horizon.
Cost Volatility and Material Sensitivity
Steel and alloy pricing remains the single largest cost variable for pressure vessel manufacturers, with carbon steel accounting for 35 percent to 45 percent of total production cost. This exposure means that margin compression can occur quickly when input prices spike or when contractual pass-through mechanisms lag behind market movements. Companies that rely on fixed-price bidding without hedging or index-linked clauses are particularly vulnerable. The practical implication is that procurement discipline, long-term supplier agreements, and design choices that optimize material usage are becoming strategic levers rather than operational details.
Regulatory Tightening and Compliance Burden
The 2025 ASME Boiler and Pressure Vessel Code (BPVC) Section VIII was published with new additions and enhancements for the design and construction of fired and unfired pressure vessels, becoming mandatory for compliance. Alongside this, the 2025 edition introduces updated rules for flanges and design by analysis, with educational webinars scheduled for March 2026 to explain impacts on pressure vessel design and documentation. On the inspection side, API 510 certification publications took effect for September 2025 through May 2026 exams and September 2026 through May 2027 exams, governing pressure vessel inspector qualifications. Together, these developments raise the bar for documentation, testing, and personnel certification. For manufacturers, the upside is a higher barrier to entry that benefits established, code-certified players; the downside is increased time-to-market and administrative overhead, especially for smaller fabricators.
Project Economics and Demand Cyclicality
Demand for pressure vessels is closely linked to large-project sanctioning in energy, chemicals, and power generation. When capital budgets tighten or project timelines slip, equipment orders can be delayed rather than cancelled, creating lumpy order books and unpredictable cash flow patterns. Companies that diversify across multiple verticals and offer modular or repowering solutions tend to smooth these cycles more effectively. The broader lesson is that dependency on a single sector or project type amplifies exposure to macroeconomic and policy shifts.
Key Drivers Reshaping the Market
Several interlocking forces are pushing the market beyond baseline growth and redefining where value is created.
Technology Innovation and Advanced Fabrication
Additive manufacturing and precision fabrication are gradually expanding the design envelope for high-pressure, high-temperature components. A notable example is SAMSON AG’s November 2025 achievement of CE certification from TÜV SÜD Industrie Service GmbH for its additively manufactured high-pressure valve, Type 3251-AM, enabling full market availability up to DN 100/PN 400. This milestone illustrates how certified additive processes can move from prototyping to commercial deployment, particularly where complex geometries, weight reduction, or rapid iteration offer tangible benefits. For pressure vessel ecosystems, the implication is broader than a single product: qualification pathways are opening for advanced manufacturing methods, and firms that invest early in certification, material validation, and digital design tools can capture premium segments that value performance and lead-time advantages.
Policy and Regulatory Environment
Regulatory frameworks are both a constraint and a catalyst. Mandatory updates to the ASME BPVC and the ongoing API 510 certification cycles increase the compliance burden, but they also reinforce the value of established quality systems and multi-code capabilities. In practice, this tends to favor manufacturers that can navigate multiple codes simultaneously and provide end-to-end documentation support. Regions with active plant safety initiatives, aging infrastructure replacement programs, and stringent inspection regimes are likely to see steadier demand for replacement and upgrade vessels, while newer project markets may prioritize first-time certification and faster delivery. The strategic takeaway is that regulatory competence is becoming a differentiator, not just a compliance checkbox.
Demand-Side Shifts in End-Use Industries
End-use industries are pushing pressure vessel specifications in two directions: higher durability for harsh operating environments and greater flexibility for modular or distributed installations. In oil and gas, chemicals, and power generation, operators are increasingly attentive to lifecycle costs, inspection intervals, and material degradation under elevated pressures and temperatures. This favors vessels designed for easier maintenance, better corrosion resistance, and compatibility with advanced monitoring. At the same time, some applications are shifting toward standardized, repeatable designs that reduce engineering overhead while preserving code compliance. The net effect is a bifurcated demand profile: high-spec custom work remains important, but there is growing value in repeatable platforms that can be deployed quickly across multiple sites.
Supply Chain and Cost Structure Evolution
Because material costs dominate production economics, supply chain strategy is now a core margin lever. Manufacturers are increasingly looking at long-term steel and alloy agreements, localized sourcing to reduce logistics risk, and design-for-manufacturability practices that reduce scrap and machining time. Digital procurement visibility and inventory buffering for critical materials are also gaining traction as ways to protect delivery commitments during volatile periods. Companies that integrate sourcing, design, and production planning more tightly are better positioned to hold margins without sacrificing competitiveness on price.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three firms holding approximately 32.5 percent of revenue and the top five reaching about 38.2 percent. This level of concentration indicates a landscape where a handful of capable players command meaningful share, but ample room remains for specialized manufacturers, regional fabricators, and system integrators that can differentiate on service, certification breadth, or application expertise.
Strategic Positioning Among Established Players
A review of leading participants shows a clear split between large, multi-code equipment suppliers and focused fabricators that compete on customization, speed, or niche expertise.
- Samuel Pressure Vessel Group operates as an ASME-certified fabricator with emphasis on custom and standard vessels for industrial applications, positioning around flexibility and proven code compliance.
- Modern Welding Company, Inc. specializes in custom fabrication for process, storage, and high-pressure applications, appealing to customers that need tightly specified components and responsive engineering support.
- Larsen & Toubro Limited provides large-scale process plant pressure vessels and equipment for oil & gas, power, and chemical sectors with multi-code certifications, which supports complex, cross-border projects where regulatory diversity matters.
- Doosan Heavy Industries & Construction Co., Ltd. manufactures heavy process equipment including pressure vessels for power generation and petrochemical applications, leveraging scale and integration with broader plant systems.
- Mitsubishi Heavy Industries, Ltd. supplies pressure vessels for energy, nuclear, and industrial high-temperature/high-pressure applications, aligning with sectors that demand rigorous performance and long service life.
- Bharat Heavy Electricals Limited offers pressure vessels and process equipment for power generation, oil & gas, and chemical processing industries, benefiting from strong positioning in large infrastructure programs.
- IHI Corporation fabricates pressure vessels for high-pressure and high-temperature industrial and energy applications, competing on technical capability in demanding operating conditions.
On the specialized and regional side, a second tier of manufacturers competes through precision, filtration integration, and application-specific solutions.
Electric Pressure Cooker Market
- Precision Custom Components, LLC is recognized among top suppliers with a focus on precision fabrication, appealing to customers that prioritize dimensional accuracy and repeatability.
- APEX Engineered Products specializes in engineered pressure vessels and components for industrial and process applications, positioning around tailored engineering rather than commodity supply.
- Industrial Filter Manufacturers, Inc. provides pressure vessel solutions integrated with filtration systems for industrial use, creating value through combined functional packages.
- Buckeye Fabricating Company and Manchester Tank & Equipment are PVMA members with ASME certification, emphasizing industrial and process industry supply as well as equipment provision.
- Quality Steel Corporation produces steel-based pressure vessels for industrial applications, reflecting the importance of material-grade specialization.
- TRIARC Tank, LLC and Worthington Enterprises contribute additional fabrication and manufacturing services within the PVMA member ecosystem, reinforcing the role of accredited fabricators in meeting regional demand.
- Petrosmith Equipment, LP focuses on pressure vessel solutions for oil and gas applications, highlighting the continued relevance of sector-specific expertise.
These profiles reveal a market where competitive advantage is built on a combination of code certification, application knowledge, fabrication precision, and the ability to deliver integrated solutions rather than isolated hardware.
How Leaders Differentiate
Top performers tend to differentiate along four dimensions. First, multi-code certification and documentation capability reduce friction for customers operating across jurisdictions. Second, engineering-led customization enables firms to capture higher-margin work in complex or extreme-service applications. Third, integration with adjacent systems, such as filtration or monitoring, creates more complete offerings that can command stronger customer stickiness. Fourth, supply chain and material management discipline protects margins in an environment where steel and alloy costs remain the dominant variable. Companies that combine several of these strengths are better positioned to weather cycles and defend share.
Structural Evolution of the Landscape
The competitive map is evolving through selective consolidation, specialization, and new entry where certification and engineering capabilities allow. Larger suppliers are well placed to benefit from project scale, multi-code complexity, and global delivery requirements. At the same time, smaller and regional fabricators can thrive by serving localized demand, niche applications, or customers that value shorter lead times and closer collaboration. Additive manufacturing certification, such as the SAMSON AG CE approval, hints at a longer-term opening for new approaches to component production, especially where design complexity or throughput advantages can be validated under recognized codes. The likely outcome is a continued mix of scale players, specialized engineers, and certified fabricators, with differentiation increasingly tied to compliance agility and solution breadth.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to shape where growth and margin opportunities emerge.
Stabilization Around Code-Driven Quality and Documentation
With the 2025 ASME BPVC updates and ongoing API 510 certification cycles, the market will place greater weight on design-by-analysis competence, flange rule compliance, and inspector qualifications. This creates opportunities for firms that can offer robust documentation packages, training-aligned inspection support, and design services that reduce rework. Customers will increasingly value partners that can accelerate approvals and minimize compliance risk, which can translate into preference for suppliers with established quality systems and clear traceability.
Premium Segments in High-Temperature, High-Pressure Applications
Demand for vessels that can operate reliably under more severe conditions is expected to remain a focal point, particularly in power generation, energy, and chemical processing. This favors manufacturers with strong high-temperature and high-pressure expertise, advanced material selection, and proven performance records. Commercial opportunities include replacement and upgrade programs for aging assets, as well as new installations where operating envelopes are expanding. Firms that can demonstrate lifecycle value through reduced inspection frequency, better corrosion resistance, or improved durability will have a stronger value proposition than those competing solely on initial price.
Modular, Repeatable Platforms and Integrated Solutions
A countertrend to bespoke engineering is the growing appeal of standardized, modular designs that can be deployed across multiple sites with predictable lead times and lower engineering overhead. This is especially relevant where operators seek to scale capacity without repeating full custom cycles for each unit. Integrated offerings that combine pressure vessels with filtration, instrumentation, or monitoring can also increase project value and simplify procurement for end users. The commercial opportunity lies in building platform-based portfolios that preserve code compliance while improving scalability and delivery consistency.
Pressure Vessel Composite Materials Market
Material Strategy as a Margin Lever
Given that carbon steel represents 35 percent to 45 percent of production cost, material strategy will remain central to profitability. Companies that secure stable sourcing, optimize wall thickness and form factors through better design, and use index-linked contracting where appropriate will be better able to protect margins through input price swings. There is also opportunity in specifying alternative grades or coatings where they extend service life and reduce total cost of ownership, particularly in corrosive or cyclic service environments.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Project sanctioning delays in major end-use sectors can shift demand timing and create uneven order books. Regulatory interpretation and adoption rates may vary by region, affecting how quickly new code provisions translate into procurement requirements. Input cost volatility can compress margins if not managed through sourcing and contract structures. Finally, the pace at which advanced manufacturing methods achieve broad code acceptance and customer confidence will determine whether additive and related approaches expand beyond niche applications in the near term.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to convert compliance and engineering capability into visible commercial advantage. That means investing in multi-code documentation, design-by-analysis proficiency, and qualification pathways for advanced fabrication methods, while protecting margins through disciplined material sourcing and design-for-manufacturability practices. Building platform-based product families can improve delivery predictability and expand addressable volume without diluting the ability to take on custom work where margins are stronger.
For investors, the opportunity set favors companies that combine certification breadth, application expertise, and margin resilience rather than those chasing volume alone. Attention should be paid to firms with diversified end-market exposure, stable sourcing strategies, and the ability to serve high-temperature or high-pressure segments where barriers are higher and value is more defensible. Monitoring how quickly advanced manufacturing certifications translate into commercial adoption will also provide early signals about emerging competitive dynamics.
For procurement and engineering leaders, the focus should be on total lifecycle value and compliance risk reduction. Evaluating suppliers on documentation quality, inspection support, material strategy, and integration capability can reduce project risk and improve long-term performance. Where possible, favoring repeatable platforms with proven code compliance can shorten lead times and simplify multi-site deployment, while reserving custom engineering for applications where operating conditions truly demand it.
For those seeking a deeper dive into segment-level sizing, regional demand patterns, and company-specific positioning, the full research report provides detailed breakdowns and customized recommendations tailored to specific strategic questions.
For detailed analysis of this topic, please visit the official page: Pressure Vessels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electrohydraulic Actuator Market: Why the 6.8% CAGR Reshapes Strategy 2026–2032
By pmarketresearch, 2026-09-21
The Electrohydraulic Actuator Market: Strategic Trends and Commercial Opportunities Through 2032
The electrohydraulic actuator market has reached a structural inflection point. Valued at approximately 247.0 million USD in 2025, the sector has expanded from 180.0 million USD in 2020, compounding at an estimated 6.8 percent annually through the forecast horizon that extends to 2032. By the end of that period, total market revenue is projected to approach 392.0 million USD. These figures reflect more than steady expansion; they signal a market where demand is being reshaped by technological maturation, regulatory pressure, and shifting application requirements. For executives and investors, the critical question is no longer whether the sector will grow, but where value will concentrate and which capabilities will separate durable players from marginal suppliers.
Electro Hydraulic Servo Valve Market
Market Context and Defining Challenges
The current landscape is characterized by broad-based adoption across industrial automation, energy infrastructure, and specialized manufacturing. Linear configurations continue to command the larger revenue share, while rotary variants serve niche motion-control requirements where rotational precision and compact form factors are paramount. Applications span heavy industry, power generation, oil and gas infrastructure, and automotive systems, with industrial end-use segments representing the largest demand pool. Geographically, Asia Pacific generates the highest regional revenue, followed by North America and Europe, while Latin America and the Middle East & Africa contribute smaller but growing shares as industrial modernization and energy-sector investments accelerate. The market remains moderately fragmented, with the top three suppliers capturing roughly 32 percent of total revenue and the top five accounting for approximately 42 percent, leaving meaningful space for specialists and regional integrators.
PW Consulting
Despite the positive trajectory, the industry faces several structural challenges that will define competitive outcomes over the next half-decade:
- Efficiency and energy-cost pressures are forcing operators to reconsider traditional hydraulic architectures. Stringent energy-efficiency regulations and rising utility costs are accelerating the shift toward electrohydraulic designs that reduce parasitic losses, minimize idle consumption, and lower emissions footprints. Suppliers that cannot demonstrate measurable efficiency gains risk losing specification decisions to conventional electric or fully hydraulic alternatives.
- Integration complexity and standardization gaps persist across applications. End users increasingly demand plug-and-play reliability, yet electrohydraulic systems still require careful matching of power supply architecture, control logic, sealing integrity, and environmental protection. The absence of universally adopted integration standards creates customization burdens, lengthens validation cycles, and raises total cost of ownership for multi-site deployments.
- Supply-chain resilience and material durability have become decisive procurement criteria. Harsh operating environments—mining sites, refineries, underwater installations, and safety-critical valve networks—expose actuators to corrosion, vibration, and temperature extremes. Components that rely on proprietary, non-repairable assemblies face scrutiny, while designs emphasizing replaceable parts and robust housing materials gain preference in maintenance-intensive settings.
For decision-makers, these challenges are not merely technical obstacles; they are commercial filters. Procurement teams are increasingly evaluating actuators on lifecycle cost, maintainability, functional safety, and energy performance rather than upfront price alone. That shift rewards suppliers who can document reliability, certify safety performance, and offer serviceable architectures.
Core Drivers Reshaping Demand and Supply
Technology Innovation and Performance Breakthroughs
Performance gains are redefining what electrohydraulic actuators can accomplish. Recent product introductions demonstrate that output density and integration safety are improving faster than many legacy assumptions would suggest. A notable example is the launch of a next-generation contracting HASEL electrohydraulic actuator family, which delivers more than double the mechanical output of prior versions, uses a fully encapsulated design to simplify safer integration, and benefits from improved material-science manufacturing techniques. Alongside such advances, compact four-in-one designs with high ingress protection ratings are extending deployment into underwater, heavy-lifting, and extreme-environment applications. These innovations compress the traditional trade-off between force density and system simplicity, enabling electrohydraulic solutions to compete in segments that previously favored purely mechanical or centralized hydraulic systems.
The practical implication is clear: capability expansion is opening new application windows. Robotics, automation, and dexterous manipulation are exploring muscle-like electrohydraulic elements, while heavy industrial users are evaluating self-contained actuators that reduce piping, fluid handling, and maintenance overhead. Suppliers that can translate laboratory-stage improvements into field-validated reliability will capture early-mover advantage in emerging sub-segments.
Policy and Regulatory Environment
Regulation is actively reshaping specification criteria. Functional safety certification has become a deciding factor for safety-critical industrial valve applications, where failure modes carry direct operational and environmental consequences. Actuators designed with SIL 3 functional safety certification are increasingly favored in environments where modulating control and on/off operations must meet rigorous reliability thresholds. At the same time, macro-level energy-efficiency mandates are pushing adoption of electrohydraulic systems that can deliver 25 to 30 percent higher efficiency than conventional hydraulic arrangements by cutting energy waste and emissions.
Regulatory trends also influence power-architecture choices. Certain advanced electrohydraulic technologies require high-voltage DC inputs and are controlled via specific analog voltage signals to ensure safe operation. While these requirements raise engineering and integration complexity, they also create differentiation opportunities for providers that can supply compatible control hardware, documentation, and integration support. For industrial buyers, compliance is no longer a checkbox; it is a selection criterion that can narrow the supplier field quickly.
Demand-Side Shifts in End-Use Behavior
End users are re-evaluating actuation strategies through a total-cost-of-ownership lens. In power generation and oil and gas, where uptime and safety are paramount, operators are favoring actuators that combine precise modulating control with robust protection against environmental stress. In industrial automation, the push toward decentralized, self-contained actuation is reducing dependence on central hydraulic power units and long fluid-conduit networks. This shift simplifies plant layouts, lowers leak risks, and supports modular expansion.
Automotive-related applications, while smaller in absolute terms, contribute to broader expectations around compactness, responsiveness, and integration with electronic control architectures. Across sectors, the common thread is a preference for actuators that can be specified, installed, and maintained with fewer system-level compromises. Demand is increasingly shaped by engineering teams that need to balance force requirements, spatial constraints, safety certification, and energy consumption within a single solution.
Supply-Side and Cost-Structure Dynamics
Cost structures are being recalibrated by material choices, repairability, and manufacturing maturity. Suppliers that employ continuously welded steel cases with fully replaceable components are better positioned for harsh mining and refinery environments, where service access and part longevity directly affect operating economics. At the same time, improved material-science manufacturing and encapsulation techniques are reducing failure modes tied to sealing degradation and environmental exposure. These advances lower the hidden costs of maintenance and unscheduled downtime, which often outweigh initial procurement savings.
Supply-chain considerations also matter. As end users expand deployments across multiple sites and geographies, they increasingly favor suppliers that can provide consistent quality, documented lifecycle support, and repairable architectures. The ability to standardize on platforms with interchangeable parts reduces inventory complexity and shortens repair cycles. In a market where the top five players hold under half of total revenue, there is room for both global integrators and regional specialists to win by aligning cost structures with the operational realities of their target segments.
Competitive Landscape and Leading Strategies
The competitive field blends established motion-control leaders, application-focused specialists, and technology-forward innovators. Each cluster pursues a distinct strategic posture, and understanding these differences is essential for evaluating partnership, sourcing, and investment options.
Premier producers of electrohydraulic servo actuators for industrial, aerospace, and defense motion control occupy the high-performance end of the market. Their differentiation rests on precision linear and rotary systems, rigorous qualification standards, and deep application engineering support. These firms typically compete on reliability, control fidelity, and the ability to meet demanding dynamic requirements where motion accuracy and repeatability are non-negotiable.
Compact electro-hydraulic actuator and hybrid-system suppliers address a different priority: self-contained, high-force linear actuation for industrial and decentralized applications. Their value proposition centers on reducing external hydraulic infrastructure while maintaining force output and controllability. By packaging actuation, fluid handling, and control into compact units, they lower installation complexity and enable point-of-use deployment. This approach is particularly attractive where plant layouts are constrained or where modularity and scalability matter more than centralized hydraulic efficiency.
Specialist manufacturers focused on power stations, refineries, mining, and heavy industrial applications emphasize durability and maintainability. Their actuator designs often feature replaceable parts and robust housing construction suited to abrasive, corrosive, or high-vibration environments. In segments where downtime costs dominate procurement decisions, the ability to repair rather than replace entire units becomes a meaningful commercial advantage. These suppliers also tend to build deep relationships with channel partners and service networks that understand local operating conditions.
Another emerging cluster includes producers of integrated electric-hydraulic linear actuators for heavy-duty lifting, underwater, and extreme-environment applications. Their competitive edge lies in combining high ingress protection, compact form factors, and multi-function integration. By consolidating functions into a single package, they reduce assembly interfaces and simplify specification for environmentally demanding deployments.
On the technology frontier, developers of HASEL electro-hydraulic soft artificial muscles are exploring a different trajectory altogether. Their focus on muscle-like performance for robotics, automation, and dexterous manipulation signals a potential long-term expansion beyond traditional industrial actuation. While these applications are earlier in maturity, they illustrate how electrohydraulic principles can be adapted to soft robotics and precision manipulation, creating optionality for future cross-market growth.
Recent market activity reinforces the importance of performance, safety, and integration. The February 2026 introduction of contracting HASEL electrohydraulic actuators with more than double mechanical output, fully encapsulated design, and improved material-science manufacturing underscores how quickly capability benchmarks are moving. In parallel, functional safety certifications and efficiency-oriented design claims are becoming standard elements of competitive positioning in industrial valve and safety-critical applications.
Several landscape trends are likely to intensify:
- Differentiation by application depth will increase. Companies that invest in segment-specific validation, certification, and service networks will be better positioned than those competing primarily on generic specifications.
- Integration and ecosystem offerings will matter more. End users prefer suppliers that can provide compatible control interfaces, documentation, and support pathways, especially where high-voltage DC operation or analog signal control introduces engineering complexity.
- Repairability and lifecycle economics will become stronger selection criteria. In harsh environments, architectures that enable component replacement and reduce scrap rates align with operational cost goals and sustainability expectations.
- Barrier management will shape consolidation. While the market remains moderately concentrated, larger motion-control platforms may seek to broaden their electrohydraulic portfolios through technology acquisition or partnership, particularly where aerospace, defense, and industrial channels overlap.
Forward Outlook: Trends and Commercial Opportunities
Looking toward 2032, three trends are likely to shape where value is created and captured.
First, efficiency-led specification will broaden adoption. As energy regulations tighten and operating cost sensitivity rises, electrohydraulic actuators that deliver measurable efficiency improvements over traditional hydraulic systems will gain traction across industrial and energy applications. The commercial opportunity lies in quantifying and documenting efficiency gains in real operating conditions, then translating those gains into lifecycle-cost narratives that procurement and engineering teams can use in specification decisions. Suppliers that can supply verified performance data, compatible control solutions, and clear integration guidance will be better placed to convert regulatory momentum into recurring demand.
Second, application-specific platforms will outcompete generic offerings. The diversity of operating environments—from underwater and extreme-temperature settings to safety-critical valve networks and soft robotics experimentation—favors platforms tailored to distinct failure modes, protection requirements, and control architectures. Companies that build validated architectures for targeted segments, supported by replaceable components and robust housing materials, will reduce integration risk and improve customer retention. For investors, the opportunity is in businesses that demonstrate repeatable specification wins within defined end-use pools rather than broad but shallow product lines.
Third, new entrants and technology crossover will reshape sub-segments. Innovations such as high-output contracting electrohydraulic muscles and compact multi-function actuator packages suggest that electrohydraulic principles will continue to migrate into adjacent domains, including automation, manipulation, and specialized lifting. This crossover creates both opportunity and uncertainty. Opportunity arises where proven industrial reliability combines with novel form factors or performance characteristics. Uncertainty stems from the risk that early-stage technologies may face integration, power-supply, or control-compatibility hurdles before achieving scale. Decision-makers should therefore distinguish between near-term commercial adoption in established industrial applications and longer-horizon potential in emerging robotics and automation use cases.
Potential risks and uncertainties deserve equal attention. Regulatory trajectories can shift, altering the pace at which efficiency and safety requirements translate into procurement mandates. Supply-chain disruptions affecting steel housing production, sealing materials, or specialized control electronics may pressure lead times and margins. In addition, the need for high-voltage DC power and specific analog control signals in certain advanced actuator families can constrain deployment where existing infrastructure or in-house expertise is limited. Finally, competitive intensity may increase as larger platforms expand their electrohydraulic offerings, potentially compressing price flexibility in segments with fewer differentiation levers.
Actionable Guidance for Decision-Makers
Strategic responses should be calibrated to role and exposure within the value chain.
For manufacturers and suppliers:
Electric Actuators Market
- Prioritize verified efficiency and functional safety as marketable differentiators. Document efficiency improvements relative to conventional hydraulic systems and secure relevant safety certifications for critical applications. Reliable evidence of performance reduces specification risk for end users and strengthens bidding positions in regulated segments.
- Invest in repairable, environmentally robust architectures for harsh industrial settings. Replaceable components, durable housing materials, and clear service pathways lower total cost of ownership and improve customer retention where maintenance access and uptime are decisive.
- Build application-specific integration support. Where advanced actuator families require high-voltage DC inputs or analog control signaling, provide compatible documentation, validation guidance, and integration assistance. Reducing customer-side engineering burden can be a decisive advantage in complex deployments.
For investors and strategic partners:
- Focus on businesses with segment-specific traction and repeatable specification wins. In a market where the top five suppliers hold less than half of revenue, durable growth often comes from depth in targeted applications rather than broad product breadth alone.
- Evaluate technology crossover potential with discipline. Innovations in output density, encapsulation, and soft-actuation principles can open adjacent markets, but commercial readiness, control compatibility, and power-architecture requirements should be assessed before assuming rapid scaling.
- Monitor consolidation signals and channel strategies. Larger motion-control platforms may seek to strengthen electrohydraulic capabilities, while regional specialists may gain from deep service relationships and local operating knowledge. Both paths can create value, but the economics differ substantially.
For procurement and engineering leaders:
- Evaluate actuators on lifecycle cost, maintainability, safety certification, and efficiency rather than initial price. In safety-critical and maintenance-intensive environments, the cost of downtime and repair often dominates procurement economics.
- Standardize where possible without sacrificing application fit. Selecting platforms with interchangeable parts and consistent integration characteristics can reduce spare-parts complexity and accelerate maintenance, provided the chosen architecture meets environmental and control requirements.
- Validate integration assumptions early. For technologies that require specific power and control architectures, confirm infrastructure readiness and in-house expertise during the specification phase to avoid deployment delays and hidden engineering costs.
The electrohydraulic actuator market is evolving from a mature but narrowly defined niche into a broader, more performance-driven field shaped by efficiency mandates, safety requirements, and application-specific engineering needs. Navigating that transition successfully requires detailed segmentation insight, competitive intelligence, and scenario planning that go beyond top-line growth figures. Comprehensive market research can provide the deeper breakdowns, regional and application-level dynamics, and supplier-level benchmarking needed to translate these trends into concrete sourcing, investment, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Electrohydraulic Actuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Caprolactone Market 2026: Why 3.27% CAGR and Asia Pacific Demand Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Caprolactone Market (2026–2032)
The global caprolactone market has matured into a specialized yet strategically significant segment of the broader specialty chemicals and bioplastics ecosystem. Valued at approximately $208.75 million in 2020, the market expanded to an estimated $244.23 million by 2025, with projections indicating a compound annual growth rate of 3.27 percent through 2032. Reaching roughly $305.62 million by the end of the forecast period, the trajectory reflects steady, moderate expansion rather than explosive growth. This measured pace underscores a market defined by technical specialization, regulatory navigation, and shifting downstream demand across adhesives, coatings, thermoplastic polyurethanes, and biodegradable polymer applications.
The base year of 2025 marks a critical inflection point. The market has moved past its early adoption phase and into a period where supply chain consistency, purity specifications, and regulatory compliance increasingly dictate competitive positioning. Concentration metrics reveal a moderately consolidated landscape, with the top three players accounting for 48.5 percent of total market share and the top five reaching 61.2 percent. Such concentration suggests that established participants control significant portions of capacity and distribution, yet meaningful room remains for differentiated players who can address specific purity requirements, regional supply gaps, or emerging application niches.
Despite the upward revenue trajectory, the industry faces structural tensions that will shape investment decisions and strategic planning over the next several years. Understanding these pressures is essential for executives evaluating exposure to caprolactone-derived materials or considering capacity allocation in adjacent specialty chemical portfolios.
Market Context and Core Challenges
A Moderately Consolidated Specialty Chemical Segment
The caprolactone market operates at the intersection of performance materials and sustainability-driven substitution. Demand is distributed across multiple application tracks, with polycaprolactone production and specialty polymer synthesis representing the largest consumption pools, while thermoplastic polyurethane formulations, adhesives, coatings, and dedicated biodegradable polymer segments absorb the remainder. Regional activity spans mature industrial markets with established formulation infrastructure alongside rapidly expanding manufacturing hubs where capacity additions and export-oriented production are reshaping trade flows.
Concentration in the market reflects the technical barriers to entry. Producing epsilon-caprolactone at commercial scale requires controlled oxidation pathways, careful handling of intermediates, and consistent purity management. Buyers in pharmaceutical-adjacent synthesis, high-performance coatings, or regulated adhesive systems prioritize batch reliability and certified quality, reinforcing the advantage of established producers. At the same time, the presence of multiple regional manufacturers and specialty chemical firms indicates a market that rewards operational execution and customer-specific technical support rather than volume alone.
Key Challenges Shaping Current Decision-Making
Several intersecting challenges define the current operating environment for caprolactone suppliers, buyers, and investors.
- Raw material dependency and process sensitivity. Caprolactone is derived from cyclohexanone through hydrogen peroxide oxidation, a pathway that ties product economics and supply continuity to the availability and pricing of upstream precursors. Fluctuations in feedstock markets, oxidation yield variability, and plant operating reliability can influence margins and delivery consistency, particularly for buyers requiring tight purity tolerances.
- Regulatory complexity across export markets. Manufacturers targeting multiple regions must navigate registration and compliance regimes such as European REACH and Korean K-REACH, alongside customer-specific documentation requirements. Registration status has become a practical competitive factor, affecting market access for new entrants and shaping procurement decisions for buyers who prioritize supply chain transparency and regulatory readiness.
- Demand fragmentation across applications. While polycaprolactone production remains the dominant use case, growth in coatings, adhesives, TPU formulations, and biodegradable polymers is uneven. Different applications impose different purity thresholds, performance specifications, and volume expectations, making it difficult for a single product grade or marketing message to capture broad demand. This fragmentation rewards suppliers that can align capacity, technical support, and distribution with specific application verticals.
These challenges are not insurmountable, but they do require deliberate strategy. The most resilient participants are those treating caprolactone not as a generic intermediate, but as a performance material with application-specific value propositions, regulatory preparedness, and distribution alignment.
Key Drivers Shaping Market Dynamics
Technical Innovation and Purity Differentiation
Purity specifications remain one of the clearest drivers of value creation in this market. The split between standard and higher-purity grades reflects different buyer expectations: industrial-scale polymer production often prioritizes cost efficiency and volume consistency, while specialty synthesis, advanced coatings, and high-performance adhesive formulations demand tighter specifications and more controlled impurity profiles. Over recent periods, producers have emphasized grade differentiation and application-focused technical positioning, enabling them to capture value in segments where performance matters more than unit cost alone.
Recent product and exhibition activity illustrates how manufacturers are using technical presence to anchor demand. Participation in major coatings and polymer events has become a visible channel for signaling grade availability, application flexibility, and formulation support. For example, Ingevity exhibited Capa caprolactone polyols at the European Coatings Show in Frankfurt in March 2025, reinforcing its focus on formulation-sensitive end markets. Around the same timeframe, Hunan Juren Chemical advanced its presence in international forums, and by early 2026 consolidated its positioning in PCL-related materials through continued production growth and trade engagement. These moves reflect a broader pattern: suppliers are competing increasingly on application relevance and technical credibility, not merely on listing a commodity-grade monomer.
Policy, Registration, and Compliance as Market Enablers
Regulatory readiness has shifted from back-office compliance to a frontline competitive consideration. For caprolactone, registration achievements in key export markets directly affect which buyers can source from which suppliers with confidence. Holding European REACH and Korean K-REACH registrations, for instance, reduces procurement friction for formulators and distributors who need documented compliance for their own downstream customers.
This dynamic favors producers that have invested early in registration and documentation, particularly those seeking to serve multi-region demand. It also creates a practical barrier for less-prepared entrants, even where manufacturing capacity might otherwise be available. For buyers, this means supplier selection increasingly includes compliance assurance as a procurement criterion, not just price and lead time. For investors and strategic planners, registration status is a signal of long-term market access, especially in applications that feed into regulated end-use industries.
Demand-Side Evolution Toward Performance and Sustainability
Downstream demand is changing in ways that favor specific caprolactone value propositions. In adhesives and coatings, formulators continue to seek tunable polymer characteristics that balance adhesion, flexibility, and durability, while also accommodating sustainability messaging where feasible. In thermoplastic polyurethane and biodegradable polymer segments, caprolactone-based materials offer properties that align with performance targets and, in some cases, with broader material transition narratives. The commercial appeal lies not in generic substitution, but in targeted performance improvement and material design flexibility.
Distribution choices are adapting accordingly. In June 2025, Ingevity established Jamplast as the exclusive US and Canada distributor for Capa caprolactone products in bioplastics, a move that reflects the importance of regional channel expertise in reaching formulation customers efficiently. Such arrangements can accelerate market penetration by pairing product availability with distributor relationships already embedded in local application ecosystems. For buyers, this suggests a market where sourcing options are becoming more structured and regionally specialized, rather than uniformly global.
Polycaprolactone Market
Supply-Side Adjustments and Capacity Realignment
Capacity and operational adjustments are reshaping how the market balances supply with regional demand. Debottlenecking and targeted production expansion have become practical levers for participants seeking to support growth without undertaking full-scale greenfield projects. Perstorp's debottlenecking of Capa caprolactone derivatives units at Warrington, UK, is an example of optimizing existing assets to serve global demand more effectively. Meanwhile, Hunan Juren Chemical's continued production growth and expansion of sales agency coverage in Japan illustrate how capacity increases can be paired with regional commercial expansion.
These supply-side actions matter because they influence lead times, regional availability, and pricing stability. For procurement teams, capacity reliability can be as important as unit cost, especially when formulation schedules and downstream production planning depend on predictable monomer supply. For competitors, the strategic question is whether to expand broadly or to focus on segments where purity, registration, and application support justify stronger margins.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The caprolactone market features a mix of global specialty chemical firms and regionally focused manufacturers, each leveraging different strengths. Ingevity Corporation has built its position around the Capa brand of caprolactone monomer and derivatives, emphasizing applications in adhesives, coatings, bioplastics, and performance materials. Its recent activities highlight a dual strategy: deepen formulation-market engagement through exhibitions and technical presence, while also optimizing commercial reach through distribution partnerships. At the same time, broader portfolio considerations, including reported business considerations involving its Advanced Polymer Technologies segment in late 2025, indicate that caprolactone assets may be evaluated within larger corporate portfolio strategies, a reminder that specialty chemical assets can move unpredictably when parent companies reassess segment priorities.
Worldwide ¦Ä-Valerolactone Market
Hunan Juren Chemical has emerged as an active Chinese manufacturer with a focus on epsilon-caprolactone, PCL polyols, and biodegradable materials. Its growth trajectory has been supported by capacity expansion, certification achievements including REACH and K-REACH registrations, and increased international trade engagement. Participation in industry events and the establishment of sales agency coverage in Japan reflect a strategy oriented toward widening export reach and reinforcing regional supply relationships. For buyers seeking alternative sourcing or region-specific supply, such positioning can be strategically relevant, especially when paired with compliance documentation.
Large international chemical and specialty material companies, including BASF SE, Solvay SA, Daicel Corporation, and Sigma-Aldrich Corporation, occupy distinct roles. Some participate through integrated monomer and derivative portfolios, while others focus on synthesis-grade supply and specialty applications. Daicel's Placcel caprolactone monomer, for instance, aligns with pharmaceutical-grade and advanced polymer synthesis needs, showcasing how product positioning can be tailored to high-specification segments. Merck KGaA's Sigma-Aldrich brand serves research and industrial formulation channels where small-volume, high-purity supply and technical documentation are critical. These differentiated roles illustrate a market where scale, purity, and application focus define separate competitive lanes.
Perstorp Holding AB has reinforced its specialty chemical identity by optimizing Capa caprolactone derivatives production and supporting global demand through operational improvements. Its approach highlights the value of debottlenecking and incremental capacity enhancement as a practical growth path, especially where the objective is to improve reliability for existing application customers rather than launch completely new product categories.
How the Competitive Landscape Is Evolving
The market is evolving along several concurrent lines. First, application-aligned competition is intensifying. Suppliers are increasingly evaluated by buyers based on formulation fit, registration status, and regional availability rather than generic product listing. This favors firms that can demonstrate consistent grade quality, technical support, and channel reliability in the specific verticals they target.
Second, regional supply dynamics are becoming more pronounced. Differences in registration coverage, distribution partnerships, and capacity location are shaping procurement preferences in North America, Europe, Asia Pacific, and other regions. Buyers in markets with stricter documentation requirements or with strong local formulation ecosystems may prefer suppliers that have both compliance readiness and appropriate channel access.
Third, portfolio and asset realignment introduces uncertainty and opportunity. The possibility of segment sales, restructuring, or broader corporate portfolio changes can alter supply relationships quickly. While such developments can create supply continuity considerations for some buyers, they can also open pathways for new commercial structures, distribution partnerships, or capacity acquisitions by competitors seeking to strengthen their position.
Overall, the landscape is not moving toward pure price competition. Instead, it is becoming more segmented, with winners differentiating through purity grades, application focus, compliance documentation, and regional supply reliability. For market participants, the practical implication is that positioning must be deliberate: broad exposure without clear application alignment tends to dilute advantage in a market where specifications and compliance matter.
Forward Outlook: Trends and Opportunities for 2026–2032
Trend One: Application-Specific Value Creation Will Outpace Generic Volume Play
Over the next three to five years, the most durable growth will likely come from segments where caprolactone provides clear functional advantages rather than from undifferentiated volume expansion. Formulators in adhesives, coatings, and TPU-related applications will continue to seek materials that offer tunable properties, process compatibility, and reliable performance. Where caprolactone grades can be positioned as enabling ingredients rather than commodity inputs, pricing power and customer stickiness improve.
Commercial opportunity lies in aligning product grades, technical documentation, and distributor relationships with those application priorities. Suppliers and buyers alike benefit when specifications are matched closely to end-use requirements, reducing reformulation risk and improving supply predictability.
Trend Two: Regulatory Readiness Will Become a Procurement Gatekeeper
As multi-region trade continues and downstream industries face increasing scrutiny around material documentation, registration status and compliance readiness will increasingly function as a gatekeeper for supplier selection. Manufacturers with established REACH and K-REACH coverage, and with transparent documentation practices, will have an easier path into regulated supply chains. This trend is likely to consolidate procurement around suppliers that can reduce compliance risk for their customers.
The opportunity here is twofold. For producers, early investment in registration and documentation can translate into durable market access. For buyers, prioritizing suppliers with demonstrated compliance readiness can lower downstream risk, especially in applications feeding into industries where customer audits and material traceability are routine.
Trend Three: Regional Capacity Realignment Will Shape Supply Security
Capacity adjustments, whether through debottlenecking, targeted expansion, or regional sales infrastructure, will influence which suppliers can reliably serve specific geographies. The market is likely to see continued emphasis on optimizing existing assets and strengthening regional channels rather than relying solely on large-scale new capacity additions. This dynamic favors participants that can combine operational flexibility with localized commercial presence.
For procurement and supply chain teams, the practical takeaway is to evaluate regional availability, lead-time reliability, and channel structure alongside price. For investors and strategists, capacity moves should be interpreted in the context of application focus and regulatory readiness, not merely as volume indicators.
Uncertainties Worth Monitoring
Several factors could alter the trajectory. Shifts in upstream feedstock markets and oxidation process economics may affect cost structures and margin resilience. Portfolio decisions by larger chemical companies could redirect caprolactone assets or change supply relationships unexpectedly. Demand growth in biodegradable polymers and related segments may evolve at different speeds depending on formulation adoption, end-market acceptance, and the pace of sustainability-driven substitution. Finally, regional compliance requirements and trade dynamics can change procurement preferences faster than capacity can be rebalanced, particularly in markets where documentation and channel access determine practical availability.
These uncertainties do not imply downside inevitability. Rather, they highlight the need for scenario-aware planning. Companies that monitor feedstock sensitivity, registration status, distribution alignment, and application demand together will be better positioned to anticipate shifts rather than react to them.
PW Consulting
Strategic Actions for Decision-Makers
For Manufacturers and Formulators
Alignment between grade strategy and application demand should be a priority. Evaluate whether current product specifications match the purity, documentation, and performance needs of target segments. Where possible, strengthen technical engagement and distribution partnerships in regions where formulation customers are concentrated. Consider registration and compliance readiness as part of product strategy, especially when serving multi-region customers or regulated downstream industries.
- Map capacity and grade availability against the application segments most likely to grow, rather than assuming uniform demand across all uses.
- Use trade presence and technical demonstrations to reinforce formulation relevance, particularly in coatings, adhesives, and biodegradable polymer channels.
- Monitor potential asset or segment realignment among larger players, since these can affect supply continuity and competitive dynamics quickly.
For Investors and Strategic Planners
Caprolactone should be evaluated as a specialty segment where value is shaped by purity differentiation, compliance readiness, and application alignment rather than by headline volume alone. Due diligence should consider registration status, regional distribution structure, feedstock exposure, and the parent company's broader portfolio strategy. Capacity announcements are useful, but they matter most when paired with clear commercial focus and regulatory preparedness.
- Prioritize targets where technical positioning and compliance documentation support durable customer relationships, not only where capacity is expanding.
- Assess regional supply gaps and channel strength, particularly where local formulation demand is growing and where distributor relationships can accelerate market entry.
- Track corporate portfolio decisions and segment-level asset movements, since these can create acquisition opportunities or supply reassessments.
For Procurement and Sourcing Leaders
Supplier selection should incorporate compliance readiness, regional availability, and application-specific grade consistency alongside cost. Where formulations depend on predictable monomer supply and tight specifications, reliability and documentation can be as strategic as unit price. Diversifying sourcing options across suppliers with different regional strengths may reduce exposure to single-point disruptions or sudden portfolio changes.
- Verify registration and documentation coverage for the regions and applications that matter most to your supply chain.
- Evaluate distributor and channel structures, especially when sourcing in territories where local technical support and logistics affect delivery performance.
- Build contingency awareness around potential asset or segment-level changes among major suppliers, and maintain visibility into alternative qualified sources.
The caprolactone market is entering a phase where disciplined positioning matters more than ever. Moderate but steady growth, application-specific demand, evolving compliance expectations, and ongoing capacity realignment create a landscape that rewards clarity of strategy. For decision-makers seeking deeper segment data, regional breakdowns, and customized scenario planning, comprehensive research coverage can provide the granularity needed to translate these trends into precise commercial action.
For detailed analysis of this topic, please visit the official page: Caprolactone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
X-Ray Flat Panel Detector Market: The Real Drivers Behind Its 5.1% CAGR and $2.5 Billion Growth
By pmarketresearch, 2026-09-21
Navigating the X-Ray Flat Panel Detector Market: Strategic Trends and Commercial Opportunities (2025–2032)
The X-ray flat panel detector market is entering a phase of disciplined expansion, defined by tangible technology maturation, evolving regulatory expectations, and shifting procurement priorities across medical and industrial imaging. Valued at approximately USD 1,800.0 million in 2025 and projected to grow at a 5.1 percent compound annual rate through 2032 to reach USD 2,535.0 million, the sector reflects a structural move away from legacy analog and first-generation digital solutions toward higher-performance, more versatile detector platforms. This growth trajectory is not uniform. It is being reshaped by where innovation is landing, how capital is allocated across regions, and which applications are proving most economically resilient in a tightening cost environment.
For senior decision-makers, the immediate task is to separate signal from noise. The market is large enough to attract new entrants, yet concentrated enough to reward focused differentiation. Understanding where performance thresholds are moving, where regulatory clearance acts as both barrier and accelerator, and how application portfolios are being reevaluated will determine which organizations capture margin rather than merely chase volume.
Market Snapshot: Scale, Structure, and Concentration
Historical data from 2020 through 2025 shows a market that has recovered from early-cycle volatility and built momentum on the back of broader digital radiography adoption and industrial inspection modernization. The 5.1 percent CAGR across the forecast window points to steady, not explosive, expansion. This pace matters because it suggests that growth will increasingly be earned through share shifts, product upgrades, and application-specific wins rather than broad-based demand surges.
Market concentration remains high, with the top three players accounting for roughly 65 percent of revenue and the top five approaching 78 percent. That concentration reflects the cumulative weight of heritage product lines, established service networks, and long-cycle integration into clinical and inspection workflows. At the same time, the absolute size of the addressable market leaves meaningful room for specialists and regional champions, particularly where pricing flexibility, form factor innovation, or application nuance can outweigh scale advantages.
The commercial picture is further defined by device architecture and end-use mix. Amorphous silicon continues to anchor a substantial portion of revenue, benefiting from maturity, production experience, and broad compatibility with existing radiography environments. Amorphous selenium and CMOS-based configurations represent smaller but strategically important slices, each aligning with distinct resolution, dose, and speed requirements. On the application side, medical use cases remain the dominant economic engine, while industrial inspection and other emerging uses contribute a meaningful but smaller share, often carrying different purchasing dynamics, approval pathways, and lifecycle expectations.
Critical Challenges and Inflection Points
The most consequential challenge is the intersection of performance expectations and cost discipline. End-users are no longer asking simply whether a detector can capture an image; they are weighing whether a given architecture justifies its price, service burden, and integration complexity relative to incremental gains in image quality, throughput, or portability. This is especially true where facilities are managing capital constraints, where industrial buyers are calibrating inspection frequency against throughput targets, and where portable and wireless configurations are becoming practical alternatives to fixed installations in select workflows.
A second inflection point lies in the widening gap between mature, well-supported product families and newer technologies still working through validation, regulatory, and adoption cycles. The appeal of advanced sensitivity, lower dose, or compact form factors can be compelling, but organizations purchasing into these platforms are balancing upfront capability against long-term reliability, spare-part availability, software support, and integration risk. That balance is increasingly shaping procurement criteria, particularly in environments where downtime carries direct operational or clinical consequences.
A third challenge is the uneven pace of regional and sectoral adoption. Markets with established reimbursement structures, higher capital budgets, and mature service ecosystems tend to move faster on premium configurations. Others favor cost-effective upgrades, retrofits, or application-specific solutions that address a narrower set of needs. This unevenness means that national or global strategies can underperform if they do not account for local procurement behavior, approval pathways, and the practical realities of installation, training, and maintenance.
Key Drivers Reshaping Demand and Competition
Technology Evolution Beyond Specification Benchmarks
The market is being pulled forward less by headline specifications and more by practical usability advances. Detector architectures are converging around clearer trade-offs between sensitivity, spatial resolution, dose efficiency, and mechanical form factor. In parallel, glass-free and lighter-weight detector designs are gaining attention because they directly affect positioning flexibility, patient or object handling, and transport within mobile or multi-room settings. Wireless connectivity and improved battery management are no longer niche conveniences; they are becoming decisive factors for point-of-care mobility and decentralized imaging workflows.
Recent product clearances illustrate how these trends are moving from engineering concepts into market-ready configurations. A large-sized wireless detector achieving regulatory clearance for broad X-ray applications reflects growing confidence in portable and flexible deployment models. Another wireless and wired detector cleared for stationary systems signals that manufacturers are expanding options across both fixed and mobile environments rather than forcing a single deployment philosophy. In parallel, expanded detector portfolios spanning multiple sensor technologies for both inspection and medical use point toward a deliberate push to serve adjacent applications with platform-level flexibility, rather than treating each use case as an isolated product line.
For manufacturers, the strategic implication is that differentiation is shifting from “can it detect” to “how well does it fit the workflow.” Weight, cable management, recalibration burden, software interoperability, and ease of cleaning or repositioning are increasingly part of the purchasing conversation. Companies that can package performance advances in deployable, serviceable, and intuitive configurations are better positioned to convert technical advantage into commercial advantage.
PW Consulting
Regulatory and Policy Environment as Both Gate and Accelerator
Regulatory clearance is a decisive commercial event in this market. Approval pathways shape not only whether a product can be sold in a given geography, but also how quickly hospital groups, imaging centers, and industrial customers can standardize on a platform. The recent wave of clearances for large-format and wireless detectors indicates that regulators are accommodating newer deployment models, which in turn expands the practical field of play for manufacturers and buyers alike.
At the same time, regulatory expectations around documentation, quality systems, and post-market support raise the bar for smaller entrants and new product introductions. This does not necessarily slow innovation; it tends to filter it toward organizations that can sustain validation, traceability, and field support over time. For buyers, the practical takeaway is that clearance timing and the scope of cleared indications matter as much as performance claims. A detector that clears a relevant use case faster can capture early adoption cycles, while a technically similar product arriving later may have to compete on price, integration, or service terms rather than first-mover visibility.
Demand-Side Shifts in Medical and Industrial Workflows
Demand is being shaped by a pragmatic reevaluation of where detectors create the most value. In medical settings, the emphasis is increasingly on throughput, flexibility, and the ability to support varied imaging scenarios without sacrificing image quality. Portable and wireless configurations are especially relevant where patient movement, room turnover, and bedside or field imaging are part of the operational routine. Purchasers are also more attentive to total cost of ownership, which includes service intervals, replacement part availability, and compatibility with existing system software and archiving workflows.
Flat Panel X Ray Detectors Market
In industrial applications, the driver set is more fragmented but no less real. Inspection needs vary by material, geometry, throughput, and defect sensitivity, and buyers are increasingly looking for detector solutions that can be reconfigured or deployed across multiple inspection tasks without excessive retooling or retraining. In this context, versatility and durability can be as commercially important as peak imaging performance. Detector portfolios that span medical and industrial use cases can benefit from shared engineering investment, but they must still meet the distinct reliability and environmental expectations of each sector.
A broader demand-side trend is the growing preference for solutions that reduce friction in installation and daily operation. Simpler setup, clearer user interfaces, and more predictable maintenance schedules help organizations manage staffing constraints and operational variability. In practice, this means that a detector’s commercial appeal often depends as much on the surrounding system design and support model as on the sensor itself.
Supply Chain and Cost Structure Dynamics
Cost structures in this market are influenced by component specialization, manufacturing experience, and the economics of scaling particular detector architectures. Mature technologies typically benefit from established process knowledge and broader supply bases, which can support price stability and service readiness. Newer or more specialized sensor approaches can offer performance advantages but may face tighter supply constraints or more complex qualification requirements, especially when they depend on specialized materials, readout designs, or packaging processes.
These dynamics create a practical tension for manufacturers deciding how broadly to invest across technology families. Over-indexing on a single architecture can sharpen focus and reduce complexity, but it can also leave a company exposed if customer requirements shift toward speed, weight, dose, or inspection versatility that another platform addresses more naturally. Conversely, maintaining multiple technology lines can preserve optionality, but it demands disciplined portfolio management to avoid diluting engineering resources and supply reliability.
For purchasers, cost is increasingly evaluated through the lens of deployment and support rather than unit price alone. Shipping, positioning, calibration, integration, training, and service response all contribute to the economic picture. In that environment, a modestly higher upfront cost can be justified if it reduces downtime, simplifies installation, or improves throughput enough to offset the difference over the equipment lifecycle.
Medical X-ray Flat Panel Detector Market
Competitive Landscape: Positioning, Differentiation, and Evolution
Strategic Positioning Among Leading Players
The competitive field includes established imaging and detector specialists, diversified medical technology companies, and focused manufacturers with strong regional or application-specific footprints. What distinguishes leaders is rarely a single product feature; it is the ability to combine detector performance with integration depth, regulatory readiness, and a credible support model.
Companies with heritage in amorphous silicon flat panel detectors have built advantage through long-standing product familiarity, broad compatibility with digital radiography environments, and experience serving high-dose or demanding imaging scenarios. Their positioning tends to emphasize reliability, system-level integration, and the practical maturity that comes from serving large installed bases. For buyers, that maturity can translate into smoother procurement, predictable service expectations, and lower perceived integration risk.
Other leaders have leaned into high-resolution detector technology, often paired with scintillator approaches optimized for digital radiography. Their differentiation frequently centers on image clarity, consistent performance across varied use cases, and product families that span multiple detector sizes or deployment scenarios. Where these companies extend into portable or specialized configurations, they attempt to translate high-resolution heritage into workflow flexibility, which is a meaningful commercial message when mobility is a priority.
Specialist manufacturers often compete by narrowing the focus to particular detector designs, regional markets, or application domains. Their advantage can come from faster adaptation to local procurement preferences, targeted product engineering, and closer responsiveness to specific customer pain points. In some cases, that focus allows them to move more nimbly on form factor innovations, wireless options, or application-tailored configurations. The trade-off is that scale, service breadth, and multi-market reach may be limited relative to larger incumbents.
Differentiation Beyond Sensor Specifications
In practice, differentiation is now multidimensional. It includes mechanical design choices such as glass-free construction and lighter weight, connectivity and battery management for wireless operation, software interoperability with broader imaging or inspection ecosystems, and the structure of service and replacement support. The commercial impact of these factors is significant because they affect day-to-day usability and the long-term cost of ownership.
A detector that is technically competitive but difficult to position, clean, recharge, or service can lose ground to a slightly less ambitious product that fits more cleanly into the operating environment. Similarly, a device that integrates well with existing workstation software, acquisition workflows, and archiving systems can reduce adoption friction in ways that are highly valued by procurement teams and end-users alike. As a result, product launches and clearances are increasingly interpreted through the lens of deployment flexibility as much as raw detection capability.
Market Structure and the Trajectory of Consolidation and Entry
The market’s concentration suggests that scale, installed-base relationships, and full-lifecycle support create meaningful barriers. At the same time, the presence of multiple active players across regions and technology families indicates that differentiation and niche leadership remain viable. Recent product and regulatory activity reflects this dual reality: established players continue to broaden portfolios and address new form factors, while targeted entrants gain traction where they can demonstrate clear workflow fit or application-specific value.
The likely evolution is not a simple rush to consolidation or fragmentation, but a layered competitive structure. Large incumbents will continue to compete on integration, breadth, and support endurance. Specialists will compete on precision, flexibility, and responsiveness in defined segments. New entrants will most likely succeed where they can clear regulatory hurdles efficiently and address a specific deployment need that larger portfolios address less directly. In such a structure, the winners are often those who can articulate a defensible position rather than those who attempt to compete across every dimension simultaneously.
Forward Outlook: Three Strategic Trends for the Next 3–5 Years
1. Mobility and Wireless Deployment Become Commercially Central
As large-format wireless detectors secure regulatory clearance and expand into broader application profiles, mobile and flexible imaging setups are moving from niche convenience toward a mainstream procurement consideration. The commercial opportunity lies in applications where room turnover, bedside imaging, field inspection, or decentralized workflows matter. Manufacturers and system integrators that can make wireless operation reliable, rechargeable, and easy to manage will be better placed to capture demand in hospitals, outpatient environments, and mobile industrial inspection scenarios. The risk is that wireless systems must prove durability and consistent performance over repeated use; otherwise, early enthusiasm can flatten into operational disappointment.
2. Multi-Technology Portfolios and Cross-Application Platforms Gain Value
Companies releasing expanded detector portfolios across multiple sensor types and across medical and industrial uses are signaling a shift toward platform-level flexibility. This matters because it allows engineering investment to serve more than one demand pool, and it gives buyers a clearer path to standardizing on a supplier that can address varied inspection or imaging needs. The opportunity is strongest for organizations that can maintain consistent quality, support, and integration across applications without diluting focus. The uncertainty lies in execution: stretching across technologies and use cases can create complexity in manufacturing, qualification, and service if portfolio strategy is not managed tightly.
3. Procurement Will Favor Total Workflow Value Over Isolated Performance Claims
Over the next few years, purchasing decisions are likely to increasingly weigh deployment practicality, support responsiveness, interoperability, and lifecycle economics alongside detector performance. This trend favors solutions that reduce installation friction, simplify daily operation, and promise predictable maintenance. It also rewards suppliers that can provide clear, credible evidence of reliability and field support, not just laboratory specifications. The downside risk is that without strong service infrastructure or integration support, even technically impressive products can struggle to win recurring adoption, especially in budget-constrained or staffing-sensitive environments.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Developers
Focus differentiation on the intersection of performance and usability. Detector specifications remain important, but the commercial battleground is increasingly whether a solution fits real deployment conditions with acceptable weight, connectivity, calibration burden, and service needs. Portfolio decisions should be made deliberately: either concentrate on a well-supported architecture where scale and maturity can be leveraged, or build a carefully managed multi-technology platform with clear rules for where each sensor type earns its place. In either case, regulatory readiness and post-market support capability should be treated as core strategic assets, not administrative afterthoughts.
For Investors and Capital Allocators
Evaluate opportunities through the lens of deployment fit and support endurance rather than technology novelty alone. The most durable value often lies in products that can enter practical workflows quickly, clear relevant approvals efficiently, and sustain service and replacement availability over time. Pay attention to whether a company’s portfolio strategy is coherent, whether its regional positioning matches local procurement realities, and whether its product roadmap addresses wireless, portability, or application versatility in ways that buyers are actually prioritizing. Technologies that solve a specific workflow problem with credible support tend to outperform broad but uncommitted platform claims.
For Procurement Leaders and System Integrators
Assess total workflow impact before committing to a detector architecture. Weight, cable management, wireless reliability, compatibility with existing software and archiving environments, and the predictability of service and replacement support can matter as much as image quality in day-to-day operations. Where possible, test fit within actual usage conditions rather than relying solely on specification comparisons. Also, consider how a detector choice affects future flexibility: a platform that can span multiple applications or form factors may reduce long-term integration complexity, but only if the supplier can deliver consistent support across those scenarios.
The X-ray flat panel detector market is not simply expanding; it is recalibrating around practical performance, regulatory momentum, and workflow-centered value. That creates room for disciplined players to gain share, but it also raises the cost of vague positioning and under-supported innovation. For executives and investors who need segmented growth paths, regional deployment patterns, and customized competitive benchmarking, a more detailed commercial report can provide the finer distinctions that this overview is designed to frame.
For detailed analysis of this topic, please visit the official page: X-ray Flat Panel Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mobile Phone Insurance Ecosystem: How 8.5% CAGR Reshapes a $68B Market
By pmarketresearch, 2026-09-21
The Mobile Phone Insurance Ecosystem: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global mobile phone insurance ecosystem has matured from a peripheral accessory into a core component of the device lifecycle value chain. Over the past five years, the market has expanded steadily, crossing $39 billion in 2025 and projected to reach approximately $68.6 billion by 2032. This trajectory reflects a compound annual growth rate of roughly 8.5%, signaling sustained demand for device protection as smartphones become more expensive, more integral to daily operations, and increasingly vulnerable to a broadening set of risks. The market is now large enough to attract diverse players, from original equipment manufacturers and traditional insurers to specialized protection providers and technology-enabled claim processors.
Despite this growth, the industry sits at a structural inflection point. Three challenges are reshaping how coverage is designed, priced, and delivered.
First, risk aggregation is becoming more volatile. As device ownership cycles lengthen in some segments and accelerate in others, insurers and protection providers must recalibrate exposure models. The rise of refurbished and mid-tier devices, combined with frequent software-driven hardware obsolescence, creates uneven claim patterns that traditional actuarial frameworks struggle to capture.
Second, the boundary between insurance and extended service warranties is blurring. Consumers increasingly expect seamless, subscription-style protection that covers multiple devices and integrates with digital ecosystems. This expectation pressures providers to move beyond event-driven claims toward continuous service models, which demands new pricing logic, customer engagement strategies, and operational capabilities.
Third, regulatory and standardization pressures are gaining traction. Emerging requirements around repairability, data security, and claim transparency are altering eligibility criteria and processing timelines. Providers that rely on legacy underwriting and claims workflows face rising compliance costs and potential coverage gaps, while those that redesign processes around these mandates can convert regulation into a differentiation lever.
Taken together, these forces mean that scale alone no longer guarantees advantage. The market is fragmenting along lines of service integration, claim efficiency, and ecosystem alignment, creating both disruption and opportunity for players that can realign their offerings with the new risk and service paradigm.
Mobile Phone Antenna Market
Key Drivers Reshaping the Market
Technology Innovation and Claim Automation
Technological capability is becoming a primary differentiator in the protection space. AI-driven claim assessment, image-based damage verification, and automated eligibility checks are reducing processing friction and improving consistency. In select markets, insurers are already deploying machine learning models to triage claims, flag fraud indicators, and accelerate approvals for straightforward cases. This shift matters because claim experience is now a core determinant of customer retention and brand trust. Faster, more transparent claims reduce the perceived distance between payment and protection, which in turn supports subscription-style models and multi-device coverage.
Technology is also enabling more granular risk pricing. Device telemetry, usage patterns, and repair history can inform dynamic pricing and personalized coverage tiers. However, this opportunity is constrained by data access, privacy rules, and the need for standardized diagnostic protocols. Providers that can operationalize these inputs without overstepping regulatory boundaries are likely to gain pricing accuracy and customer relevance.
Policy and Regulatory Pressure on Repairability and Coverage Design
Regulatory momentum around device repairability is beginning to reshape insurance economics. Requirements that improve component replacement and standardize repair processes affect claim timelines, eligibility for accidental damage, and the relative cost of repair versus replacement. As repair pathways become more accessible and standardized, insurers and protection providers must reassess when repairs are the preferred outcome and how to price coverage accordingly. This is not merely a compliance issue; it changes the fundamental cost structure of claims and the value proposition offered to consumers and enterprises.
Worldwide Mobile Phone Protective Cases Market
At the same time, broader consumer protection expectations are pushing for clearer coverage terms, faster dispute resolution, and more transparent exclusions. These expectations raise the bar for policy wording and customer communication. Providers that simplify coverage language and align eligibility with realistic repair and replacement pathways are better positioned to reduce disputes and improve net retention.
Demand-Side Shifts Toward Multi-Device and Subscription Protection
Consumer and enterprise behavior is moving toward bundled, subscription-based protection. Rather than purchasing single-device policies at the point of sale, users increasingly prefer coverage that spans multiple devices, renewals automatically, and integrates with digital wallets or account ecosystems. This preference is reinforced by the growing number of connected devices per user and the desire for predictable operating costs. For households and small businesses, a single protection subscription that covers phones, tablets, and adjacent devices reduces administrative friction and improves perceived value.
Enterprise demand is also evolving. Organizations that manage large device fleets are looking for protection models that align with asset management, procurement cycles, and employee experience standards. They want coverage that supports rapid replacement, consistent service levels, and reporting that feeds into broader IT operations. This creates an opening for providers that can package protection with service-level commitments and integration into fleet management workflows.
Supply Chain and Cost Structure Dynamics
Cost structures across the device protection value chain are shifting. Component availability, manufacturing variability, and the growth of certified refurbished devices all influence claim costs and replacement economics. At the same time, logistics for repair and replacement are being reengineered through localized service networks, improved parts availability, and better reverse logistics. Providers that can coordinate repair, replacement, and escalation paths more efficiently will compress loss adjustment expenses and improve turnaround times.
The supply side is also seeing increased interest in partnerships that connect OEMs, carriers, retailers, and insurers. These alliances can distribute coverage at points of high customer intent, share risk information, and standardize service experiences. The strategic value lies not only in distribution reach, but in the ability to align underwriting, claims, and customer support around a unified journey.
Competitive Landscape and Leading Strategies
The competitive field combines technology platforms, established insurers, and specialist protection providers, each pursuing a distinct route to relevance. Apple has extended its protection ecosystem through subscription-style plans that cover multiple device categories, emphasizing digital activation and streamlined claims. This approach reinforces ecosystem loyalty and positions protection as a recurring service rather than a one-time add-on. By bundling coverage across devices, the strategy reduces per-customer friction and creates a more predictable revenue stream tied to the device lifecycle.
Asurion and Assurant continue to play central roles through carrier and retailer partnerships, offering broad coverage that includes accidental damage, theft, and loss. Their strength lies in distribution depth and operational scale across multiple channels. The strategic implication is clear: partnership-led models remain powerful because they meet customers at moments of high purchase intent and leverage existing trust relationships. However, these models increasingly depend on claim efficiency and service consistency to defend retention against more integrated, ecosystem-based offerings.
Allianz and other traditional insurers are exploring AI-enhanced claim processing and broader policy portfolios that position mobile protection within wider personal or enterprise coverage. This route emphasizes underwriting discipline, brand trust, and cross-sell potential. The opportunity is to use mobile protection as an entry point into broader relationships while using automation to improve service economics. The challenge is to maintain agility in a segment where customer expectations for speed and simplicity are rising quickly.
The market is evolving along two parallel tracks. On one side, consolidation and partnership are strengthening incumbent positions by combining distribution, claims infrastructure, and risk management. On the other, differentiation is emerging through service design: multi-device subscriptions, faster digital claims, repair-oriented coverage, and integration with broader device management platforms. New entrants and niche players can gain traction by solving a specific friction point well, such as student segments, SME fleets, or specialized coverage like oxidation or environmental damage, especially when they pair that focus with a compelling service experience.
Future Trends and Commercial Opportunities
Trend 1: From Event-Based Claims to Continuous Protection Services
Over the next three to five years, protection is likely to shift further from reactive claims toward continuous service models. Subscriptions that cover multiple devices, automatic renewals, and integrated digital experiences will become more common, particularly where ecosystems can connect coverage with device registration, diagnostics, and self-service claims. The commercial opportunity lies in building retention through convenience and trust: customers who perceive protection as an always-on service are less likely to churn at renewal and more likely to expand coverage across additional devices. Providers that invest in seamless activation, transparent eligibility, and rapid resolution will be best positioned to capture this value.
Trend 2: Repairability-Driven Coverage Redesign
Regulatory and consumer pressure around repairability will continue to influence coverage design. As repair becomes more standardized and accessible, insurance and protection offerings will need to define clearer repair-versus-replace logic, adjust eligibility for accidental damage, and price accordingly. This creates an opportunity for providers that can coordinate repair networks, parts availability, and claim decisions in a way that reduces cost while preserving customer satisfaction. Coverage that explicitly supports repair pathways can also align with sustainability expectations, which is increasingly relevant for both consumer and enterprise buyers.
Trend 3: AI-Enabled Claims and Risk Selection as a Competitive Moat
AI-assisted claims processing, fraud detection, and risk segmentation will likely become table stakes rather than differentiators, but the quality of implementation will separate leaders from followers. The most valuable applications will combine speed with accuracy: automated triage for simple cases, consistent damage assessment, and better signals for underwriting and pricing. Over time, these capabilities can lower loss adjustment expenses, improve customer experience, and support more personalized coverage. The risk is overengineering without measurable improvement in turnaround or cost; the opportunity is to use automation to make protection feel immediate and dependable.
These trends point to a clear commercial thread: value is shifting toward providers that can integrate coverage, service, and technology into a coherent customer journey. The winners will be those that reduce friction at the moments that matter most—purchase, claim, repair, and renewal—while maintaining disciplined risk management.
Strategic Recommendations for Decision Makers
For Device Manufacturers and Ecosystem Owners
Protection should be treated as part of the device experience, not an afterthought. Aligning coverage with device registration, digital account ecosystems, and multi-device ownership can strengthen loyalty and create recurring revenue tied to the product lifecycle. Manufacturers that make activation simple, claims transparent, and repairs accessible will differentiate more effectively than those that treat insurance as a standalone SKU. It is also important to anticipate repairability mandates and design coverage logic that accommodates repair pathways without eroding economics.
For Investors Evaluating Protection Providers and Adjacent Platforms
Focus on operational leverage and service integration rather than top-line growth alone. The most durable models will combine scalable claims automation, strong partner distribution, and retention-driven subscription dynamics. Watch for providers that can demonstrate consistent turnaround improvements, disciplined loss ratios, and the ability to expand coverage across devices or customer segments without proportionally increasing complexity. Equally important is regulatory readiness: companies that can adapt coverage and claims processes to evolving repairability and transparency requirements will face less disruption and may convert compliance into advantage.
For Carriers, Retailers, and Enterprise Procurement Leaders
Prioritize protection partnerships that reduce customer friction and align with broader service goals. For consumer-facing channels, that means coverage that is easy to understand, quick to activate, and supported by fast claims. For enterprise buyers, it means protection that fits into fleet management, asset tracking, and employee support workflows, with clear service levels and reporting. When evaluating options, assess not just price but the end-to-end experience: activation speed, claim clarity, repair coordination, and renewal simplicity. The best partnerships are those that make protection feel like a reliable extension of the core offering.
PW Consulting
Conclusion
The mobile phone insurance ecosystem is expanding within a market that is both sizable and rapidly reconfiguring. Growth is sustained by higher device value, broader risk expectations, and a shift toward subscription-style, multi-device protection. Yet the most important changes are operational and strategic: claims are becoming more automated, coverage is being redesigned around repairability and transparency, and competition is increasingly decided by service integration rather than distribution alone. Decision makers that act on these shifts—by aligning protection with device ecosystems, investing in claims efficiency, and selecting partnerships that reduce friction—will be better positioned to capture durable value in the next phase of market development.
The dynamics described here reflect the broad contours of a market in transition. For more detailed segmentation, regional intensity patterns, and company-specific strategy benchmarks, the full PW Consulting research report provides a deeper set of data and tailored recommendations for specific business contexts.
For detailed analysis of this topic, please visit the official page: Mobile Phone Insurance Ecosystem Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tea Tree Oil Market: Strategic Shifts and Commercial Opportunities Through 2032
The global tea tree oil market has entered a decisive growth phase, underpinned by structural demand shifts across personal care, household hygiene, and therapeutic applications. Market revenue expanded from approximately USD 490.0 million in 2020 to USD 700.0 million in 2025, with a forecast trajectory climbing toward USD 1.42 billion by 2032. This expansion reflects a compound annual growth rate of 10.6% across the 2026–2032 forecast period, signaling a market that is growing faster than the broader essential oils segment and capturing share from synthetic alternatives. The acceleration is not merely cyclical; it stems from converging forces in consumer preference, regulatory validation, supply chain reconfiguration, and capital deployment by leading producers. For executives and investors, the central question is no longer whether the market will expand, but how value will be captured across a landscape defined by concentration, grade differentiation, and regional specialization.
Understanding the tea tree oil market requires looking beyond headline growth figures. The revenue composition reflects a market that is simultaneously commoditized at one end and highly premiumized at the other, with distinct margin structures, certification requirements, and buyer expectations. Regional dynamics further complicate the picture, as production remains geographically concentrated while consumption patterns diverge across developed and emerging markets. Sustainability credentials, traceability, and supply assurance have transitioned from nice-to-have attributes to baseline procurement requirements. In this context, strategic positioning depends on aligning product grade, sourcing model, certification footprint, and distribution reach with the specific demand clusters that are expanding most rapidly.
Market Dynamics and Structural Challenges
The current market phase is characterized by robust demand pull, but that growth is filtering through a set of operational and regulatory constraints that will determine which players scale profitably. Three structural challenges stand out as defining features of the period ahead.
PW Consulting
Grade Differentiation and Margin Compression Risks
The market is bifurcated between bulk commodity-grade volumes and pharmaceutical-grade material, each serving fundamentally different buyers and pricing dynamics. Commodity-grade supply supports high-volume applications where functional performance and cost efficiency drive purchasing decisions. Pharmaceutical-grade and premium certified volumes command stricter specification controls, traceability requirements, and price premiums, but they also expose producers to higher compliance costs and more exacting buyer scrutiny. The strategic tension lies in managing this dual structure without eroding margin integrity. Producers that cannot sustain specification consistency, batch reliability, and certification upkeep risk being pulled into price competition, while those that over-invest in premium capabilities without securing offtake commitments may face underutilization.
Concentration and Supply Assurance
Production is not evenly distributed, and the market’s concentration profile makes supply assurance a strategic variable rather than a background assumption. A meaningful share of revenue is captured by a limited set of established players, which creates both stability and vulnerability. For buyers, concentration raises questions about continuity of supply during adverse weather, harvest disruptions, or capacity constraints. For producers, it raises the stakes around capacity planning, geographic diversification, and contractual structuring. As demand scales into the next forecast period, supply assurance will increasingly differentiate preferred partners from transactional suppliers.
Regulatory Clarity and Classification Uncertainty
Regulatory development is simultaneously enabling and complicating market expansion. Recent SCCS opinions have affirmed the safe use of tea tree oil as an anti-seborrheic and anti-microbial agent in specific cosmetic product types, reinforcing its positioning in personal care formulations. At the same time, trade concerns have emerged around proposed changes to hazard classification under CLP regulation, with potential implications for import controls and documentation requirements. This dual dynamic creates a market environment where safety endorsement supports demand confidence, while classification scrutiny raises compliance complexity for cross-border trade. Companies that integrate regulatory monitoring into product development and sourcing decisions will be better positioned to avoid formulation disruption and trade friction.
Core Growth Drivers
The market’s expansion is being propelled by four interlocking drivers, each shaping not only volume growth but also the types of products, grades, and supply relationships that will command premium positioning.
Innovation in Extraction, Yield, and Product Development
Technological upgrades across distillation efficiency, biomass utilization, and extraction precision are improving yield quality while reducing processing waste. These advances matter because they directly influence cost structure, specification reliability, and the ability to meet pharmaceutical-grade or certified organic thresholds consistently. Recent capacity upgrades and production optimization initiatives by leading producers illustrate a broader shift toward high-efficiency processing that supports larger volumes without sacrificing purity. From a commercial standpoint, extraction and process innovation create two advantages: they lower the marginal cost of high-specification output and they increase the credibility of premium claims in buyer evaluations. Product-side innovation is equally important. New formulations and application bundles that pair tea tree oil with complementary natural actives are expanding the addressable use cases beyond traditional antiseptic and cleansing roles, creating additional pull from skincare, scalp care, and household hygiene categories.
Policy and Regulatory Tailwinds with Ongoing Watchpoints
Regulatory developments are acting as a demand enabler in personal care by validating functional claims and setting clear use parameters. The confirmation of safe use in defined cosmetic applications supports formulation confidence and reduces uncertainty for ingredient purchasers and brand developers. At the same time, classification and trade notifications introduce a compliance dimension that should be factored into sourcing and market-entry plans. For multinational buyers, the practical implication is that regulatory foresight is now part of supply selection. Suppliers that maintain rigorous documentation, adapt to evolving hazard classification expectations, and provide formulation support will hold an advantage in procurement evaluations. For producers, the opportunity lies in aligning certification, testing, and labeling practices with the markets they intend to serve, rather than treating compliance as a post-production exercise.
Demand-Side Reorientation Toward Natural, Sustainable, and Traceable Inputs
Consumer and enterprise purchasing behavior continues to shift toward ingredients with verifiable provenance, lower environmental footprints, and credible ethical or organic credentials. In personal care, this has translated into stronger demand for organic, regeneratively sourced, and Fair Trade-aligned tea tree oil, particularly in premium skincare and wellness product lines. In household cleaning and hygiene, the driver is slightly different but related: buyers want effective natural antimicrobial alternatives that fit sustainability narratives and ingredient transparency expectations. This demand-side reorientation is not a niche trend; it is reshaping procurement specifications across multiple channels. As a result, traceability, certification, and storytelling around sourcing practices have become commercial assets that influence both pricing power and shelf positioning.
Supply Chain Realignment and Export-Oriented Capacity Building
Supply chain expansion is another defining driver. Several producers have moved to strengthen export-oriented operations, broaden distributor relationships across Europe and Asia, and invest in plantation and harvesting capacity. This matters because regional demand growth is outpacing local supply in key consumption markets, making export logistics, bulk handling, and consistent supply timing strategically important. The broader effect is a market in which capability to serve international buyers reliably, with the right grade mix and documentation, is becoming a differentiator. Suppliers that integrate cultivation, distillation, quality control, and export logistics into a coordinated model are better positioned to capture demand from markets where natural personal care and hygiene adoption is accelerating.
Worldwide Tea Tree Extract Market
Competitive Landscape and Strategic Positioning
The competitive field combines specialists with deep production and certification roots against global brands that leverage brand equity, distribution scale, and formulation ecosystems. Rather than a single competitive model, the market now rewards distinct strategic archetypes.
Leading Players and Their Strategic Anchors
Australian producers remain central to the market’s premium and pharmaceutical-grade supply, with several companies anchoring their positioning around purity, certification, and vertical integration. G.R. Davis Pty Ltd has built its identity around growing, distilling, and refining pure Australian tea tree oil across grades, including pharmaceutical-grade, supported by ISO9001 and CODEX HACCP certifications. This positions the company as a specification-sensitive supplier for buyers that require documented quality systems and consistent batch integrity. Main Camp Natural Extracts Pty Ltd differentiates through scale in plantation ownership and high-efficiency on-site distillation, emphasizing highest-purity output and premium and organic grades. Its strategic anchor is supply depth and processing efficiency, which supports volume reliability and premium positioning simultaneously. Jenbrook Australia Pty Ltd emphasizes certified organic production and supply, aligning with buyers that prioritize organic credentials and clean sourcing narratives. Oribi Oils (Pty) Ltd, based in South Africa, adds a different value proposition by combining pure tea tree oil with lemon-scented variants and a community-focused model supported by organic, Fair Trade, and Regenerative Organic certifications. This illustrates how ethical sourcing and certification can be used not only for compliance but also as market access and premiumization tools. On the brand and distribution side, doTERRA International LLC and Young Living Essential Oils leverage premium essential oil positioning, strong consumer-facing channels, and formulated product ecosystems. Their strength lies in translating ingredient quality into finished-product demand, particularly in skincare, scalp health, and household purification applications. Integria Healthcare Pty Ltd represents the healthcare and wellness integration angle, where tea tree oil is incorporated into broader wellness products rather than sold solely as a raw material input.
Recent Developments as Strategic Signals
Recent activity across the market shows a clear pattern: capital is flowing into capacity, plantation depth, export supply chains, and productization. Capacity upgrades in large-scale steam distillation and high-efficiency biomass boiler systems have strengthened the ability to supply higher volumes of high-purity pharmaceutical-grade material. Plantation expansion and advanced agricultural technologies have reinforced long-term yield stability and raw material control. Dedicated export supply chain expansion toward major distributors in Europe and Asia reflects a deliberate push to capture demand in regions where natural ingredient adoption is rising. Production optimization focused on eco-friendly extraction has improved alignment with sustainability expectations while supporting efficient output. On the brand side, expanded extraction facilities and new organic skincare launches indicate that demand is being pursued not only at the ingredient level but also through finished-product pipelines. The strategic signal is consistent: winners are investing where demand is most durable and where differentiation can be defended through certification, purity, scale, or formulation strength.
Evolution of the Market Structure
The market is likely to evolve along two parallel tracks. In one, consolidation and partnership intensify among producers capable of delivering pharmaceutical-grade assurance, export reliability, and certified sustainability. In the other, segmentation continues between premium branded ecosystems and commodity-driven supply channels. New entrants will find opportunity not by competing head-on across all dimensions, but by specializing: for example, in certified organic supply, traceable community-sourced models, regional distribution partnerships, or application-specific formulations. The most durable advantage will belong to players that can combine grade control, certification credibility, and supply continuity with a clear route to the demand segments they target.
Forward Outlook and Commercial Opportunities
Looking across the 2026–2032 forecast window, three trends are especially consequential for strategy and investment decisions.
Premiumization with Specification Sophistication
Demand for pharmaceutical-grade and certified organic tea tree oil is expected to keep rising, particularly in personal care and wellness applications where formulation integrity and claim support matter. The commercial opportunity lies in building or securing supply that can consistently meet stricter specifications, maintain documentation rigor, and satisfy buyer audit requirements. This is not only a production challenge; it is a commercial one, because premium-grade buyers often value reliability, test data, and traceability as much as price. Suppliers that can operationalize this level of assurance will be able to defend margins even as overall market volume grows.
Regional Demand Diversification and Export Opportunity
Consumption growth is broadening beyond traditional strongholds, with Europe and parts of Asia showing strong pull for natural personal care, household hygiene, and sustainable ingredient narratives. For producers and exporters, the opportunity is to match grade portfolios and logistics capabilities to the specific entry points in these regions, including distributor networks, formulation requirements, and regulatory expectations. For buyers, the opportunity is to secure multi-source supply strategies that reduce concentration risk while preserving access to high-specification material. The markets that grow fastest will reward players that can move reliably across borders with the right documentation and grade alignment.
Functional Expansion Beyond Traditional Use Cases
Tea tree oil is increasingly being embedded into broader skincare, scalp care, air purification, and household hygiene solutions. This functional expansion creates opportunity for combination products, targeted formulations, and usage-specific positioning. The strategic implication is that raw material suppliers and brand developers can capture more value by aligning around application needs rather than selling a single generic input. Formulation expertise, stability data, and compatibility knowledge will become more valuable as tea tree oil appears in more diversified product architectures.
Eucalyptus Oil Market
These opportunities come with watchpoints. Regulatory classification developments, trade notifications, and safety opinions can shift compliance requirements and import conditions. Supply concentration means that weather, crop risk, or capacity constraints can affect availability. Sustainability claims also face rising scrutiny, making credible certification and verifiable sourcing essential rather than optional. Companies that treat these as manageable variables, monitored and incorporated into planning, will be better placed to benefit from growth without being disrupted by it.
Actionable Implications for Decision-Makers
For manufacturers and brand developers, the priority is to align product portfolios with the grade and certification profiles that buyers increasingly require. That means defining whether the strategy depends on bulk commodity-grade cost efficiency or premium pharmaceutical-grade and certified organic differentiation, and then building sourcing, quality systems, and documentation to match. Formulation teams should also evaluate how tea tree oil can be integrated into broader natural and sustainable product lines in ways that support both performance and claim credibility, especially as regulatory validation continues to shape acceptable use cases.
For investors, the attractive thesis is not simply market growth but the quality of the growth. Capital deployed into capacity that improves yield, purity, and export reliability, or into brands that can convert ingredient demand into finished-product momentum, is better positioned than capital chasing undifferentiated volume. Due diligence should focus on certification integrity, supply chain resilience, regulatory preparedness, and the durability of offtake relationships in target regions. In a market where concentration and grade differentiation matter, operational and compliance capabilities are as important as top-line expansion.
For procurement and supply chain leaders, the strategic move is to reduce dependency on single-source assumptions while preserving access to high-specification material. Multi-source strategies, clear grade requirements, and contractual terms that protect continuity during harvest or capacity cycles will become more valuable as demand scales. Procurement teams should also integrate regulatory monitoring into supplier selection, ensuring that classification, hazard documentation, and import requirements do not become last-minute disruptions. The most resilient sourcing models combine quality assurance, traceability, and geographic or supplier diversity with a clear understanding of the end-use grade needed.
Given the pace of capacity expansion, regulatory evolution, and regional demand shifts, detailed segmentation data, supplier capability assessments, and region-specific forecasts can materially improve strategic timing and resource allocation. The broader market direction is clear, but the specifics of grade mix, regional exposure, certification pathways, and competitive positioning determine where value is actually captured. Decision-makers looking to move from directional awareness to executable planning will benefit from a closer reading of the segment-level dynamics and company-specific developments shaping this market.
For detailed analysis of this topic, please visit the official page: Tea Tree Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aramid Paper Market: Why 6.1% CAGR and Asia Pacific’s Growth Reshape 2032
By pmarketresearch, 2026-09-21
Aramid Paper Market: Strategic Trends and Commercial Opportunities Through 2032
The global aramid paper sector has entered a phase of measured expansion, driven by the material’s irreplaceable role in high-temperature insulation, fire safety, and lightweight structural reinforcement. Valued at approximately USD 587.6 million in 2025, the market is projected to grow at a compound annual growth rate of 6.1% through 2032, reaching an estimated USD 892.4 million. This trajectory reflects a broader industrial shift toward materials that balance thermal stability, dielectric strength, and mechanical durability. Historical growth from 2020 to 2025 has been steady, with annual revenue climbing steadily as electrical grid modernization, aerospace consolidation, and industrial automation have absorbed incremental volume. Yet the path ahead is not linear. Supply chain volatility, evolving regulatory expectations, and shifting competitive dynamics are reshaping how value is created and captured in this niche but strategically critical segment.
For executives and investors tracking high-performance materials, the aramid paper market offers a compelling case study in how specialized polymers navigate industrial cycles. The sector’s resilience stems from its integration into mission-critical applications where substitution is costly and downtime is unacceptable. At the same time, manufacturers and buyers must navigate a landscape where raw material pricing, compliance obligations, and geographic trade flows are increasingly interconnected. The following analysis examines the forces shaping the market, the strategies of leading players, and the strategic decisions that will determine competitive advantage over the next three to five years.
Market Landscape and Core Challenges
The aramid paper market operates within a highly concentrated environment, with the top three firms accounting for over three-quarters of global revenue and the top five collectively commanding more than four-fifths of supply. This concentration reflects the capital intensity of fiber-to-paper conversion, the technical expertise required for grade optimization, and the long qualification cycles inherent in aerospace, electrical, and transportation applications. While consolidation has delivered scale efficiencies and consistent quality control, it also creates structural dependencies that buyers and suppliers must manage carefully.
Key Challenges Shaping the Sector
Three interlocking challenges are redefining how the market evolves. First, feedstock volatility has introduced unpredictability into cost structures. Para-aramid paper production relies heavily on para-phenylenediamine and terephthaloyl chloride, and price movements in these inputs directly affect manufacturing margins and downstream pricing power. Recent quarterly increases of approximately six percent in Chinese spot markets illustrate how supply constraints and aerospace-driven demand can compress margins when producers lack hedging mechanisms or long-term contractual buffers.
Second, regulatory complexity is accelerating. Europe’s Ecodesign for Sustainable Products Regulation, which has been effective since mid-2024, requires digital product passports for aramid paper by 2030 to support traceability and circularity claims. Simultaneously, stricter chemical registration and restriction frameworks are influencing formulation decisions, particularly for meta-aramid grades used in electrical insulation. Fire safety standards across multiple jurisdictions, including UL 94, NFPA 701, and EN 45545-2, continue to mandate rigorous compliance testing for applications in electrical systems and transportation. These requirements increase time-to-market for new grades and raise the barrier for smaller producers who lack robust documentation and testing infrastructure.
Third, trade policy is reshaping regional supply flows. Cumulative tariffs on certain meta-aramid insulation imports have reached levels that alter the economics of cross-border sourcing for North American electrical and aerospace sectors. These measures introduce cost premiums that ripple through procurement decisions, encouraging regionalization, inventory buffering, and alternative supplier qualification. For buyers, the challenge is balancing cost efficiency against supply continuity; for producers, the opportunity lies in localized capacity, differentiated service, and compliance-ready product architectures.
These challenges do not signal instability; rather, they highlight a maturing market where value is increasingly tied to reliability, compliance readiness, and supply chain intelligence. Companies that treat regulation and trade conditions as strategic variables rather than administrative hurdles are better positioned to protect margins and deepen customer relationships.
PW Consulting
Key Drivers of Market Evolution
Technological Innovation and Grade Optimization
Advancements in thermal resistance, dielectric performance, and mechanical consistency are expanding the addressable use cases for aramid paper. Du Pont’s recent portfolio updates, including improved thermal resistance grades for industrial and aerospace applications, demonstrate how incremental material engineering can unlock qualification in higher-temperature environments and more demanding insulation architectures. In parallel, Teijin Aramid’s digital product passport-aligned offerings show how compliance and traceability are becoming embedded into product design rather than treated as after-the-market add-ons.
For manufacturers, the strategic implication is clear: innovation cycles are shortening in areas where performance differentiation directly influences specification decisions. Investing in grade development, process control, and application-specific testing can convert technical advantages into commercial lock-in. For buyers, the opportunity lies in collaborating with suppliers on qualification roadmaps that anticipate future thermal, electrical, and fire-safety requirements before they become constraint-driven mandates.
Policy and Regulatory Environment
Regulatory momentum is a defining force in the aramid paper market. The digital product passport requirement signals a broader push toward supply chain transparency and circular economy accountability. Beyond Europe, fire safety and chemical compliance standards continue to influence product design and approval timelines across electrical insulation and transportation end markets. These frameworks reward producers with robust documentation, consistent batch quality, and clear material traceability, while increasing the cost of non-compliance for any participant that treats certification as a tactical checkpoint.
The commercial impact is twofold. First, compliance capability is becoming a competitive filter, particularly in segments where safety certification and material provenance are inseparable from procurement decisions. Second, regulatory alignment creates opportunities for value-added services such as lifecycle documentation, responsible sourcing verification, and end-of-use guidance. Organizations that integrate compliance into their product strategy can reduce friction in specification approvals and strengthen their position in regulated markets.
Demand-Side Shifts in Electrical, Aerospace, and Industrial Sectors
Demand growth is being shaped by three overlapping trends. Electrical insulation remains the largest application segment, supported by grid modernization, transformer upgrades, and the expansion of high-voltage infrastructure. Aerospace and defense applications continue to absorb aramid paper where weight reduction, thermal stability, and fire resistance must coexist, particularly in composite reinforcement and insulation systems. Meanwhile, industrial and automotive insulation needs are evolving as electrification and automated manufacturing increase the prevalence of high-temperature electrical and mechanical environments.
These demand shifts are not uniform across regions or customer segments. In mature markets, replacement and upgrade cycles drive volume, while in faster-industrializing regions, new infrastructure build-out and localized manufacturing expansion create incremental demand. The commercial takeaway is that aramid paper is increasingly tied to system-level modernization rather than commodity substitution. Buyers evaluating total cost of ownership, reliability, and compliance continuity are more likely to prioritize proven performance over short-term price optimization.
Supply Chain and Cost Structure Dynamics
The cost structure of aramid paper is sensitive to feedstock pricing, regional production footprints, and logistics complexity. Para-aramid feedstocks remain the primary cost driver, and recent spot price movements highlight how supply constraints and application-specific demand can interact to create quarterly volatility. At the same time, the presence of regional producers serving Asia-Pacific and Southeast Asian markets has diversified supply options, though often with trade-offs in scale, certification breadth, or grade consistency.
For procurement strategies, this environment rewards multi-source planning and supplier development. Companies that maintain visibility into feedstock trends, qualify alternative grades, and build relationships with converters offering slitting, die-cutting, and custom lamination can reduce exposure to single-point disruptions. For producers, cost competitiveness increasingly depends on process efficiency, grade yield, and service breadth rather than volume alone. In a concentrated market, the ability to deliver consistent quality with flexible formats and compliant documentation is a meaningful differentiator.
Competitive Landscape and Leading Strategies
The competitive structure of the aramid paper market reflects a blend of established multinational producers, regionally focused manufacturers, and specialized converters. E. I. du Pont de Nemours and Company maintains a leading position through its Nomex and Kevlar grades, with a strong footprint in electrical insulation, aerospace composites, and high-temperature applications. Teijin Aramid complements this profile with an integrated fiber-to-paper supply chain and a portfolio encompassing Technora and Twaron grades, serving aerospace, automotive, and electrical insulation markets with an emphasis on end-to-end control. Yantai Tayho Advanced Materials has emerged as a significant producer of meta-aramid paper for electrical insulation and transformer applications, leveraging expanded capacity to serve Asia-Pacific demand. SRO Aramid and Ganzhou Longpont Material Technology contribute additional capacity in the electrical insulation segment, often with a focus on cost-competitive supply to Chinese and Southeast Asian markets. Kolon Industries supplies para-aramid and meta-aramid variants for industrial and automotive insulation applications, while Tokushu Tokai Paper continues to promote its TT-TOKRON grade in transformer and motor insulation markets following its initial launch. Yantai Metastar Special Paper adds further regional supply through its Metastar-branded meta-aramid paper for electrical insulation and transformer use. Pronat Industries rounds out the landscape as a converter and distributor, offering slitting, die-cutting, and custom lamination services that extend the reach of branded aramid paper into tailored formats.
Strategic Positioning and Differentiation
Leading players are differentiating along several axes. Multinational producers emphasize brand recognition, qualification depth, and global service networks, which reduce risk for OEMs and specifiers in aerospace and high-voltage electrical applications. Regional producers compete on capacity availability, localized service, and price positioning, often gaining traction where procurement teams prioritize responsiveness and regional supply continuity. Converters and distributors add value through format flexibility, custom processing, and inventory management, enabling end users to integrate aramid paper into mixed-material assemblies with less friction.
Aramid (Aramid Fiber) Market
A notable strategic shift is the embedding of compliance and traceability into product architecture. Teijin Aramid’s rollout of digital product passport-compliant products aligned with Europe’s Ecodesign for Sustainable Products Regulation illustrates how traceability is moving from a documentation exercise to a product feature. Similarly, Tokushu Tokai Paper’s continued promotion of TT-TOKRON in transformer and motor insulation markets reflects a strategy of sustained market adoption through application focus and specification reinforcement. For buyers, this means that supplier selection increasingly involves evaluating not only grade performance but also documentation readiness, regulatory alignment, and the ability to support lifecycle expectations.
Market Structure Evolution
The market is evolving along three concurrent directions. Consolidation among established producers continues to reinforce scale advantages and qualification moats, particularly in segments where certification cycles are long and switching costs are high. At the same time, regional capacity additions are expanding supply options in Asia-Pacific and adjacent markets, creating a more layered competitive environment where price, service, and compliance readiness interact differently by customer segment. New entrants and converters are also finding niches by offering tailored formats, value-added processing, and specialized documentation support, even as they operate within a market where core fiber supply and grade development remain concentrated.
For strategic planners, the practical implication is that the market is not simply becoming more crowded or more consolidated; it is becoming more segmented by capability. Suppliers that can demonstrate consistent performance, regional responsiveness, and regulatory alignment will capture share in specification-driven applications, while those that compete primarily on price will face pressure where qualification breadth and documentation quality matter. The winners are likely to be those that treat compliance, traceability, and service flexibility as part of the core product proposition.
Future Trends and Commercial Opportunities
Trend One: Compliance and Traceability as Default Requirements
The trajectory toward digital product passports, chemical compliance, and fire-safety certification is unlikely to reverse. By 2030, traceability and circularity documentation will be expected rather than optional in many European-facing supply chains, and similar expectations are likely to influence procurement decisions in other regions as standards propagate. This trend creates commercial opportunities for producers and converters that invest early in documentation infrastructure, responsible sourcing verification, and lifecycle support. For buyers, it enables faster specification approvals and clearer risk management in regulated applications. The risk lies in late movers facing compliance gaps that delay qualification or restrict market access, particularly in segments where safety and material provenance are tightly linked.
Trend Two: Regionalization and Supply Chain Buffering
Tariff effects, feedstock volatility, and the desire for supply continuity are encouraging regional sourcing strategies and inventory buffering. Over the next three to five years, procurement teams are likely to balance global scale with regional resilience, qualifying multiple suppliers and increasing the share of locally supported supply in critical applications. This trend benefits regional producers and converters that can offer responsive service, format flexibility, and localized technical support. It also creates opportunities for producers to differentiate through guaranteed lead times, transparent pricing mechanisms, and application-specific grade libraries. The uncertainty is whether regionalization will remain cost-neutral or impose premiums that reshape competitive positioning across segments.
Trend Three: Higher-Performance Grades in Electrical and Aerospace Applications
Continued investment in thermal resistance, dielectric strength, and mechanical consistency is expected to expand the use of aramid paper in higher-temperature and more demanding insulation architectures. Du Pont’s improved thermal resistance grades and broader application focus signal that performance upgrades can unlock new specification opportunities, especially where system designers must push thermal boundaries without compromising safety. For commercial teams, the opportunity is to align grade development with qualification roadmaps in electrical insulation and aerospace composite systems, reducing the time between material advancement and adoption. The risk is that performance gains must be matched by testing, documentation, and customer qualification capacity, otherwise technical advantages do not translate into commercial share.
Strategic Recommendations for Decision Makers
For Manufacturers and Suppliers
Invest in compliance-ready product architecture and documentation as a core capability rather than a peripheral function. Align grade development with the qualification needs of electrical insulation, aerospace, and industrial applications, and ensure that traceability, fire-safety certification, and chemical compliance are integrated into the product story. Strengthen regional service capability where tariff and feedstock dynamics make responsiveness a competitive lever. For converters, emphasize format flexibility, custom processing, and inventory support to capture value in segments where end users prioritize integration simplicity and supply predictability.
For Investors
Prioritize participants with durable qualification moats, traceable supply chains, and clear exposure to electrical insulation and aerospace demand. Evaluate cost structures with attention to feedstock exposure and regional pricing dynamics, and assess whether a company’s differentiation is sustainable beyond price competition. Opportunities are likely to accrue to firms that can combine scale with compliance readiness and that serve segments where switching costs and certification requirements limit substitution. Monitor regional capacity additions and converter networks, as these can create new value pools even within a concentrated market.
For Procurement and Engineering Leaders
Build multi-source strategies that balance global qualification depth with regional service responsiveness. Qualify alternative grades and formats early, and treat compliance documentation, traceability, and lead-time reliability as evaluation criteria alongside performance and price. In electrical insulation and transportation applications, align procurement decisions with anticipated regulatory and fire-safety requirements to reduce rework and qualification delays. Where possible, collaborate with suppliers on specification roadmaps that anticipate higher-temperature and higher-dielectric demands before they become constraint-driven.
Electrical Insulation Paper Market
Accessing Deeper Segment Intelligence
The aramid paper market is moving from a phase of steady expansion into a period where compliance, regional supply strategy, and grade performance will determine competitive outcomes. The forces shaping this transition are visible today in feedstock dynamics, regulatory timelines, tariff effects, and the evolving positioning of leading producers and converters. Decision makers who understand these interlocking dynamics can protect margins, reduce qualification friction, and position their organizations for the next cycle of specification growth.
For executives and investors who require deeper segment-level data, detailed application and regional breakdowns, and customized scenario analysis, a comprehensive research report is available that extends these insights with granular market sizing, competitive benchmarking, and tailored strategic recommendations. The full report provides the context needed to translate market-wide trends into operational and investment decisions across specific segments and geographies.
For detailed analysis of this topic, please visit the official page: Aramid Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com