

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Brown Sugar Market 2026: Beyond the 7.4% CAGR Growth Trajectory and Strategic Shifts

Strategic Trends and Commercial Opportunities in the Brown Sugar Market
The global brown sugar market demonstrates a trajectory of steady, quality-driven expansion as the industry transitions from a commoditized sweetener segment into a differentiated value category. In 2025, the market reached an estimated 2.39 billion USD in revenue, reflecting compounded growth from 1.88 billion USD in 2020. Looking ahead through 2032, the sector is projected to expand at a seven-point-four percent compound annual growth rate, crossing the 3.9 billion USD threshold by the end of the forecast window. This growth is not uniform across all categories; it is increasingly shaped by application-specific demand, regional consumption patterns, and a measurable shift toward premium and specialty formats. The market remains structurally fragmented, with the top three participants accounting for roughly twenty-five percent of total revenue and the top five capturing just under twenty-nine percent. Such concentration levels indicate that while scale advantages exist, competitive advantage is increasingly determined by formulation precision, sourcing reliability, and the ability to align product attributes with downstream manufacturing requirements.
Current Landscape and Critical Inflection Points
The brown sugar market sits at a notable intersection where volume growth, functional utility, and premiumization intersect. Historical volatility during the early part of the decade stabilized into a more predictable expansion curve, but that pattern is now being tested by a combination of supply-side constraints and demand-side recalibration. Industry participants are navigating an environment where raw material availability, trade policy adjustments, and formulation requirements intersect more frequently than in prior cycles.
Several structural challenges are actively shaping strategic decision-making. First, the sector faces ongoing sensitivity to input cost dynamics and sourcing stability. Sugar production is heavily influenced by seasonal conditions, regional cropping outcomes, and trade mechanism adjustments, all of which introduce variability into cost planning for industrial buyers. This is especially relevant for manufacturers that rely on consistent moisture content, molasses balance, and particle size to maintain product consistency across bakery lines, beverage formulations, and confectionery production.
Second, the market is confronting a divergence between traditional bulk demand and rising expectations for specification-grade, specialty-format products. While staple applications continue to drive baseline consumption, growth is increasingly tied to categories that require precise flavor profiles, clean-label alignment, and traceability. Suppliers that operate primarily in undifferentiated bulk segments are finding it harder to protect margins, whereas those capable of delivering consistent functional attributes and certification-backed positioning are capturing stronger downstream preference.
Third, regulatory and trade frameworks continue to shape regional accessibility and pricing stability. In major consuming markets, import mechanisms and domestic support arrangements influence the flow of raw and refined inputs, affecting both cost structures and supply planning. Companies that depend on cross-border sourcing must account for quota allocations, suspension agreements, and the periodic recalibration of trade thresholds, all of which can alter short-term availability and long-term procurement strategy.
Key Drivers Shaping Market Evolution
The expansion trajectory of the brown sugar market is not simply a function of population growth or broad sweetener consumption. It is being reshaped by a set of interacting drivers that reward operational precision and market-specific positioning.
One significant driver is the evolution of product formulation and process control. Producers are increasingly differentiating through controlled molasses integration, crystallization techniques, and variant consistency across light and dark formats. This matters because downstream users in bakery, beverage, and confectionery applications depend on predictable color, moisture, and flavor intensity to maintain line efficiency and product quality. Suppliers that invest in tighter specification control and flexible packaging formats are better positioned to serve industrial customers who require repeatability across batches and reduced rework.
A second driver is the alignment of product positioning with consumer-facing expectations around ingredient transparency. Clean-label considerations, non-genetically modified verification, vegan compatibility, and Kosher certification are no longer peripheral claims; they are becoming operational procurement criteria for food manufacturers that must meet retail and foodservice requirements. Offerings that combine domestically grown cane or beet inputs with verified certification structures are gaining traction, particularly in applications where label simplicity and ingredient sourcing are closely scrutinized.
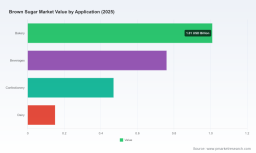
A third driver is the structural shift in application demand. Brown sugar continues to hold relevance in bakery environments, where its moisture contribution and flavor depth support product differentiation in breads, pastries, and specialty doughs. At the same time, beverage and confectionery uses are expanding as formulators seek cost-effective yet distinctively flavored sweetening options. Dairy and adjacent applications remain smaller in relative scale but are becoming more relevant in flavored products and functional blends, where brown sugar’s organoleptic properties can be leveraged without requiring major formulation redesign.
A fourth driver is the interaction between supply-side planning and policy environment. Recent market intelligence from agricultural outlook agencies emphasizes continuing supply and utilization monitoring for U.S. sugar markets based on broader agricultural supply and demand estimates. At the same time, tariff-rate quota allocations for raw sugar are set annually to align with multilateral trade commitments, and domestic support mechanisms operate alongside suspension agreements with Mexico to stabilize input flows. These mechanisms do not merely influence pricing; they shape procurement timing, contract design, and the relative attractiveness of domestic versus imported sourcing strategies.
Taken together, these drivers create a market where competitive advantage is increasingly less about volume alone and more about the ability to deliver specification reliability, certification alignment, and procurement predictability. Companies that treat brown sugar as a functional ingredient rather than a passive sweetener are capturing stronger value capture across industrial and retail channels.
Competitive Landscape and Leading Strategies
The competitive environment in the brown sugar market is characterized by a mix of large diversified sugar producers, regional specialty manufacturers, and brand-focused refiners. No single entity dominates the category, and the moderately fragmented structure creates room for differentiation through crop origin, processing technology, and downstream application focus.
Among the most strategically visible participants, several patterns stand out. One major global food and agriculture company emphasizes a pure cane sugar base combined with molasses, supported by non-GMO verification, vegan-friendly positioning, and Kosher compliance. Its offering is structured to serve bakery, confectionery, sauce, and canned product production, with both bulk and retail packaging options. This model illustrates a broader competitive logic: pairing supply consistency with certification attributes that downstream food manufacturers can use as procurement assurance.
Another leading European producer focuses on crystalline and soft brown sugar produced by crystallizing beet or cane syrups with caramel syrup. Its dual-format approach enables participation across bakery, biscuit, cereal, sauce, and beverage segments, emphasizing formulation versatility. This flexibility is strategically important for industrial buyers that seek one supplier capable of meeting varied processing requirements without sacrificing specification consistency.
Regional processors also play a meaningful role. A U.S.-based beet sugar producer delivers liquid and brown sugars under a well-known regional brand, targeting industrial, commercial, and retail customers. Its relevance lies in localized sourcing and processing capabilities, which can reduce exposure to certain import-related variables and support steady supply for domestic food manufacturers. A major U.S. cane sugar refiner maintains strong brand recognition through established consumer and foodservice labels, while an Oregon-based cooperative and a Hong Kong-based cane sugar producer extend the competitive map across beet-and-cane portfolios and regional export markets.
In Southern Africa, a mill focused on high-quality VHP brown sugar illustrates how regional production can serve both local consumption and export-adjacent demand, particularly where quality consistency and processing standards are key to maintaining market access. Meanwhile, brand-oriented U.S. offerings in light and dark brown sugar continue to reinforce the importance of format clarity and application-specific naming for foodservice and retail buyers.
Across these participants, several strategic themes emerge. First, differentiation is increasingly achieved through a combination of sourcing origin, certification readiness, and format flexibility rather than price competition alone. Second, leading players are investing in the ability to serve industrial customers with reliable batch consistency and packaging options that match processing environments. Third, brand and label equity remains valuable in retail and foodservice channels, where recognition and compliance attributes streamline purchasing decisions.
The market structure also points to ongoing evolution rather than abrupt consolidation. While scale players benefit from procurement leverage and distribution breadth, smaller or regionally anchored producers can compete by specializing in specific formats, crop-based narratives, or application-focused solutions. New entry remains feasible in niche segments where certification, organic positioning, or regenerative agriculture credentials align with buyer requirements, but scaling such offerings typically depends on supply reliability and cost discipline.
Forward Outlook: Key Trends for the Next Three to Five Years
Looking toward the next several years, the brown sugar market is likely to be defined by three interrelated trends.
The first trend is continued premiumization within a still-substantial bulk baseline. Light and dark variants will remain core, but demand growth will increasingly concentrate in specification-managed products that offer predictable flavor intensity, controlled moisture, and certification support. Manufacturers that can standardize these attributes across batches will gain preference in bakery, confectionery, and beverage environments where formulation integrity is critical. This trend favors suppliers that can combine processing precision with transparent documentation and flexible pack sizes.
The second trend is deeper integration between sourcing strategy and regulatory awareness. Because trade mechanisms, quota allocations, and domestic support arrangements influence input availability and cost planning, procurement teams are likely to place greater emphasis on scenario-based sourcing, multi-origin flexibility, and contract structures that reduce exposure to short-term supply shocks. In practical terms, this means brown sugar procurement will become more strategic and less transactional, with buyers evaluating suppliers not only on price but also on reliability under changing trade conditions.
The third trend is the growing relevance of sustainability-linked sourcing narratives where they can be credibly documented and linked to buyer requirements. Organic certification, regenerative agriculture claims, and non-GMO verification are already present in portions of the market, and their commercial importance is likely to increase as food manufacturers seek to align ingredient sourcing with broader label and corporate expectations. The opportunity here is not simply in claims, but in the ability to provide traceable, repeatable sourcing that can withstand procurement scrutiny.
PW Consulting
These trends create tangible commercial opportunities. Suppliers that invest in specification control, certification readiness, and procurement transparency can capture stronger positioning with industrial buyers. Food manufacturers that align product development with brown sugar’s functional profile can use it as a differentiation lever in bakery and beverage portfolios. Investors and strategic planners can focus on the segments where application growth, certification alignment, and supply reliability intersect, rather than assuming uniform growth across all formats and regions.
At the same time, uncertainty remains. Input availability can shift with seasonal outcomes and trade policy adjustments. Certification and labeling requirements may evolve, affecting the cost and feasibility of certain positioning strategies. In addition, any broadening of tariff-rate quota constraints or changes to suspension agreements could alter the relative cost balance between domestic and imported supply in key markets. Companies that build flexibility into sourcing and product planning will be better positioned to navigate these variables.
Strategic Actions for Decision Makers
For manufacturers and brand owners, the priority is to treat brown sugar as a functional, specification-sensitive ingredient. This means aligning procurement with clear technical requirements for moisture, molasses balance, particle characteristics, and certification needs. Where possible, establish supplier relationships that provide batch consistency documentation and flexible packaging options suited to production environments. For product development teams, brown sugar can be used not only as a sweetener but also as a flavor and texture lever in bakery, beverage, and confectionery applications, provided formulation consistency is safeguarded.
For procurement and supply chain leaders, the emphasis should be on resilience and predictability. Evaluate sourcing options against not only unit cost but also supply reliability under changing trade and quota conditions. Consider multi-origin or mixed-format strategies where applicable, and structure contracts to reduce exposure to short-term input volatility. Maintain visibility into regulatory updates that affect import mechanisms and domestic support arrangements, since these can influence both availability and planning horizons.
Sugar Sphere Market
For investors and strategic planners, the opportunity lies in identifying participants and segments that combine scale, specification control, and credible certification or sourcing narratives. The market is large enough to support diverse models, but long-term outperformance is likely to favor those that can deliver consistent quality, serve industrial requirements efficiently, and adapt to evolving buyer expectations around transparency and sourcing. Monitoring application-side uptake, regional supply dynamics, and trade framework adjustments will be essential for anticipating shifts in competitive positioning.
For all of the above, the value of timely, granular intelligence is clear. Market-level projections provide useful direction, but operational decisions depend on detail: segment-by-segment demand patterns, specification preferences, sourcing constraints, certification adoption, and the cadence of regulatory and trade updates. Detailed reporting that breaks down these layers can support more precise planning, from product roadmap design to supplier selection and investment prioritization.
As the brown sugar market continues its transition toward more differentiated, specification-driven growth, the strategic question is no longer whether the category will expand, but how companies will position themselves to capture value within it. Those that combine process discipline, procurement awareness, and clear alignment with downstream application needs are best placed to convert market growth into durable commercial advantage.
Worldwide Brown Rice Market
For detailed analysis of this topic, please visit the official page: Brown Sugar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com