

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Niacin (Vitamin B3) Market: Why Asia Pacific’s 6.65% CAGR Reshapes Global Growth

Strategic Shifts in the Niacin (Vitamin B3) Market: Navigating Growth, Consolidation, and Sustainable Innovation
The global niacin market has solidified its position as a high-growth specialty ingredient segment, driven by expanding applications across nutrition, pharmaceuticals, and personal care. With revenues reaching approximately 676 million USD in 2025 and a projected compound annual growth rate of 6.65 percent through 2032, the market is on a clear upward trajectory. This expansion is not merely a function of population growth or traditional feed demand; it reflects deeper structural changes in how formulators approach metabolic health, skin barrier function, and clean-label supply chains. For executives and investors, the niacin space presents a compelling balance of established demand drivers and emerging differentiation fronts. Understanding where value is created—and where margin pressure or regulatory friction will intensify—requires moving beyond headline figures and examining the interplay of feedstock dynamics, certification barriers, and strategic repositioning by leading suppliers.
Market Snapshot and the Anatomy of Growth
Growth in the niacin market has been steady rather than explosive, with annual revenue climbing from roughly 490 million USD in 2020 to the mid-670 million USD range by 2025. The forward curve points toward a market approaching 1.06 billion USD by 2032, indicating that incremental demand will be supported by both volume expansion and value migration toward higher-specification grades. The trajectory suggests that the next phase of growth will be less about raw volume and more about grade premiumization, application diversification, and regional production realignment.
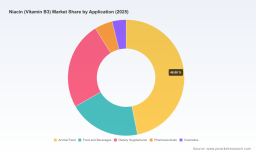
Several structural characteristics define the current market environment. Demand is distributed across multiple end-use channels, with animal nutrition and human nutraceuticals representing the largest demand pools, while personal care and pharmaceutical applications serve as higher-margin, specification-driven niches. On the supply side, synthetic production dominates, reflecting the maturity of chemical synthesis routes and the scalability of established manufacturing hubs. Form factor preferences continue to favor dry formats for bulk handling and feed integration, while liquid variants maintain a differentiated role in formulation flexibility and specific cosmetic or pharmaceutical workflows.
PW Consulting
The market also exhibits a high degree of supplier concentration, with a small group of large-scale producers accounting for the majority of global capacity. This concentration has historically provided pricing stability and supply reliability for bulk grades, but it also concentrates risk around feedstock access, regulatory compliance pathways, and geopolitical exposure. As downstream customers increasingly demand traceability, sustainability credentials, and grade-specific documentation, the competitive frontier is shifting from pure cost leadership to capability-based differentiation.
Key Challenges and Inflection Points
Despite a favorable demand outlook, the niacin market faces several concurrent challenges that will shape investment decisions and sourcing strategies over the next few years.
- Feedstock volatility and petrochemical linkage. The primary precursor for niacinamide synthesis is tightly coupled to petrochemical market cycles. Price oscillations in this feedstock create margin variability for manufacturers and complicate long-term contract planning for buyers. Because a significant share of precursor supply and intermediate processing is concentrated in specific geographic regions, geopolitical disruptions or trade policy shifts can transmit quickly through the value chain.
- Regulatory and certification complexity. Pharmaceutical and nutraceutical grades require rigorous documentation, including pharmacopeial compliance and bioequivalence records at multiple production nodes. Regulatory frameworks across major markets mandate certifications that extend lead times and increase the cost of qualification. For animal feed and food applications, certifications related to quality management, food safety, and religious or dietary compliance have become baseline expectations rather than differentiators.
- Inventory cycles and qualification friction. In high-specification segments, extended lead times are increasingly tied to documentation and approval workflows rather than pure physical production constraints. Buyers in pharmaceutical and personal care channels must manage longer qualification cycles, which affects inventory planning and responsiveness to demand spikes. This dynamic rewards suppliers with integrated quality systems and penalizes those reliant on fragmented compliance processes.
These challenges do not undermine the market outlook; instead, they redefine where competitive advantage is earned. Suppliers that reduce qualification friction, stabilize feedstock exposure, and embed sustainability credentials into their operating models are better positioned to capture premium demand and defend margins.
Worldwide Cosmetic Grade Niacinamide Market
Core Growth Drivers: Innovation, Regulation, Demand, and Supply Chain Realignment
The niacin market is being reshaped by four interlocking drivers that will determine the pace and composition of growth through the late 2020s and into the early 2030s.
Technological Innovation and Specification Premiumization
Innovation in niacin and niacinamide is increasingly oriented around purity, sustainability, and application-specific performance rather than generic volume expansion. Bio-based feedstock approaches are gaining traction as formulators seek to align ingredient sourcing with broader environmental goals and consumer-facing sustainability narratives. In personal care, advanced niacinamide formats are being positioned around skin barrier support, redness reduction, and tolerability, which creates room for premium positioning when supported by robust documentation and stability data.
On the manufacturing side, process optimization and high-purity production capabilities are becoming important differentiators. Suppliers that can deliver consistent pharmaceutical-grade material with minimal batch variability and streamlined certification documentation are capturing share in higher-margin segments. This shift is especially pronounced where downstream brands are under pressure to reduce time-to-market while meeting stringent quality standards.
Policy, Regulation, and Certification as Commercial Gateways
Regulatory expectations are no longer a back-office compliance issue; they are a commercial gateway that shapes market access and supplier selection. Pharmaceutical and nutraceutical channels require pharmacopeial-grade compliance and documentation that supports bioequivalence and traceability. Food and feed channels increasingly treat certifications related to quality systems, food safety, and dietary compliance as standard procurement prerequisites. In practice, certification readiness determines which suppliers can enter tenders, which can scale with key accounts, and which can respond quickly to reformulation requests.
This environment favors scaled producers with established regulatory infrastructure, but it also creates opportunities for specialized manufacturers that can offer targeted grade solutions with faster qualification cycles. For buyers, the implication is clear: supplier selection should weigh not only unit cost but also the speed and reliability of documentation, the breadth of certification coverage, and the supplier’s ability to support regional regulatory variations.
Demand-Side Evolution: Nutrition, Personal Care, and Formulation Trends
Demand is being reshaped by two broad consumer and industry trends. In human nutrition, interest in metabolic health, B-vitamin supplementation, and functional ingredients continues to support steady demand for niacin in dietary supplement formats. In personal care, niacinamide remains a cornerstone ingredient for skin health formulations, and the rise of sensitive-skin positioning, barrier-focused skincare, and clean-label ingredient narratives creates additional demand pull. These channels are not growing at the same rate, but together they diversify the demand base and reduce dependence on any single end-use cycle.
Animal nutrition remains a large demand anchor, particularly where feed fortification and livestock productivity considerations support consistent volume. However, growth in this channel is more cyclical and cost-sensitive than in nutraceuticals or personal care. The differing demand characteristics across channels mean that successful suppliers often need segment-specific commercial models rather than a single one-size-fits-all approach.
Supply Chain Structure and Cost Dynamics
The supply chain for niacin is characterized by concentrated precursor access, regional production hubs, and grade-specific logistics requirements. Feedstock price movements translate directly into cost variability, and because precursor sourcing is exposed to petrochemical cycles and regional supply risks, manufacturers must manage both price and availability simultaneously. The result is that contract structures, inventory positioning, and multi-source strategies matter as much as production capacity.
At the same time, grade differentiation is reshaping logistics and lead times. Pharmaceutical-grade workflows require more rigorous documentation at each production node, which extends qualifying lead times and influences inventory strategy. For buyers, this creates a trade-off between responsiveness and compliance assurance. Suppliers that can compress qualification timelines without compromising documentation integrity will gain commercial leverage, particularly in fast-moving personal care and supplement channels.
Nicotinamide (NAA) (aka Niacinamide) Market
Competitive Landscape: Concentration, Differentiation, and Strategic Realignment
The niacin market is defined by a concentrated group of large-scale producers alongside specialized manufacturers that compete on grade, purity, and application focus. The leading players span chemical synthesis expertise, life sciences orientation, and contract manufacturing capabilities, creating a diversified competitive field in which companies differentiate through distinct value propositions rather than through undifferentiated capacity alone.
Several patterns stand out in the current landscape.
- Large-scale producers anchor bulk and feed demand. Established chemical synthesis capabilities support high-volume supply for animal nutrition, food, and industrial applications. These players compete on scale, reliability, and cost management, while increasingly adding grade-specific offerings to capture higher-margin demand.
- Life sciences and pharmaceutical-focused suppliers emphasize documentation and purity. Companies with strong pharmaceutical-grade infrastructure position around compliance, quality systems, and consistency. Their differentiation lies in the ability to meet rigorous pharmacopeial expectations and support bioequivalence and traceability requirements.
- Specialized and mid-sized manufacturers target niche grades and faster qualification. Some suppliers focus on personal care, supplement, or cosmetic-grade solutions, emphasizing flexibility, application support, and certification breadth. This positioning can be attractive to brands that value responsiveness and tailored technical support.
- Regional production dynamics create both opportunity and risk. With significant manufacturing capacity concentrated in specific regions, supply chain resilience depends on multi-source strategies, regional qualification readiness, and the ability to manage feedstock and logistics exposure.
The competitive field is also evolving through strategic realignment. Recent portfolio moves in the broader nutrition and health ingredients space illustrate how companies are reshaping their exposure to vitamin portfolios and adjacent businesses. Divestitures of animal nutrition and health-related assets by major players reflect a broader trend toward portfolio simplification and focus on higher-value or strategically aligned segments. At the same time, product-level innovation continues to expand the differentiation frontier. The introduction of bio-based niacinamide lines for personal care, combined with visible presence at regional industry events, signals that sustainability and application-specific messaging are becoming central to commercial positioning in cosmetics and skin health.
Taken together, these dynamics suggest a market that will continue to consolidate around capable, well-documented suppliers while also opening space for differentiated players in higher-specification niches. New entrants will face meaningful barriers in pharmaceutical and nutraceutical grades due to certification requirements, but may find more accessible pathways in cosmetic or supplement segments if they can demonstrate quality, consistency, and clear application value.
Looking Ahead: Three Trends Shaping the Next 3–5 Years
Based on current demand patterns, regulatory direction, and supplier behavior, three trends are likely to define the niacin market over the next several years.
Trend 1: Premium-grade migration and application diversification
As downstream brands seek differentiation, demand will increasingly shift toward grades that offer stronger documentation, consistent purity, and specific performance profiles. Pharmaceutical and nutraceutical channels will continue to reward suppliers with robust quality systems, while personal care and supplement segments will place greater emphasis on tolerability, stability, and sustainability narratives. This premium-grade migration creates margin opportunities for suppliers that can support higher specification requirements without sacrificing reliability.
Trend 2: Sustainable sourcing and bio-based differentiation
Sustainability credentials will move from baseline expectations to active commercial differentiators, especially in personal care and consumer-facing nutrition. Bio-based feedstock approaches, traceability improvements, and certifications aligned with dietary and religious requirements will matter more as brands use ingredient sourcing as part of their broader market positioning. Suppliers that can substantiate sustainability claims with verifiable processes and certifications will be better placed to capture preference-driven demand.
Trend 3: Supply chain resilience and qualification speed as core capabilities
Feedstock volatility, regional concentration, and documentation-heavy qualification workflows will make supply chain resilience a central competitive factor. Buyers will increasingly value suppliers that can offer predictable lead times, transparent compliance documentation, and flexible sourcing strategies. The ability to shorten qualification cycles while maintaining regulatory integrity will become a meaningful advantage, particularly for accounts that need to scale quickly or support reformulation programs.
These trends also carry risks. Feedstock price swings can compress margins if not managed through contract design or hedging approaches. Regulatory divergence across regions may increase complexity for globally distributed portfolios. And sustainability claims will face greater scrutiny, meaning that unsubstantiated positioning can create reputational and commercial exposure. The winners will be those who treat resilience, documentation, and credible sustainability as integrated capabilities rather than isolated initiatives.
Strategic Implications for Decision Makers
For executives, planners, and investors, the niacin market offers a mix of stable demand foundations and evolving differentiation opportunities. The strategic question is less whether the market will grow and more how to position for the kind of growth that will arrive.
For manufacturers and suppliers
Focus on grade-specific capability building. Invest in documentation infrastructure, pharmacopeial compliance readiness, and certification breadth that aligns with the channels you intend to serve. If sustainability is part of your positioning, ensure it is backed by verifiable processes and certification coverage that buyers can audit. Consider how feedstock exposure is managed in contracts and inventory planning, because cost variability will remain a persistent margin factor. Where possible, build segment-specific commercial models that match the purchasing logic of feed, supplements, personal care, and pharmaceutical customers rather than applying a single pricing and service model across all channels.
For investors
Evaluate exposure through the lens of grade mix and channel concentration. Businesses with stronger positioning in pharmaceutical, nutraceutical, or premium personal care segments may offer better margin resilience than those dependent primarily on cost-sensitive bulk channels. Pay attention to supply chain structure, regulatory readiness, and the credibility of sustainability claims, since these factors increasingly determine scalability and procurement preference. Also watch portfolio realignment activity across the larger nutrition and health ingredients space, as divestitures and refocusing can reshape competitive dynamics and create both acquisition and partnership opportunities.
For procurement and sourcing leaders
Treat supplier selection as a multi-dimensional decision. Unit price should be weighed against qualification speed, certification coverage, documentation reliability, and supply continuity. For pharmaceutical and supplement-grade procurement, the cost of delayed qualification or compliance gaps can exceed the apparent savings from lower-priced sources. Diversify sourcing where feasible to reduce exposure to feedstock and regional concentration risks, and align inventory strategies with the lead-time realities of higher-specification grades. Request clear evidence of certification status, traceability, and process consistency, especially when sustainability or grade claims are part of the sourcing decision.
Where deeper intelligence adds value
The niacin market is large enough to support multiple successful strategies, but the right strategy depends on segment-specific data that goes beyond aggregate growth figures. Detailed segmentation, regional demand intensity, grade-level margin structures, feedstock cost sensitivities, and competitor-specific capability maps can materially change sourcing, investment, and product roadmap decisions. For teams that need to move from broad market confidence to precise execution planning, deeper segmentation data and tailored competitive assessments provide the granularity required to prioritize capacity, negotiate contracts, and shape formulation strategies with greater confidence.
For detailed analysis of this topic, please visit the official page: Niacin (Vitamin B3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com