

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
X-Ray Flat Panel Detector Market: The Real Drivers Behind Its 5.1% CAGR and $2.5 Billion Growth

Navigating the X-Ray Flat Panel Detector Market: Strategic Trends and Commercial Opportunities (2025–2032)
The X-ray flat panel detector market is entering a phase of disciplined expansion, defined by tangible technology maturation, evolving regulatory expectations, and shifting procurement priorities across medical and industrial imaging. Valued at approximately USD 1,800.0 million in 2025 and projected to grow at a 5.1 percent compound annual rate through 2032 to reach USD 2,535.0 million, the sector reflects a structural move away from legacy analog and first-generation digital solutions toward higher-performance, more versatile detector platforms. This growth trajectory is not uniform. It is being reshaped by where innovation is landing, how capital is allocated across regions, and which applications are proving most economically resilient in a tightening cost environment.
For senior decision-makers, the immediate task is to separate signal from noise. The market is large enough to attract new entrants, yet concentrated enough to reward focused differentiation. Understanding where performance thresholds are moving, where regulatory clearance acts as both barrier and accelerator, and how application portfolios are being reevaluated will determine which organizations capture margin rather than merely chase volume.
Market Snapshot: Scale, Structure, and Concentration
Historical data from 2020 through 2025 shows a market that has recovered from early-cycle volatility and built momentum on the back of broader digital radiography adoption and industrial inspection modernization. The 5.1 percent CAGR across the forecast window points to steady, not explosive, expansion. This pace matters because it suggests that growth will increasingly be earned through share shifts, product upgrades, and application-specific wins rather than broad-based demand surges.
Market concentration remains high, with the top three players accounting for roughly 65 percent of revenue and the top five approaching 78 percent. That concentration reflects the cumulative weight of heritage product lines, established service networks, and long-cycle integration into clinical and inspection workflows. At the same time, the absolute size of the addressable market leaves meaningful room for specialists and regional champions, particularly where pricing flexibility, form factor innovation, or application nuance can outweigh scale advantages.
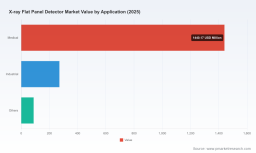
The commercial picture is further defined by device architecture and end-use mix. Amorphous silicon continues to anchor a substantial portion of revenue, benefiting from maturity, production experience, and broad compatibility with existing radiography environments. Amorphous selenium and CMOS-based configurations represent smaller but strategically important slices, each aligning with distinct resolution, dose, and speed requirements. On the application side, medical use cases remain the dominant economic engine, while industrial inspection and other emerging uses contribute a meaningful but smaller share, often carrying different purchasing dynamics, approval pathways, and lifecycle expectations.
Critical Challenges and Inflection Points
The most consequential challenge is the intersection of performance expectations and cost discipline. End-users are no longer asking simply whether a detector can capture an image; they are weighing whether a given architecture justifies its price, service burden, and integration complexity relative to incremental gains in image quality, throughput, or portability. This is especially true where facilities are managing capital constraints, where industrial buyers are calibrating inspection frequency against throughput targets, and where portable and wireless configurations are becoming practical alternatives to fixed installations in select workflows.
A second inflection point lies in the widening gap between mature, well-supported product families and newer technologies still working through validation, regulatory, and adoption cycles. The appeal of advanced sensitivity, lower dose, or compact form factors can be compelling, but organizations purchasing into these platforms are balancing upfront capability against long-term reliability, spare-part availability, software support, and integration risk. That balance is increasingly shaping procurement criteria, particularly in environments where downtime carries direct operational or clinical consequences.
A third challenge is the uneven pace of regional and sectoral adoption. Markets with established reimbursement structures, higher capital budgets, and mature service ecosystems tend to move faster on premium configurations. Others favor cost-effective upgrades, retrofits, or application-specific solutions that address a narrower set of needs. This unevenness means that national or global strategies can underperform if they do not account for local procurement behavior, approval pathways, and the practical realities of installation, training, and maintenance.
Key Drivers Reshaping Demand and Competition
Technology Evolution Beyond Specification Benchmarks
The market is being pulled forward less by headline specifications and more by practical usability advances. Detector architectures are converging around clearer trade-offs between sensitivity, spatial resolution, dose efficiency, and mechanical form factor. In parallel, glass-free and lighter-weight detector designs are gaining attention because they directly affect positioning flexibility, patient or object handling, and transport within mobile or multi-room settings. Wireless connectivity and improved battery management are no longer niche conveniences; they are becoming decisive factors for point-of-care mobility and decentralized imaging workflows.
Recent product clearances illustrate how these trends are moving from engineering concepts into market-ready configurations. A large-sized wireless detector achieving regulatory clearance for broad X-ray applications reflects growing confidence in portable and flexible deployment models. Another wireless and wired detector cleared for stationary systems signals that manufacturers are expanding options across both fixed and mobile environments rather than forcing a single deployment philosophy. In parallel, expanded detector portfolios spanning multiple sensor technologies for both inspection and medical use point toward a deliberate push to serve adjacent applications with platform-level flexibility, rather than treating each use case as an isolated product line.
For manufacturers, the strategic implication is that differentiation is shifting from “can it detect” to “how well does it fit the workflow.” Weight, cable management, recalibration burden, software interoperability, and ease of cleaning or repositioning are increasingly part of the purchasing conversation. Companies that can package performance advances in deployable, serviceable, and intuitive configurations are better positioned to convert technical advantage into commercial advantage.
PW Consulting
Regulatory and Policy Environment as Both Gate and Accelerator
Regulatory clearance is a decisive commercial event in this market. Approval pathways shape not only whether a product can be sold in a given geography, but also how quickly hospital groups, imaging centers, and industrial customers can standardize on a platform. The recent wave of clearances for large-format and wireless detectors indicates that regulators are accommodating newer deployment models, which in turn expands the practical field of play for manufacturers and buyers alike.
At the same time, regulatory expectations around documentation, quality systems, and post-market support raise the bar for smaller entrants and new product introductions. This does not necessarily slow innovation; it tends to filter it toward organizations that can sustain validation, traceability, and field support over time. For buyers, the practical takeaway is that clearance timing and the scope of cleared indications matter as much as performance claims. A detector that clears a relevant use case faster can capture early adoption cycles, while a technically similar product arriving later may have to compete on price, integration, or service terms rather than first-mover visibility.
Demand-Side Shifts in Medical and Industrial Workflows
Demand is being shaped by a pragmatic reevaluation of where detectors create the most value. In medical settings, the emphasis is increasingly on throughput, flexibility, and the ability to support varied imaging scenarios without sacrificing image quality. Portable and wireless configurations are especially relevant where patient movement, room turnover, and bedside or field imaging are part of the operational routine. Purchasers are also more attentive to total cost of ownership, which includes service intervals, replacement part availability, and compatibility with existing system software and archiving workflows.
Flat Panel X Ray Detectors Market
In industrial applications, the driver set is more fragmented but no less real. Inspection needs vary by material, geometry, throughput, and defect sensitivity, and buyers are increasingly looking for detector solutions that can be reconfigured or deployed across multiple inspection tasks without excessive retooling or retraining. In this context, versatility and durability can be as commercially important as peak imaging performance. Detector portfolios that span medical and industrial use cases can benefit from shared engineering investment, but they must still meet the distinct reliability and environmental expectations of each sector.
A broader demand-side trend is the growing preference for solutions that reduce friction in installation and daily operation. Simpler setup, clearer user interfaces, and more predictable maintenance schedules help organizations manage staffing constraints and operational variability. In practice, this means that a detector’s commercial appeal often depends as much on the surrounding system design and support model as on the sensor itself.
Supply Chain and Cost Structure Dynamics
Cost structures in this market are influenced by component specialization, manufacturing experience, and the economics of scaling particular detector architectures. Mature technologies typically benefit from established process knowledge and broader supply bases, which can support price stability and service readiness. Newer or more specialized sensor approaches can offer performance advantages but may face tighter supply constraints or more complex qualification requirements, especially when they depend on specialized materials, readout designs, or packaging processes.
These dynamics create a practical tension for manufacturers deciding how broadly to invest across technology families. Over-indexing on a single architecture can sharpen focus and reduce complexity, but it can also leave a company exposed if customer requirements shift toward speed, weight, dose, or inspection versatility that another platform addresses more naturally. Conversely, maintaining multiple technology lines can preserve optionality, but it demands disciplined portfolio management to avoid diluting engineering resources and supply reliability.
For purchasers, cost is increasingly evaluated through the lens of deployment and support rather than unit price alone. Shipping, positioning, calibration, integration, training, and service response all contribute to the economic picture. In that environment, a modestly higher upfront cost can be justified if it reduces downtime, simplifies installation, or improves throughput enough to offset the difference over the equipment lifecycle.
Medical X-ray Flat Panel Detector Market
Competitive Landscape: Positioning, Differentiation, and Evolution
Strategic Positioning Among Leading Players
The competitive field includes established imaging and detector specialists, diversified medical technology companies, and focused manufacturers with strong regional or application-specific footprints. What distinguishes leaders is rarely a single product feature; it is the ability to combine detector performance with integration depth, regulatory readiness, and a credible support model.
Companies with heritage in amorphous silicon flat panel detectors have built advantage through long-standing product familiarity, broad compatibility with digital radiography environments, and experience serving high-dose or demanding imaging scenarios. Their positioning tends to emphasize reliability, system-level integration, and the practical maturity that comes from serving large installed bases. For buyers, that maturity can translate into smoother procurement, predictable service expectations, and lower perceived integration risk.
Other leaders have leaned into high-resolution detector technology, often paired with scintillator approaches optimized for digital radiography. Their differentiation frequently centers on image clarity, consistent performance across varied use cases, and product families that span multiple detector sizes or deployment scenarios. Where these companies extend into portable or specialized configurations, they attempt to translate high-resolution heritage into workflow flexibility, which is a meaningful commercial message when mobility is a priority.
Specialist manufacturers often compete by narrowing the focus to particular detector designs, regional markets, or application domains. Their advantage can come from faster adaptation to local procurement preferences, targeted product engineering, and closer responsiveness to specific customer pain points. In some cases, that focus allows them to move more nimbly on form factor innovations, wireless options, or application-tailored configurations. The trade-off is that scale, service breadth, and multi-market reach may be limited relative to larger incumbents.
Differentiation Beyond Sensor Specifications
In practice, differentiation is now multidimensional. It includes mechanical design choices such as glass-free construction and lighter weight, connectivity and battery management for wireless operation, software interoperability with broader imaging or inspection ecosystems, and the structure of service and replacement support. The commercial impact of these factors is significant because they affect day-to-day usability and the long-term cost of ownership.
A detector that is technically competitive but difficult to position, clean, recharge, or service can lose ground to a slightly less ambitious product that fits more cleanly into the operating environment. Similarly, a device that integrates well with existing workstation software, acquisition workflows, and archiving systems can reduce adoption friction in ways that are highly valued by procurement teams and end-users alike. As a result, product launches and clearances are increasingly interpreted through the lens of deployment flexibility as much as raw detection capability.
Market Structure and the Trajectory of Consolidation and Entry
The market’s concentration suggests that scale, installed-base relationships, and full-lifecycle support create meaningful barriers. At the same time, the presence of multiple active players across regions and technology families indicates that differentiation and niche leadership remain viable. Recent product and regulatory activity reflects this dual reality: established players continue to broaden portfolios and address new form factors, while targeted entrants gain traction where they can demonstrate clear workflow fit or application-specific value.
The likely evolution is not a simple rush to consolidation or fragmentation, but a layered competitive structure. Large incumbents will continue to compete on integration, breadth, and support endurance. Specialists will compete on precision, flexibility, and responsiveness in defined segments. New entrants will most likely succeed where they can clear regulatory hurdles efficiently and address a specific deployment need that larger portfolios address less directly. In such a structure, the winners are often those who can articulate a defensible position rather than those who attempt to compete across every dimension simultaneously.
Forward Outlook: Three Strategic Trends for the Next 3–5 Years
1. Mobility and Wireless Deployment Become Commercially Central
As large-format wireless detectors secure regulatory clearance and expand into broader application profiles, mobile and flexible imaging setups are moving from niche convenience toward a mainstream procurement consideration. The commercial opportunity lies in applications where room turnover, bedside imaging, field inspection, or decentralized workflows matter. Manufacturers and system integrators that can make wireless operation reliable, rechargeable, and easy to manage will be better placed to capture demand in hospitals, outpatient environments, and mobile industrial inspection scenarios. The risk is that wireless systems must prove durability and consistent performance over repeated use; otherwise, early enthusiasm can flatten into operational disappointment.
2. Multi-Technology Portfolios and Cross-Application Platforms Gain Value
Companies releasing expanded detector portfolios across multiple sensor types and across medical and industrial uses are signaling a shift toward platform-level flexibility. This matters because it allows engineering investment to serve more than one demand pool, and it gives buyers a clearer path to standardizing on a supplier that can address varied inspection or imaging needs. The opportunity is strongest for organizations that can maintain consistent quality, support, and integration across applications without diluting focus. The uncertainty lies in execution: stretching across technologies and use cases can create complexity in manufacturing, qualification, and service if portfolio strategy is not managed tightly.
3. Procurement Will Favor Total Workflow Value Over Isolated Performance Claims
Over the next few years, purchasing decisions are likely to increasingly weigh deployment practicality, support responsiveness, interoperability, and lifecycle economics alongside detector performance. This trend favors solutions that reduce installation friction, simplify daily operation, and promise predictable maintenance. It also rewards suppliers that can provide clear, credible evidence of reliability and field support, not just laboratory specifications. The downside risk is that without strong service infrastructure or integration support, even technically impressive products can struggle to win recurring adoption, especially in budget-constrained or staffing-sensitive environments.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Developers
Focus differentiation on the intersection of performance and usability. Detector specifications remain important, but the commercial battleground is increasingly whether a solution fits real deployment conditions with acceptable weight, connectivity, calibration burden, and service needs. Portfolio decisions should be made deliberately: either concentrate on a well-supported architecture where scale and maturity can be leveraged, or build a carefully managed multi-technology platform with clear rules for where each sensor type earns its place. In either case, regulatory readiness and post-market support capability should be treated as core strategic assets, not administrative afterthoughts.
For Investors and Capital Allocators
Evaluate opportunities through the lens of deployment fit and support endurance rather than technology novelty alone. The most durable value often lies in products that can enter practical workflows quickly, clear relevant approvals efficiently, and sustain service and replacement availability over time. Pay attention to whether a company’s portfolio strategy is coherent, whether its regional positioning matches local procurement realities, and whether its product roadmap addresses wireless, portability, or application versatility in ways that buyers are actually prioritizing. Technologies that solve a specific workflow problem with credible support tend to outperform broad but uncommitted platform claims.
For Procurement Leaders and System Integrators
Assess total workflow impact before committing to a detector architecture. Weight, cable management, wireless reliability, compatibility with existing software and archiving environments, and the predictability of service and replacement support can matter as much as image quality in day-to-day operations. Where possible, test fit within actual usage conditions rather than relying solely on specification comparisons. Also, consider how a detector choice affects future flexibility: a platform that can span multiple applications or form factors may reduce long-term integration complexity, but only if the supplier can deliver consistent support across those scenarios.
The X-ray flat panel detector market is not simply expanding; it is recalibrating around practical performance, regulatory momentum, and workflow-centered value. That creates room for disciplined players to gain share, but it also raises the cost of vague positioning and under-supported innovation. For executives and investors who need segmented growth paths, regional deployment patterns, and customized competitive benchmarking, a more detailed commercial report can provide the finer distinctions that this overview is designed to frame.
For detailed analysis of this topic, please visit the official page: X-ray Flat Panel Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com