

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Aramid Paper Market: Why 6.1% CAGR and Asia Pacific’s Growth Reshape 2032

Aramid Paper Market: Strategic Trends and Commercial Opportunities Through 2032
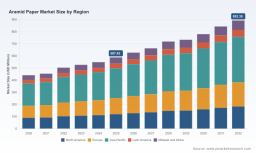
The global aramid paper sector has entered a phase of measured expansion, driven by the material’s irreplaceable role in high-temperature insulation, fire safety, and lightweight structural reinforcement. Valued at approximately USD 587.6 million in 2025, the market is projected to grow at a compound annual growth rate of 6.1% through 2032, reaching an estimated USD 892.4 million. This trajectory reflects a broader industrial shift toward materials that balance thermal stability, dielectric strength, and mechanical durability. Historical growth from 2020 to 2025 has been steady, with annual revenue climbing steadily as electrical grid modernization, aerospace consolidation, and industrial automation have absorbed incremental volume. Yet the path ahead is not linear. Supply chain volatility, evolving regulatory expectations, and shifting competitive dynamics are reshaping how value is created and captured in this niche but strategically critical segment.
For executives and investors tracking high-performance materials, the aramid paper market offers a compelling case study in how specialized polymers navigate industrial cycles. The sector’s resilience stems from its integration into mission-critical applications where substitution is costly and downtime is unacceptable. At the same time, manufacturers and buyers must navigate a landscape where raw material pricing, compliance obligations, and geographic trade flows are increasingly interconnected. The following analysis examines the forces shaping the market, the strategies of leading players, and the strategic decisions that will determine competitive advantage over the next three to five years.
Market Landscape and Core Challenges
The aramid paper market operates within a highly concentrated environment, with the top three firms accounting for over three-quarters of global revenue and the top five collectively commanding more than four-fifths of supply. This concentration reflects the capital intensity of fiber-to-paper conversion, the technical expertise required for grade optimization, and the long qualification cycles inherent in aerospace, electrical, and transportation applications. While consolidation has delivered scale efficiencies and consistent quality control, it also creates structural dependencies that buyers and suppliers must manage carefully.
Key Challenges Shaping the Sector
Three interlocking challenges are redefining how the market evolves. First, feedstock volatility has introduced unpredictability into cost structures. Para-aramid paper production relies heavily on para-phenylenediamine and terephthaloyl chloride, and price movements in these inputs directly affect manufacturing margins and downstream pricing power. Recent quarterly increases of approximately six percent in Chinese spot markets illustrate how supply constraints and aerospace-driven demand can compress margins when producers lack hedging mechanisms or long-term contractual buffers.
Second, regulatory complexity is accelerating. Europe’s Ecodesign for Sustainable Products Regulation, which has been effective since mid-2024, requires digital product passports for aramid paper by 2030 to support traceability and circularity claims. Simultaneously, stricter chemical registration and restriction frameworks are influencing formulation decisions, particularly for meta-aramid grades used in electrical insulation. Fire safety standards across multiple jurisdictions, including UL 94, NFPA 701, and EN 45545-2, continue to mandate rigorous compliance testing for applications in electrical systems and transportation. These requirements increase time-to-market for new grades and raise the barrier for smaller producers who lack robust documentation and testing infrastructure.
Third, trade policy is reshaping regional supply flows. Cumulative tariffs on certain meta-aramid insulation imports have reached levels that alter the economics of cross-border sourcing for North American electrical and aerospace sectors. These measures introduce cost premiums that ripple through procurement decisions, encouraging regionalization, inventory buffering, and alternative supplier qualification. For buyers, the challenge is balancing cost efficiency against supply continuity; for producers, the opportunity lies in localized capacity, differentiated service, and compliance-ready product architectures.
These challenges do not signal instability; rather, they highlight a maturing market where value is increasingly tied to reliability, compliance readiness, and supply chain intelligence. Companies that treat regulation and trade conditions as strategic variables rather than administrative hurdles are better positioned to protect margins and deepen customer relationships.
PW Consulting
Key Drivers of Market Evolution
Technological Innovation and Grade Optimization
Advancements in thermal resistance, dielectric performance, and mechanical consistency are expanding the addressable use cases for aramid paper. Du Pont’s recent portfolio updates, including improved thermal resistance grades for industrial and aerospace applications, demonstrate how incremental material engineering can unlock qualification in higher-temperature environments and more demanding insulation architectures. In parallel, Teijin Aramid’s digital product passport-aligned offerings show how compliance and traceability are becoming embedded into product design rather than treated as after-the-market add-ons.
For manufacturers, the strategic implication is clear: innovation cycles are shortening in areas where performance differentiation directly influences specification decisions. Investing in grade development, process control, and application-specific testing can convert technical advantages into commercial lock-in. For buyers, the opportunity lies in collaborating with suppliers on qualification roadmaps that anticipate future thermal, electrical, and fire-safety requirements before they become constraint-driven mandates.
Policy and Regulatory Environment
Regulatory momentum is a defining force in the aramid paper market. The digital product passport requirement signals a broader push toward supply chain transparency and circular economy accountability. Beyond Europe, fire safety and chemical compliance standards continue to influence product design and approval timelines across electrical insulation and transportation end markets. These frameworks reward producers with robust documentation, consistent batch quality, and clear material traceability, while increasing the cost of non-compliance for any participant that treats certification as a tactical checkpoint.
The commercial impact is twofold. First, compliance capability is becoming a competitive filter, particularly in segments where safety certification and material provenance are inseparable from procurement decisions. Second, regulatory alignment creates opportunities for value-added services such as lifecycle documentation, responsible sourcing verification, and end-of-use guidance. Organizations that integrate compliance into their product strategy can reduce friction in specification approvals and strengthen their position in regulated markets.
Demand-Side Shifts in Electrical, Aerospace, and Industrial Sectors
Demand growth is being shaped by three overlapping trends. Electrical insulation remains the largest application segment, supported by grid modernization, transformer upgrades, and the expansion of high-voltage infrastructure. Aerospace and defense applications continue to absorb aramid paper where weight reduction, thermal stability, and fire resistance must coexist, particularly in composite reinforcement and insulation systems. Meanwhile, industrial and automotive insulation needs are evolving as electrification and automated manufacturing increase the prevalence of high-temperature electrical and mechanical environments.
These demand shifts are not uniform across regions or customer segments. In mature markets, replacement and upgrade cycles drive volume, while in faster-industrializing regions, new infrastructure build-out and localized manufacturing expansion create incremental demand. The commercial takeaway is that aramid paper is increasingly tied to system-level modernization rather than commodity substitution. Buyers evaluating total cost of ownership, reliability, and compliance continuity are more likely to prioritize proven performance over short-term price optimization.
Supply Chain and Cost Structure Dynamics
The cost structure of aramid paper is sensitive to feedstock pricing, regional production footprints, and logistics complexity. Para-aramid feedstocks remain the primary cost driver, and recent spot price movements highlight how supply constraints and application-specific demand can interact to create quarterly volatility. At the same time, the presence of regional producers serving Asia-Pacific and Southeast Asian markets has diversified supply options, though often with trade-offs in scale, certification breadth, or grade consistency.
For procurement strategies, this environment rewards multi-source planning and supplier development. Companies that maintain visibility into feedstock trends, qualify alternative grades, and build relationships with converters offering slitting, die-cutting, and custom lamination can reduce exposure to single-point disruptions. For producers, cost competitiveness increasingly depends on process efficiency, grade yield, and service breadth rather than volume alone. In a concentrated market, the ability to deliver consistent quality with flexible formats and compliant documentation is a meaningful differentiator.
Competitive Landscape and Leading Strategies
The competitive structure of the aramid paper market reflects a blend of established multinational producers, regionally focused manufacturers, and specialized converters. E. I. du Pont de Nemours and Company maintains a leading position through its Nomex and Kevlar grades, with a strong footprint in electrical insulation, aerospace composites, and high-temperature applications. Teijin Aramid complements this profile with an integrated fiber-to-paper supply chain and a portfolio encompassing Technora and Twaron grades, serving aerospace, automotive, and electrical insulation markets with an emphasis on end-to-end control. Yantai Tayho Advanced Materials has emerged as a significant producer of meta-aramid paper for electrical insulation and transformer applications, leveraging expanded capacity to serve Asia-Pacific demand. SRO Aramid and Ganzhou Longpont Material Technology contribute additional capacity in the electrical insulation segment, often with a focus on cost-competitive supply to Chinese and Southeast Asian markets. Kolon Industries supplies para-aramid and meta-aramid variants for industrial and automotive insulation applications, while Tokushu Tokai Paper continues to promote its TT-TOKRON grade in transformer and motor insulation markets following its initial launch. Yantai Metastar Special Paper adds further regional supply through its Metastar-branded meta-aramid paper for electrical insulation and transformer use. Pronat Industries rounds out the landscape as a converter and distributor, offering slitting, die-cutting, and custom lamination services that extend the reach of branded aramid paper into tailored formats.
Strategic Positioning and Differentiation
Leading players are differentiating along several axes. Multinational producers emphasize brand recognition, qualification depth, and global service networks, which reduce risk for OEMs and specifiers in aerospace and high-voltage electrical applications. Regional producers compete on capacity availability, localized service, and price positioning, often gaining traction where procurement teams prioritize responsiveness and regional supply continuity. Converters and distributors add value through format flexibility, custom processing, and inventory management, enabling end users to integrate aramid paper into mixed-material assemblies with less friction.
Aramid (Aramid Fiber) Market
A notable strategic shift is the embedding of compliance and traceability into product architecture. Teijin Aramid’s rollout of digital product passport-compliant products aligned with Europe’s Ecodesign for Sustainable Products Regulation illustrates how traceability is moving from a documentation exercise to a product feature. Similarly, Tokushu Tokai Paper’s continued promotion of TT-TOKRON in transformer and motor insulation markets reflects a strategy of sustained market adoption through application focus and specification reinforcement. For buyers, this means that supplier selection increasingly involves evaluating not only grade performance but also documentation readiness, regulatory alignment, and the ability to support lifecycle expectations.
Market Structure Evolution
The market is evolving along three concurrent directions. Consolidation among established producers continues to reinforce scale advantages and qualification moats, particularly in segments where certification cycles are long and switching costs are high. At the same time, regional capacity additions are expanding supply options in Asia-Pacific and adjacent markets, creating a more layered competitive environment where price, service, and compliance readiness interact differently by customer segment. New entrants and converters are also finding niches by offering tailored formats, value-added processing, and specialized documentation support, even as they operate within a market where core fiber supply and grade development remain concentrated.
For strategic planners, the practical implication is that the market is not simply becoming more crowded or more consolidated; it is becoming more segmented by capability. Suppliers that can demonstrate consistent performance, regional responsiveness, and regulatory alignment will capture share in specification-driven applications, while those that compete primarily on price will face pressure where qualification breadth and documentation quality matter. The winners are likely to be those that treat compliance, traceability, and service flexibility as part of the core product proposition.
Future Trends and Commercial Opportunities
Trend One: Compliance and Traceability as Default Requirements
The trajectory toward digital product passports, chemical compliance, and fire-safety certification is unlikely to reverse. By 2030, traceability and circularity documentation will be expected rather than optional in many European-facing supply chains, and similar expectations are likely to influence procurement decisions in other regions as standards propagate. This trend creates commercial opportunities for producers and converters that invest early in documentation infrastructure, responsible sourcing verification, and lifecycle support. For buyers, it enables faster specification approvals and clearer risk management in regulated applications. The risk lies in late movers facing compliance gaps that delay qualification or restrict market access, particularly in segments where safety and material provenance are tightly linked.
Trend Two: Regionalization and Supply Chain Buffering
Tariff effects, feedstock volatility, and the desire for supply continuity are encouraging regional sourcing strategies and inventory buffering. Over the next three to five years, procurement teams are likely to balance global scale with regional resilience, qualifying multiple suppliers and increasing the share of locally supported supply in critical applications. This trend benefits regional producers and converters that can offer responsive service, format flexibility, and localized technical support. It also creates opportunities for producers to differentiate through guaranteed lead times, transparent pricing mechanisms, and application-specific grade libraries. The uncertainty is whether regionalization will remain cost-neutral or impose premiums that reshape competitive positioning across segments.
Trend Three: Higher-Performance Grades in Electrical and Aerospace Applications
Continued investment in thermal resistance, dielectric strength, and mechanical consistency is expected to expand the use of aramid paper in higher-temperature and more demanding insulation architectures. Du Pont’s improved thermal resistance grades and broader application focus signal that performance upgrades can unlock new specification opportunities, especially where system designers must push thermal boundaries without compromising safety. For commercial teams, the opportunity is to align grade development with qualification roadmaps in electrical insulation and aerospace composite systems, reducing the time between material advancement and adoption. The risk is that performance gains must be matched by testing, documentation, and customer qualification capacity, otherwise technical advantages do not translate into commercial share.
Strategic Recommendations for Decision Makers
For Manufacturers and Suppliers
Invest in compliance-ready product architecture and documentation as a core capability rather than a peripheral function. Align grade development with the qualification needs of electrical insulation, aerospace, and industrial applications, and ensure that traceability, fire-safety certification, and chemical compliance are integrated into the product story. Strengthen regional service capability where tariff and feedstock dynamics make responsiveness a competitive lever. For converters, emphasize format flexibility, custom processing, and inventory support to capture value in segments where end users prioritize integration simplicity and supply predictability.
For Investors
Prioritize participants with durable qualification moats, traceable supply chains, and clear exposure to electrical insulation and aerospace demand. Evaluate cost structures with attention to feedstock exposure and regional pricing dynamics, and assess whether a company’s differentiation is sustainable beyond price competition. Opportunities are likely to accrue to firms that can combine scale with compliance readiness and that serve segments where switching costs and certification requirements limit substitution. Monitor regional capacity additions and converter networks, as these can create new value pools even within a concentrated market.
For Procurement and Engineering Leaders
Build multi-source strategies that balance global qualification depth with regional service responsiveness. Qualify alternative grades and formats early, and treat compliance documentation, traceability, and lead-time reliability as evaluation criteria alongside performance and price. In electrical insulation and transportation applications, align procurement decisions with anticipated regulatory and fire-safety requirements to reduce rework and qualification delays. Where possible, collaborate with suppliers on specification roadmaps that anticipate higher-temperature and higher-dielectric demands before they become constraint-driven.
Electrical Insulation Paper Market
Accessing Deeper Segment Intelligence
The aramid paper market is moving from a phase of steady expansion into a period where compliance, regional supply strategy, and grade performance will determine competitive outcomes. The forces shaping this transition are visible today in feedstock dynamics, regulatory timelines, tariff effects, and the evolving positioning of leading producers and converters. Decision makers who understand these interlocking dynamics can protect margins, reduce qualification friction, and position their organizations for the next cycle of specification growth.
For executives and investors who require deeper segment-level data, detailed application and regional breakdowns, and customized scenario analysis, a comprehensive research report is available that extends these insights with granular market sizing, competitive benchmarking, and tailored strategic recommendations. The full report provides the context needed to translate market-wide trends into operational and investment decisions across specific segments and geographies.
For detailed analysis of this topic, please visit the official page: Aramid Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com