

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electrohydraulic Actuator Market: Why the 6.8% CAGR Reshapes Strategy 2026–2032

The Electrohydraulic Actuator Market: Strategic Trends and Commercial Opportunities Through 2032
The electrohydraulic actuator market has reached a structural inflection point. Valued at approximately 247.0 million USD in 2025, the sector has expanded from 180.0 million USD in 2020, compounding at an estimated 6.8 percent annually through the forecast horizon that extends to 2032. By the end of that period, total market revenue is projected to approach 392.0 million USD. These figures reflect more than steady expansion; they signal a market where demand is being reshaped by technological maturation, regulatory pressure, and shifting application requirements. For executives and investors, the critical question is no longer whether the sector will grow, but where value will concentrate and which capabilities will separate durable players from marginal suppliers.
Electro Hydraulic Servo Valve Market
Market Context and Defining Challenges
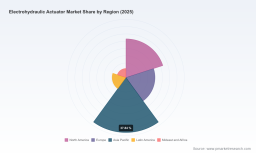
The current landscape is characterized by broad-based adoption across industrial automation, energy infrastructure, and specialized manufacturing. Linear configurations continue to command the larger revenue share, while rotary variants serve niche motion-control requirements where rotational precision and compact form factors are paramount. Applications span heavy industry, power generation, oil and gas infrastructure, and automotive systems, with industrial end-use segments representing the largest demand pool. Geographically, Asia Pacific generates the highest regional revenue, followed by North America and Europe, while Latin America and the Middle East & Africa contribute smaller but growing shares as industrial modernization and energy-sector investments accelerate. The market remains moderately fragmented, with the top three suppliers capturing roughly 32 percent of total revenue and the top five accounting for approximately 42 percent, leaving meaningful space for specialists and regional integrators.
PW Consulting
Despite the positive trajectory, the industry faces several structural challenges that will define competitive outcomes over the next half-decade:
- Efficiency and energy-cost pressures are forcing operators to reconsider traditional hydraulic architectures. Stringent energy-efficiency regulations and rising utility costs are accelerating the shift toward electrohydraulic designs that reduce parasitic losses, minimize idle consumption, and lower emissions footprints. Suppliers that cannot demonstrate measurable efficiency gains risk losing specification decisions to conventional electric or fully hydraulic alternatives.
- Integration complexity and standardization gaps persist across applications. End users increasingly demand plug-and-play reliability, yet electrohydraulic systems still require careful matching of power supply architecture, control logic, sealing integrity, and environmental protection. The absence of universally adopted integration standards creates customization burdens, lengthens validation cycles, and raises total cost of ownership for multi-site deployments.
- Supply-chain resilience and material durability have become decisive procurement criteria. Harsh operating environments—mining sites, refineries, underwater installations, and safety-critical valve networks—expose actuators to corrosion, vibration, and temperature extremes. Components that rely on proprietary, non-repairable assemblies face scrutiny, while designs emphasizing replaceable parts and robust housing materials gain preference in maintenance-intensive settings.
For decision-makers, these challenges are not merely technical obstacles; they are commercial filters. Procurement teams are increasingly evaluating actuators on lifecycle cost, maintainability, functional safety, and energy performance rather than upfront price alone. That shift rewards suppliers who can document reliability, certify safety performance, and offer serviceable architectures.
Core Drivers Reshaping Demand and Supply
Technology Innovation and Performance Breakthroughs
Performance gains are redefining what electrohydraulic actuators can accomplish. Recent product introductions demonstrate that output density and integration safety are improving faster than many legacy assumptions would suggest. A notable example is the launch of a next-generation contracting HASEL electrohydraulic actuator family, which delivers more than double the mechanical output of prior versions, uses a fully encapsulated design to simplify safer integration, and benefits from improved material-science manufacturing techniques. Alongside such advances, compact four-in-one designs with high ingress protection ratings are extending deployment into underwater, heavy-lifting, and extreme-environment applications. These innovations compress the traditional trade-off between force density and system simplicity, enabling electrohydraulic solutions to compete in segments that previously favored purely mechanical or centralized hydraulic systems.
The practical implication is clear: capability expansion is opening new application windows. Robotics, automation, and dexterous manipulation are exploring muscle-like electrohydraulic elements, while heavy industrial users are evaluating self-contained actuators that reduce piping, fluid handling, and maintenance overhead. Suppliers that can translate laboratory-stage improvements into field-validated reliability will capture early-mover advantage in emerging sub-segments.
Policy and Regulatory Environment
Regulation is actively reshaping specification criteria. Functional safety certification has become a deciding factor for safety-critical industrial valve applications, where failure modes carry direct operational and environmental consequences. Actuators designed with SIL 3 functional safety certification are increasingly favored in environments where modulating control and on/off operations must meet rigorous reliability thresholds. At the same time, macro-level energy-efficiency mandates are pushing adoption of electrohydraulic systems that can deliver 25 to 30 percent higher efficiency than conventional hydraulic arrangements by cutting energy waste and emissions.
Regulatory trends also influence power-architecture choices. Certain advanced electrohydraulic technologies require high-voltage DC inputs and are controlled via specific analog voltage signals to ensure safe operation. While these requirements raise engineering and integration complexity, they also create differentiation opportunities for providers that can supply compatible control hardware, documentation, and integration support. For industrial buyers, compliance is no longer a checkbox; it is a selection criterion that can narrow the supplier field quickly.
Demand-Side Shifts in End-Use Behavior
End users are re-evaluating actuation strategies through a total-cost-of-ownership lens. In power generation and oil and gas, where uptime and safety are paramount, operators are favoring actuators that combine precise modulating control with robust protection against environmental stress. In industrial automation, the push toward decentralized, self-contained actuation is reducing dependence on central hydraulic power units and long fluid-conduit networks. This shift simplifies plant layouts, lowers leak risks, and supports modular expansion.
Automotive-related applications, while smaller in absolute terms, contribute to broader expectations around compactness, responsiveness, and integration with electronic control architectures. Across sectors, the common thread is a preference for actuators that can be specified, installed, and maintained with fewer system-level compromises. Demand is increasingly shaped by engineering teams that need to balance force requirements, spatial constraints, safety certification, and energy consumption within a single solution.
Supply-Side and Cost-Structure Dynamics
Cost structures are being recalibrated by material choices, repairability, and manufacturing maturity. Suppliers that employ continuously welded steel cases with fully replaceable components are better positioned for harsh mining and refinery environments, where service access and part longevity directly affect operating economics. At the same time, improved material-science manufacturing and encapsulation techniques are reducing failure modes tied to sealing degradation and environmental exposure. These advances lower the hidden costs of maintenance and unscheduled downtime, which often outweigh initial procurement savings.
Supply-chain considerations also matter. As end users expand deployments across multiple sites and geographies, they increasingly favor suppliers that can provide consistent quality, documented lifecycle support, and repairable architectures. The ability to standardize on platforms with interchangeable parts reduces inventory complexity and shortens repair cycles. In a market where the top five players hold under half of total revenue, there is room for both global integrators and regional specialists to win by aligning cost structures with the operational realities of their target segments.
Competitive Landscape and Leading Strategies
The competitive field blends established motion-control leaders, application-focused specialists, and technology-forward innovators. Each cluster pursues a distinct strategic posture, and understanding these differences is essential for evaluating partnership, sourcing, and investment options.
Premier producers of electrohydraulic servo actuators for industrial, aerospace, and defense motion control occupy the high-performance end of the market. Their differentiation rests on precision linear and rotary systems, rigorous qualification standards, and deep application engineering support. These firms typically compete on reliability, control fidelity, and the ability to meet demanding dynamic requirements where motion accuracy and repeatability are non-negotiable.
Compact electro-hydraulic actuator and hybrid-system suppliers address a different priority: self-contained, high-force linear actuation for industrial and decentralized applications. Their value proposition centers on reducing external hydraulic infrastructure while maintaining force output and controllability. By packaging actuation, fluid handling, and control into compact units, they lower installation complexity and enable point-of-use deployment. This approach is particularly attractive where plant layouts are constrained or where modularity and scalability matter more than centralized hydraulic efficiency.
Specialist manufacturers focused on power stations, refineries, mining, and heavy industrial applications emphasize durability and maintainability. Their actuator designs often feature replaceable parts and robust housing construction suited to abrasive, corrosive, or high-vibration environments. In segments where downtime costs dominate procurement decisions, the ability to repair rather than replace entire units becomes a meaningful commercial advantage. These suppliers also tend to build deep relationships with channel partners and service networks that understand local operating conditions.
Another emerging cluster includes producers of integrated electric-hydraulic linear actuators for heavy-duty lifting, underwater, and extreme-environment applications. Their competitive edge lies in combining high ingress protection, compact form factors, and multi-function integration. By consolidating functions into a single package, they reduce assembly interfaces and simplify specification for environmentally demanding deployments.
On the technology frontier, developers of HASEL electro-hydraulic soft artificial muscles are exploring a different trajectory altogether. Their focus on muscle-like performance for robotics, automation, and dexterous manipulation signals a potential long-term expansion beyond traditional industrial actuation. While these applications are earlier in maturity, they illustrate how electrohydraulic principles can be adapted to soft robotics and precision manipulation, creating optionality for future cross-market growth.
Recent market activity reinforces the importance of performance, safety, and integration. The February 2026 introduction of contracting HASEL electrohydraulic actuators with more than double mechanical output, fully encapsulated design, and improved material-science manufacturing underscores how quickly capability benchmarks are moving. In parallel, functional safety certifications and efficiency-oriented design claims are becoming standard elements of competitive positioning in industrial valve and safety-critical applications.
Several landscape trends are likely to intensify:
- Differentiation by application depth will increase. Companies that invest in segment-specific validation, certification, and service networks will be better positioned than those competing primarily on generic specifications.
- Integration and ecosystem offerings will matter more. End users prefer suppliers that can provide compatible control interfaces, documentation, and support pathways, especially where high-voltage DC operation or analog signal control introduces engineering complexity.
- Repairability and lifecycle economics will become stronger selection criteria. In harsh environments, architectures that enable component replacement and reduce scrap rates align with operational cost goals and sustainability expectations.
- Barrier management will shape consolidation. While the market remains moderately concentrated, larger motion-control platforms may seek to broaden their electrohydraulic portfolios through technology acquisition or partnership, particularly where aerospace, defense, and industrial channels overlap.
Forward Outlook: Trends and Commercial Opportunities
Looking toward 2032, three trends are likely to shape where value is created and captured.
First, efficiency-led specification will broaden adoption. As energy regulations tighten and operating cost sensitivity rises, electrohydraulic actuators that deliver measurable efficiency improvements over traditional hydraulic systems will gain traction across industrial and energy applications. The commercial opportunity lies in quantifying and documenting efficiency gains in real operating conditions, then translating those gains into lifecycle-cost narratives that procurement and engineering teams can use in specification decisions. Suppliers that can supply verified performance data, compatible control solutions, and clear integration guidance will be better placed to convert regulatory momentum into recurring demand.
Second, application-specific platforms will outcompete generic offerings. The diversity of operating environments—from underwater and extreme-temperature settings to safety-critical valve networks and soft robotics experimentation—favors platforms tailored to distinct failure modes, protection requirements, and control architectures. Companies that build validated architectures for targeted segments, supported by replaceable components and robust housing materials, will reduce integration risk and improve customer retention. For investors, the opportunity is in businesses that demonstrate repeatable specification wins within defined end-use pools rather than broad but shallow product lines.
Third, new entrants and technology crossover will reshape sub-segments. Innovations such as high-output contracting electrohydraulic muscles and compact multi-function actuator packages suggest that electrohydraulic principles will continue to migrate into adjacent domains, including automation, manipulation, and specialized lifting. This crossover creates both opportunity and uncertainty. Opportunity arises where proven industrial reliability combines with novel form factors or performance characteristics. Uncertainty stems from the risk that early-stage technologies may face integration, power-supply, or control-compatibility hurdles before achieving scale. Decision-makers should therefore distinguish between near-term commercial adoption in established industrial applications and longer-horizon potential in emerging robotics and automation use cases.
Potential risks and uncertainties deserve equal attention. Regulatory trajectories can shift, altering the pace at which efficiency and safety requirements translate into procurement mandates. Supply-chain disruptions affecting steel housing production, sealing materials, or specialized control electronics may pressure lead times and margins. In addition, the need for high-voltage DC power and specific analog control signals in certain advanced actuator families can constrain deployment where existing infrastructure or in-house expertise is limited. Finally, competitive intensity may increase as larger platforms expand their electrohydraulic offerings, potentially compressing price flexibility in segments with fewer differentiation levers.
Actionable Guidance for Decision-Makers
Strategic responses should be calibrated to role and exposure within the value chain.
For manufacturers and suppliers:
Electric Actuators Market
- Prioritize verified efficiency and functional safety as marketable differentiators. Document efficiency improvements relative to conventional hydraulic systems and secure relevant safety certifications for critical applications. Reliable evidence of performance reduces specification risk for end users and strengthens bidding positions in regulated segments.
- Invest in repairable, environmentally robust architectures for harsh industrial settings. Replaceable components, durable housing materials, and clear service pathways lower total cost of ownership and improve customer retention where maintenance access and uptime are decisive.
- Build application-specific integration support. Where advanced actuator families require high-voltage DC inputs or analog control signaling, provide compatible documentation, validation guidance, and integration assistance. Reducing customer-side engineering burden can be a decisive advantage in complex deployments.
For investors and strategic partners:
- Focus on businesses with segment-specific traction and repeatable specification wins. In a market where the top five suppliers hold less than half of revenue, durable growth often comes from depth in targeted applications rather than broad product breadth alone.
- Evaluate technology crossover potential with discipline. Innovations in output density, encapsulation, and soft-actuation principles can open adjacent markets, but commercial readiness, control compatibility, and power-architecture requirements should be assessed before assuming rapid scaling.
- Monitor consolidation signals and channel strategies. Larger motion-control platforms may seek to strengthen electrohydraulic capabilities, while regional specialists may gain from deep service relationships and local operating knowledge. Both paths can create value, but the economics differ substantially.
For procurement and engineering leaders:
- Evaluate actuators on lifecycle cost, maintainability, safety certification, and efficiency rather than initial price. In safety-critical and maintenance-intensive environments, the cost of downtime and repair often dominates procurement economics.
- Standardize where possible without sacrificing application fit. Selecting platforms with interchangeable parts and consistent integration characteristics can reduce spare-parts complexity and accelerate maintenance, provided the chosen architecture meets environmental and control requirements.
- Validate integration assumptions early. For technologies that require specific power and control architectures, confirm infrastructure readiness and in-house expertise during the specification phase to avoid deployment delays and hidden engineering costs.
The electrohydraulic actuator market is evolving from a mature but narrowly defined niche into a broader, more performance-driven field shaped by efficiency mandates, safety requirements, and application-specific engineering needs. Navigating that transition successfully requires detailed segmentation insight, competitive intelligence, and scenario planning that go beyond top-line growth figures. Comprehensive market research can provide the deeper breakdowns, regional and application-level dynamics, and supplier-level benchmarking needed to translate these trends into concrete sourcing, investment, and product strategy decisions.
For detailed analysis of this topic, please visit the official page: Electrohydraulic Actuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com