

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Tea Tree Oil Market: Why 10.6% CAGR Reshapes Global Value by 2032

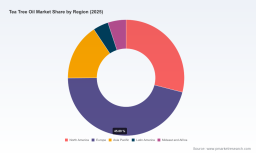
Tea Tree Oil Market: Strategic Shifts and Commercial Opportunities Through 2032
The global tea tree oil market has entered a decisive growth phase, underpinned by structural demand shifts across personal care, household hygiene, and therapeutic applications. Market revenue expanded from approximately USD 490.0 million in 2020 to USD 700.0 million in 2025, with a forecast trajectory climbing toward USD 1.42 billion by 2032. This expansion reflects a compound annual growth rate of 10.6% across the 2026–2032 forecast period, signaling a market that is growing faster than the broader essential oils segment and capturing share from synthetic alternatives. The acceleration is not merely cyclical; it stems from converging forces in consumer preference, regulatory validation, supply chain reconfiguration, and capital deployment by leading producers. For executives and investors, the central question is no longer whether the market will expand, but how value will be captured across a landscape defined by concentration, grade differentiation, and regional specialization.
Understanding the tea tree oil market requires looking beyond headline growth figures. The revenue composition reflects a market that is simultaneously commoditized at one end and highly premiumized at the other, with distinct margin structures, certification requirements, and buyer expectations. Regional dynamics further complicate the picture, as production remains geographically concentrated while consumption patterns diverge across developed and emerging markets. Sustainability credentials, traceability, and supply assurance have transitioned from nice-to-have attributes to baseline procurement requirements. In this context, strategic positioning depends on aligning product grade, sourcing model, certification footprint, and distribution reach with the specific demand clusters that are expanding most rapidly.
Market Dynamics and Structural Challenges
The current market phase is characterized by robust demand pull, but that growth is filtering through a set of operational and regulatory constraints that will determine which players scale profitably. Three structural challenges stand out as defining features of the period ahead.
PW Consulting
Grade Differentiation and Margin Compression Risks
The market is bifurcated between bulk commodity-grade volumes and pharmaceutical-grade material, each serving fundamentally different buyers and pricing dynamics. Commodity-grade supply supports high-volume applications where functional performance and cost efficiency drive purchasing decisions. Pharmaceutical-grade and premium certified volumes command stricter specification controls, traceability requirements, and price premiums, but they also expose producers to higher compliance costs and more exacting buyer scrutiny. The strategic tension lies in managing this dual structure without eroding margin integrity. Producers that cannot sustain specification consistency, batch reliability, and certification upkeep risk being pulled into price competition, while those that over-invest in premium capabilities without securing offtake commitments may face underutilization.
Concentration and Supply Assurance
Production is not evenly distributed, and the market’s concentration profile makes supply assurance a strategic variable rather than a background assumption. A meaningful share of revenue is captured by a limited set of established players, which creates both stability and vulnerability. For buyers, concentration raises questions about continuity of supply during adverse weather, harvest disruptions, or capacity constraints. For producers, it raises the stakes around capacity planning, geographic diversification, and contractual structuring. As demand scales into the next forecast period, supply assurance will increasingly differentiate preferred partners from transactional suppliers.
Regulatory Clarity and Classification Uncertainty
Regulatory development is simultaneously enabling and complicating market expansion. Recent SCCS opinions have affirmed the safe use of tea tree oil as an anti-seborrheic and anti-microbial agent in specific cosmetic product types, reinforcing its positioning in personal care formulations. At the same time, trade concerns have emerged around proposed changes to hazard classification under CLP regulation, with potential implications for import controls and documentation requirements. This dual dynamic creates a market environment where safety endorsement supports demand confidence, while classification scrutiny raises compliance complexity for cross-border trade. Companies that integrate regulatory monitoring into product development and sourcing decisions will be better positioned to avoid formulation disruption and trade friction.
Core Growth Drivers
The market’s expansion is being propelled by four interlocking drivers, each shaping not only volume growth but also the types of products, grades, and supply relationships that will command premium positioning.
Innovation in Extraction, Yield, and Product Development
Technological upgrades across distillation efficiency, biomass utilization, and extraction precision are improving yield quality while reducing processing waste. These advances matter because they directly influence cost structure, specification reliability, and the ability to meet pharmaceutical-grade or certified organic thresholds consistently. Recent capacity upgrades and production optimization initiatives by leading producers illustrate a broader shift toward high-efficiency processing that supports larger volumes without sacrificing purity. From a commercial standpoint, extraction and process innovation create two advantages: they lower the marginal cost of high-specification output and they increase the credibility of premium claims in buyer evaluations. Product-side innovation is equally important. New formulations and application bundles that pair tea tree oil with complementary natural actives are expanding the addressable use cases beyond traditional antiseptic and cleansing roles, creating additional pull from skincare, scalp care, and household hygiene categories.
Policy and Regulatory Tailwinds with Ongoing Watchpoints
Regulatory developments are acting as a demand enabler in personal care by validating functional claims and setting clear use parameters. The confirmation of safe use in defined cosmetic applications supports formulation confidence and reduces uncertainty for ingredient purchasers and brand developers. At the same time, classification and trade notifications introduce a compliance dimension that should be factored into sourcing and market-entry plans. For multinational buyers, the practical implication is that regulatory foresight is now part of supply selection. Suppliers that maintain rigorous documentation, adapt to evolving hazard classification expectations, and provide formulation support will hold an advantage in procurement evaluations. For producers, the opportunity lies in aligning certification, testing, and labeling practices with the markets they intend to serve, rather than treating compliance as a post-production exercise.
Demand-Side Reorientation Toward Natural, Sustainable, and Traceable Inputs
Consumer and enterprise purchasing behavior continues to shift toward ingredients with verifiable provenance, lower environmental footprints, and credible ethical or organic credentials. In personal care, this has translated into stronger demand for organic, regeneratively sourced, and Fair Trade-aligned tea tree oil, particularly in premium skincare and wellness product lines. In household cleaning and hygiene, the driver is slightly different but related: buyers want effective natural antimicrobial alternatives that fit sustainability narratives and ingredient transparency expectations. This demand-side reorientation is not a niche trend; it is reshaping procurement specifications across multiple channels. As a result, traceability, certification, and storytelling around sourcing practices have become commercial assets that influence both pricing power and shelf positioning.
Supply Chain Realignment and Export-Oriented Capacity Building
Supply chain expansion is another defining driver. Several producers have moved to strengthen export-oriented operations, broaden distributor relationships across Europe and Asia, and invest in plantation and harvesting capacity. This matters because regional demand growth is outpacing local supply in key consumption markets, making export logistics, bulk handling, and consistent supply timing strategically important. The broader effect is a market in which capability to serve international buyers reliably, with the right grade mix and documentation, is becoming a differentiator. Suppliers that integrate cultivation, distillation, quality control, and export logistics into a coordinated model are better positioned to capture demand from markets where natural personal care and hygiene adoption is accelerating.
Worldwide Tea Tree Extract Market
Competitive Landscape and Strategic Positioning
The competitive field combines specialists with deep production and certification roots against global brands that leverage brand equity, distribution scale, and formulation ecosystems. Rather than a single competitive model, the market now rewards distinct strategic archetypes.
Leading Players and Their Strategic Anchors
Australian producers remain central to the market’s premium and pharmaceutical-grade supply, with several companies anchoring their positioning around purity, certification, and vertical integration. G.R. Davis Pty Ltd has built its identity around growing, distilling, and refining pure Australian tea tree oil across grades, including pharmaceutical-grade, supported by ISO9001 and CODEX HACCP certifications. This positions the company as a specification-sensitive supplier for buyers that require documented quality systems and consistent batch integrity. Main Camp Natural Extracts Pty Ltd differentiates through scale in plantation ownership and high-efficiency on-site distillation, emphasizing highest-purity output and premium and organic grades. Its strategic anchor is supply depth and processing efficiency, which supports volume reliability and premium positioning simultaneously. Jenbrook Australia Pty Ltd emphasizes certified organic production and supply, aligning with buyers that prioritize organic credentials and clean sourcing narratives. Oribi Oils (Pty) Ltd, based in South Africa, adds a different value proposition by combining pure tea tree oil with lemon-scented variants and a community-focused model supported by organic, Fair Trade, and Regenerative Organic certifications. This illustrates how ethical sourcing and certification can be used not only for compliance but also as market access and premiumization tools. On the brand and distribution side, doTERRA International LLC and Young Living Essential Oils leverage premium essential oil positioning, strong consumer-facing channels, and formulated product ecosystems. Their strength lies in translating ingredient quality into finished-product demand, particularly in skincare, scalp health, and household purification applications. Integria Healthcare Pty Ltd represents the healthcare and wellness integration angle, where tea tree oil is incorporated into broader wellness products rather than sold solely as a raw material input.
Recent Developments as Strategic Signals
Recent activity across the market shows a clear pattern: capital is flowing into capacity, plantation depth, export supply chains, and productization. Capacity upgrades in large-scale steam distillation and high-efficiency biomass boiler systems have strengthened the ability to supply higher volumes of high-purity pharmaceutical-grade material. Plantation expansion and advanced agricultural technologies have reinforced long-term yield stability and raw material control. Dedicated export supply chain expansion toward major distributors in Europe and Asia reflects a deliberate push to capture demand in regions where natural ingredient adoption is rising. Production optimization focused on eco-friendly extraction has improved alignment with sustainability expectations while supporting efficient output. On the brand side, expanded extraction facilities and new organic skincare launches indicate that demand is being pursued not only at the ingredient level but also through finished-product pipelines. The strategic signal is consistent: winners are investing where demand is most durable and where differentiation can be defended through certification, purity, scale, or formulation strength.
Evolution of the Market Structure
The market is likely to evolve along two parallel tracks. In one, consolidation and partnership intensify among producers capable of delivering pharmaceutical-grade assurance, export reliability, and certified sustainability. In the other, segmentation continues between premium branded ecosystems and commodity-driven supply channels. New entrants will find opportunity not by competing head-on across all dimensions, but by specializing: for example, in certified organic supply, traceable community-sourced models, regional distribution partnerships, or application-specific formulations. The most durable advantage will belong to players that can combine grade control, certification credibility, and supply continuity with a clear route to the demand segments they target.
Forward Outlook and Commercial Opportunities
Looking across the 2026–2032 forecast window, three trends are especially consequential for strategy and investment decisions.
Premiumization with Specification Sophistication
Demand for pharmaceutical-grade and certified organic tea tree oil is expected to keep rising, particularly in personal care and wellness applications where formulation integrity and claim support matter. The commercial opportunity lies in building or securing supply that can consistently meet stricter specifications, maintain documentation rigor, and satisfy buyer audit requirements. This is not only a production challenge; it is a commercial one, because premium-grade buyers often value reliability, test data, and traceability as much as price. Suppliers that can operationalize this level of assurance will be able to defend margins even as overall market volume grows.
Regional Demand Diversification and Export Opportunity
Consumption growth is broadening beyond traditional strongholds, with Europe and parts of Asia showing strong pull for natural personal care, household hygiene, and sustainable ingredient narratives. For producers and exporters, the opportunity is to match grade portfolios and logistics capabilities to the specific entry points in these regions, including distributor networks, formulation requirements, and regulatory expectations. For buyers, the opportunity is to secure multi-source supply strategies that reduce concentration risk while preserving access to high-specification material. The markets that grow fastest will reward players that can move reliably across borders with the right documentation and grade alignment.
Functional Expansion Beyond Traditional Use Cases
Tea tree oil is increasingly being embedded into broader skincare, scalp care, air purification, and household hygiene solutions. This functional expansion creates opportunity for combination products, targeted formulations, and usage-specific positioning. The strategic implication is that raw material suppliers and brand developers can capture more value by aligning around application needs rather than selling a single generic input. Formulation expertise, stability data, and compatibility knowledge will become more valuable as tea tree oil appears in more diversified product architectures.
Eucalyptus Oil Market
These opportunities come with watchpoints. Regulatory classification developments, trade notifications, and safety opinions can shift compliance requirements and import conditions. Supply concentration means that weather, crop risk, or capacity constraints can affect availability. Sustainability claims also face rising scrutiny, making credible certification and verifiable sourcing essential rather than optional. Companies that treat these as manageable variables, monitored and incorporated into planning, will be better placed to benefit from growth without being disrupted by it.
Actionable Implications for Decision-Makers
For manufacturers and brand developers, the priority is to align product portfolios with the grade and certification profiles that buyers increasingly require. That means defining whether the strategy depends on bulk commodity-grade cost efficiency or premium pharmaceutical-grade and certified organic differentiation, and then building sourcing, quality systems, and documentation to match. Formulation teams should also evaluate how tea tree oil can be integrated into broader natural and sustainable product lines in ways that support both performance and claim credibility, especially as regulatory validation continues to shape acceptable use cases.
For investors, the attractive thesis is not simply market growth but the quality of the growth. Capital deployed into capacity that improves yield, purity, and export reliability, or into brands that can convert ingredient demand into finished-product momentum, is better positioned than capital chasing undifferentiated volume. Due diligence should focus on certification integrity, supply chain resilience, regulatory preparedness, and the durability of offtake relationships in target regions. In a market where concentration and grade differentiation matter, operational and compliance capabilities are as important as top-line expansion.
For procurement and supply chain leaders, the strategic move is to reduce dependency on single-source assumptions while preserving access to high-specification material. Multi-source strategies, clear grade requirements, and contractual terms that protect continuity during harvest or capacity cycles will become more valuable as demand scales. Procurement teams should also integrate regulatory monitoring into supplier selection, ensuring that classification, hazard documentation, and import requirements do not become last-minute disruptions. The most resilient sourcing models combine quality assurance, traceability, and geographic or supplier diversity with a clear understanding of the end-use grade needed.
Given the pace of capacity expansion, regulatory evolution, and regional demand shifts, detailed segmentation data, supplier capability assessments, and region-specific forecasts can materially improve strategic timing and resource allocation. The broader market direction is clear, but the specifics of grade mix, regional exposure, certification pathways, and competitive positioning determine where value is actually captured. Decision-makers looking to move from directional awareness to executable planning will benefit from a closer reading of the segment-level dynamics and company-specific developments shaping this market.
For detailed analysis of this topic, please visit the official page: Tea Tree Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com