

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Caprolactone Market 2026: Why 3.27% CAGR and Asia Pacific Demand Redefine Growth

Strategic Trends and Commercial Opportunities in the Caprolactone Market (2026–2032)
The global caprolactone market has matured into a specialized yet strategically significant segment of the broader specialty chemicals and bioplastics ecosystem. Valued at approximately $208.75 million in 2020, the market expanded to an estimated $244.23 million by 2025, with projections indicating a compound annual growth rate of 3.27 percent through 2032. Reaching roughly $305.62 million by the end of the forecast period, the trajectory reflects steady, moderate expansion rather than explosive growth. This measured pace underscores a market defined by technical specialization, regulatory navigation, and shifting downstream demand across adhesives, coatings, thermoplastic polyurethanes, and biodegradable polymer applications.
The base year of 2025 marks a critical inflection point. The market has moved past its early adoption phase and into a period where supply chain consistency, purity specifications, and regulatory compliance increasingly dictate competitive positioning. Concentration metrics reveal a moderately consolidated landscape, with the top three players accounting for 48.5 percent of total market share and the top five reaching 61.2 percent. Such concentration suggests that established participants control significant portions of capacity and distribution, yet meaningful room remains for differentiated players who can address specific purity requirements, regional supply gaps, or emerging application niches.
Despite the upward revenue trajectory, the industry faces structural tensions that will shape investment decisions and strategic planning over the next several years. Understanding these pressures is essential for executives evaluating exposure to caprolactone-derived materials or considering capacity allocation in adjacent specialty chemical portfolios.
Market Context and Core Challenges
A Moderately Consolidated Specialty Chemical Segment
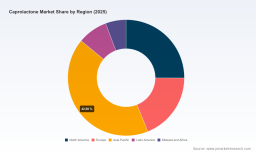
The caprolactone market operates at the intersection of performance materials and sustainability-driven substitution. Demand is distributed across multiple application tracks, with polycaprolactone production and specialty polymer synthesis representing the largest consumption pools, while thermoplastic polyurethane formulations, adhesives, coatings, and dedicated biodegradable polymer segments absorb the remainder. Regional activity spans mature industrial markets with established formulation infrastructure alongside rapidly expanding manufacturing hubs where capacity additions and export-oriented production are reshaping trade flows.
Concentration in the market reflects the technical barriers to entry. Producing epsilon-caprolactone at commercial scale requires controlled oxidation pathways, careful handling of intermediates, and consistent purity management. Buyers in pharmaceutical-adjacent synthesis, high-performance coatings, or regulated adhesive systems prioritize batch reliability and certified quality, reinforcing the advantage of established producers. At the same time, the presence of multiple regional manufacturers and specialty chemical firms indicates a market that rewards operational execution and customer-specific technical support rather than volume alone.
Key Challenges Shaping Current Decision-Making
Several intersecting challenges define the current operating environment for caprolactone suppliers, buyers, and investors.
- Raw material dependency and process sensitivity. Caprolactone is derived from cyclohexanone through hydrogen peroxide oxidation, a pathway that ties product economics and supply continuity to the availability and pricing of upstream precursors. Fluctuations in feedstock markets, oxidation yield variability, and plant operating reliability can influence margins and delivery consistency, particularly for buyers requiring tight purity tolerances.
- Regulatory complexity across export markets. Manufacturers targeting multiple regions must navigate registration and compliance regimes such as European REACH and Korean K-REACH, alongside customer-specific documentation requirements. Registration status has become a practical competitive factor, affecting market access for new entrants and shaping procurement decisions for buyers who prioritize supply chain transparency and regulatory readiness.
- Demand fragmentation across applications. While polycaprolactone production remains the dominant use case, growth in coatings, adhesives, TPU formulations, and biodegradable polymers is uneven. Different applications impose different purity thresholds, performance specifications, and volume expectations, making it difficult for a single product grade or marketing message to capture broad demand. This fragmentation rewards suppliers that can align capacity, technical support, and distribution with specific application verticals.
These challenges are not insurmountable, but they do require deliberate strategy. The most resilient participants are those treating caprolactone not as a generic intermediate, but as a performance material with application-specific value propositions, regulatory preparedness, and distribution alignment.
Key Drivers Shaping Market Dynamics
Technical Innovation and Purity Differentiation
Purity specifications remain one of the clearest drivers of value creation in this market. The split between standard and higher-purity grades reflects different buyer expectations: industrial-scale polymer production often prioritizes cost efficiency and volume consistency, while specialty synthesis, advanced coatings, and high-performance adhesive formulations demand tighter specifications and more controlled impurity profiles. Over recent periods, producers have emphasized grade differentiation and application-focused technical positioning, enabling them to capture value in segments where performance matters more than unit cost alone.
Recent product and exhibition activity illustrates how manufacturers are using technical presence to anchor demand. Participation in major coatings and polymer events has become a visible channel for signaling grade availability, application flexibility, and formulation support. For example, Ingevity exhibited Capa caprolactone polyols at the European Coatings Show in Frankfurt in March 2025, reinforcing its focus on formulation-sensitive end markets. Around the same timeframe, Hunan Juren Chemical advanced its presence in international forums, and by early 2026 consolidated its positioning in PCL-related materials through continued production growth and trade engagement. These moves reflect a broader pattern: suppliers are competing increasingly on application relevance and technical credibility, not merely on listing a commodity-grade monomer.
Policy, Registration, and Compliance as Market Enablers
Regulatory readiness has shifted from back-office compliance to a frontline competitive consideration. For caprolactone, registration achievements in key export markets directly affect which buyers can source from which suppliers with confidence. Holding European REACH and Korean K-REACH registrations, for instance, reduces procurement friction for formulators and distributors who need documented compliance for their own downstream customers.
This dynamic favors producers that have invested early in registration and documentation, particularly those seeking to serve multi-region demand. It also creates a practical barrier for less-prepared entrants, even where manufacturing capacity might otherwise be available. For buyers, this means supplier selection increasingly includes compliance assurance as a procurement criterion, not just price and lead time. For investors and strategic planners, registration status is a signal of long-term market access, especially in applications that feed into regulated end-use industries.
Demand-Side Evolution Toward Performance and Sustainability
Downstream demand is changing in ways that favor specific caprolactone value propositions. In adhesives and coatings, formulators continue to seek tunable polymer characteristics that balance adhesion, flexibility, and durability, while also accommodating sustainability messaging where feasible. In thermoplastic polyurethane and biodegradable polymer segments, caprolactone-based materials offer properties that align with performance targets and, in some cases, with broader material transition narratives. The commercial appeal lies not in generic substitution, but in targeted performance improvement and material design flexibility.
Distribution choices are adapting accordingly. In June 2025, Ingevity established Jamplast as the exclusive US and Canada distributor for Capa caprolactone products in bioplastics, a move that reflects the importance of regional channel expertise in reaching formulation customers efficiently. Such arrangements can accelerate market penetration by pairing product availability with distributor relationships already embedded in local application ecosystems. For buyers, this suggests a market where sourcing options are becoming more structured and regionally specialized, rather than uniformly global.
Polycaprolactone Market
Supply-Side Adjustments and Capacity Realignment
Capacity and operational adjustments are reshaping how the market balances supply with regional demand. Debottlenecking and targeted production expansion have become practical levers for participants seeking to support growth without undertaking full-scale greenfield projects. Perstorp's debottlenecking of Capa caprolactone derivatives units at Warrington, UK, is an example of optimizing existing assets to serve global demand more effectively. Meanwhile, Hunan Juren Chemical's continued production growth and expansion of sales agency coverage in Japan illustrate how capacity increases can be paired with regional commercial expansion.
These supply-side actions matter because they influence lead times, regional availability, and pricing stability. For procurement teams, capacity reliability can be as important as unit cost, especially when formulation schedules and downstream production planning depend on predictable monomer supply. For competitors, the strategic question is whether to expand broadly or to focus on segments where purity, registration, and application support justify stronger margins.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The caprolactone market features a mix of global specialty chemical firms and regionally focused manufacturers, each leveraging different strengths. Ingevity Corporation has built its position around the Capa brand of caprolactone monomer and derivatives, emphasizing applications in adhesives, coatings, bioplastics, and performance materials. Its recent activities highlight a dual strategy: deepen formulation-market engagement through exhibitions and technical presence, while also optimizing commercial reach through distribution partnerships. At the same time, broader portfolio considerations, including reported business considerations involving its Advanced Polymer Technologies segment in late 2025, indicate that caprolactone assets may be evaluated within larger corporate portfolio strategies, a reminder that specialty chemical assets can move unpredictably when parent companies reassess segment priorities.
Worldwide ¦Ä-Valerolactone Market
Hunan Juren Chemical has emerged as an active Chinese manufacturer with a focus on epsilon-caprolactone, PCL polyols, and biodegradable materials. Its growth trajectory has been supported by capacity expansion, certification achievements including REACH and K-REACH registrations, and increased international trade engagement. Participation in industry events and the establishment of sales agency coverage in Japan reflect a strategy oriented toward widening export reach and reinforcing regional supply relationships. For buyers seeking alternative sourcing or region-specific supply, such positioning can be strategically relevant, especially when paired with compliance documentation.
Large international chemical and specialty material companies, including BASF SE, Solvay SA, Daicel Corporation, and Sigma-Aldrich Corporation, occupy distinct roles. Some participate through integrated monomer and derivative portfolios, while others focus on synthesis-grade supply and specialty applications. Daicel's Placcel caprolactone monomer, for instance, aligns with pharmaceutical-grade and advanced polymer synthesis needs, showcasing how product positioning can be tailored to high-specification segments. Merck KGaA's Sigma-Aldrich brand serves research and industrial formulation channels where small-volume, high-purity supply and technical documentation are critical. These differentiated roles illustrate a market where scale, purity, and application focus define separate competitive lanes.
Perstorp Holding AB has reinforced its specialty chemical identity by optimizing Capa caprolactone derivatives production and supporting global demand through operational improvements. Its approach highlights the value of debottlenecking and incremental capacity enhancement as a practical growth path, especially where the objective is to improve reliability for existing application customers rather than launch completely new product categories.
How the Competitive Landscape Is Evolving
The market is evolving along several concurrent lines. First, application-aligned competition is intensifying. Suppliers are increasingly evaluated by buyers based on formulation fit, registration status, and regional availability rather than generic product listing. This favors firms that can demonstrate consistent grade quality, technical support, and channel reliability in the specific verticals they target.
Second, regional supply dynamics are becoming more pronounced. Differences in registration coverage, distribution partnerships, and capacity location are shaping procurement preferences in North America, Europe, Asia Pacific, and other regions. Buyers in markets with stricter documentation requirements or with strong local formulation ecosystems may prefer suppliers that have both compliance readiness and appropriate channel access.
Third, portfolio and asset realignment introduces uncertainty and opportunity. The possibility of segment sales, restructuring, or broader corporate portfolio changes can alter supply relationships quickly. While such developments can create supply continuity considerations for some buyers, they can also open pathways for new commercial structures, distribution partnerships, or capacity acquisitions by competitors seeking to strengthen their position.
Overall, the landscape is not moving toward pure price competition. Instead, it is becoming more segmented, with winners differentiating through purity grades, application focus, compliance documentation, and regional supply reliability. For market participants, the practical implication is that positioning must be deliberate: broad exposure without clear application alignment tends to dilute advantage in a market where specifications and compliance matter.
Forward Outlook: Trends and Opportunities for 2026–2032
Trend One: Application-Specific Value Creation Will Outpace Generic Volume Play
Over the next three to five years, the most durable growth will likely come from segments where caprolactone provides clear functional advantages rather than from undifferentiated volume expansion. Formulators in adhesives, coatings, and TPU-related applications will continue to seek materials that offer tunable properties, process compatibility, and reliable performance. Where caprolactone grades can be positioned as enabling ingredients rather than commodity inputs, pricing power and customer stickiness improve.
Commercial opportunity lies in aligning product grades, technical documentation, and distributor relationships with those application priorities. Suppliers and buyers alike benefit when specifications are matched closely to end-use requirements, reducing reformulation risk and improving supply predictability.
Trend Two: Regulatory Readiness Will Become a Procurement Gatekeeper
As multi-region trade continues and downstream industries face increasing scrutiny around material documentation, registration status and compliance readiness will increasingly function as a gatekeeper for supplier selection. Manufacturers with established REACH and K-REACH coverage, and with transparent documentation practices, will have an easier path into regulated supply chains. This trend is likely to consolidate procurement around suppliers that can reduce compliance risk for their customers.
The opportunity here is twofold. For producers, early investment in registration and documentation can translate into durable market access. For buyers, prioritizing suppliers with demonstrated compliance readiness can lower downstream risk, especially in applications feeding into industries where customer audits and material traceability are routine.
Trend Three: Regional Capacity Realignment Will Shape Supply Security
Capacity adjustments, whether through debottlenecking, targeted expansion, or regional sales infrastructure, will influence which suppliers can reliably serve specific geographies. The market is likely to see continued emphasis on optimizing existing assets and strengthening regional channels rather than relying solely on large-scale new capacity additions. This dynamic favors participants that can combine operational flexibility with localized commercial presence.
For procurement and supply chain teams, the practical takeaway is to evaluate regional availability, lead-time reliability, and channel structure alongside price. For investors and strategists, capacity moves should be interpreted in the context of application focus and regulatory readiness, not merely as volume indicators.
Uncertainties Worth Monitoring
Several factors could alter the trajectory. Shifts in upstream feedstock markets and oxidation process economics may affect cost structures and margin resilience. Portfolio decisions by larger chemical companies could redirect caprolactone assets or change supply relationships unexpectedly. Demand growth in biodegradable polymers and related segments may evolve at different speeds depending on formulation adoption, end-market acceptance, and the pace of sustainability-driven substitution. Finally, regional compliance requirements and trade dynamics can change procurement preferences faster than capacity can be rebalanced, particularly in markets where documentation and channel access determine practical availability.
These uncertainties do not imply downside inevitability. Rather, they highlight the need for scenario-aware planning. Companies that monitor feedstock sensitivity, registration status, distribution alignment, and application demand together will be better positioned to anticipate shifts rather than react to them.
PW Consulting
Strategic Actions for Decision-Makers
For Manufacturers and Formulators
Alignment between grade strategy and application demand should be a priority. Evaluate whether current product specifications match the purity, documentation, and performance needs of target segments. Where possible, strengthen technical engagement and distribution partnerships in regions where formulation customers are concentrated. Consider registration and compliance readiness as part of product strategy, especially when serving multi-region customers or regulated downstream industries.
- Map capacity and grade availability against the application segments most likely to grow, rather than assuming uniform demand across all uses.
- Use trade presence and technical demonstrations to reinforce formulation relevance, particularly in coatings, adhesives, and biodegradable polymer channels.
- Monitor potential asset or segment realignment among larger players, since these can affect supply continuity and competitive dynamics quickly.
For Investors and Strategic Planners
Caprolactone should be evaluated as a specialty segment where value is shaped by purity differentiation, compliance readiness, and application alignment rather than by headline volume alone. Due diligence should consider registration status, regional distribution structure, feedstock exposure, and the parent company's broader portfolio strategy. Capacity announcements are useful, but they matter most when paired with clear commercial focus and regulatory preparedness.
- Prioritize targets where technical positioning and compliance documentation support durable customer relationships, not only where capacity is expanding.
- Assess regional supply gaps and channel strength, particularly where local formulation demand is growing and where distributor relationships can accelerate market entry.
- Track corporate portfolio decisions and segment-level asset movements, since these can create acquisition opportunities or supply reassessments.
For Procurement and Sourcing Leaders
Supplier selection should incorporate compliance readiness, regional availability, and application-specific grade consistency alongside cost. Where formulations depend on predictable monomer supply and tight specifications, reliability and documentation can be as strategic as unit price. Diversifying sourcing options across suppliers with different regional strengths may reduce exposure to single-point disruptions or sudden portfolio changes.
- Verify registration and documentation coverage for the regions and applications that matter most to your supply chain.
- Evaluate distributor and channel structures, especially when sourcing in territories where local technical support and logistics affect delivery performance.
- Build contingency awareness around potential asset or segment-level changes among major suppliers, and maintain visibility into alternative qualified sources.
The caprolactone market is entering a phase where disciplined positioning matters more than ever. Moderate but steady growth, application-specific demand, evolving compliance expectations, and ongoing capacity realignment create a landscape that rewards clarity of strategy. For decision-makers seeking deeper segment data, regional breakdowns, and customized scenario planning, comprehensive research coverage can provide the granularity needed to translate these trends into precise commercial action.
For detailed analysis of this topic, please visit the official page: Caprolactone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com