

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
LED Panel Lights Market Set for 8.5% CAGR Growth Through 2032

Strategic Trends and Commercial Opportunities in the Worldwide LED Panel Lights Market
Market Landscape and Core Challenges
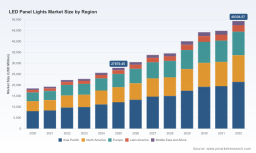
The global LED panel lights market has matured into a multi-billion-dollar segment, with revenue climbing from approximately USD 18.5 billion in 2020 to an estimated USD 27.9 billion by 2025. The trajectory reflects sustained cumulative growth of over 50% across the five-year span, driven by structural replacements of legacy fluorescent and high-intensity discharge fixtures in both commercial and residential settings. Looking ahead, the market is projected to expand from roughly USD 30.5 billion in 2026 toward USD 49.3 billion by 2032, sustaining a compound annual growth rate near 8.5% through the forecast period. This expansion is not merely a continuation of replacement cycles; it signals an inflection point where lighting transitions from a purely utilitarian component to a platform for energy optimization, space reconfiguration, and human-centric environment design.
Several structural challenges are reshaping how participants navigate the next phase of growth. First, regulatory efficacy thresholds are tightening globally, forcing manufacturers to reconcile performance requirements with cost constraints and design trade-offs. As standards evolve, products that once qualified as efficient are being outclassed by newer benchmarks, pushing continuous R&D investment and rendering legacy SKUs obsolete faster than in prior cycles. Second, the supply chain for key semiconductor and rare-earth materials remains exposed to geopolitical friction and licensing adjustments. Export controls and tariff frameworks affecting gallium, germanium, and certain processed critical minerals have introduced intermittent cost volatility and sourcing complexity, particularly for manufacturers reliant on specific regional component pipelines. Third, price compression in LED chips and core components continues to reshape margin dynamics. Capacity expansions and the transition to larger wafer formats have lowered input costs, but they simultaneously intensify competition on price, shifting the battleground toward differentiation in optics, controls integration, and application-specific engineering rather than raw lumen output alone.
The market also exhibits moderate concentration, with the top three firms capturing roughly 18.5% of revenue and the top five approaching 28.4%. This fragmented yet increasingly consolidated structure indicates that scale advantages exist, but regional expertise, application specialization, and channel relationships still determine competitive outcomes in many geographies. For decision-makers, the central challenge is to balance volume efficiency with the innovation required to stay ahead of tightening standards and shifting buyer expectations.
Key Drivers of Market Change
Technological Innovation and Performance Breakpoints
Advances in LED chip architecture, thermal management, and optical extraction are redefining what a panel light can deliver. The shift toward higher-efficacy packages and improved luminaire-level designs is enabling installations that meet tighter energy codes while reducing the number of fixtures needed for a given illuminance target. Manufacturers are increasingly building panels with tunable-white capabilities, enhanced glare control, and integrated sensing or communication features, transforming the product from a static light source into an active component of smart building ecosystems. These capabilities matter commercially because they allow facility operators to align lighting with occupancy patterns, daylight availability, and wellness objectives without separate retrofit hardware.
Policy and Regulatory Momentum
Government and standards-body initiatives continue to accelerate adoption by raising minimum performance bars and incentivizing commercial retrofits. Updated efficacy requirements for solid-state lighting took effect in early 2026, raising minimum thresholds across categories by roughly 14% and effectively resetting the baseline for compliant products. Alongside these mandates, public and utility-led programs continue to support energy-efficient upgrades in offices, institutions, and industrial facilities. The practical effect is twofold: buyers face stronger reasons to replace aging fixtures now rather than defer upgrades, and suppliers must ensure their portfolios meet or exceed revised benchmarks to remain eligible for incentive-driven procurement.
Demand-Side Behavior Shifts
Buyers are increasingly evaluating lighting as part of a broader total-cost-of-ownership calculation rather than as a standalone commodity. Commercial operators prioritize long lifespans, maintenance reductions, and compatibility with building management systems. Healthcare and institutional purchasers focus on visual comfort, circadian-supportive tuning, and reliable performance in sensitive environments. Residential demand, while smaller in absolute revenue contribution, is growing as homeowners and multi-family developers standardize on flat-panel forms for renovation and new construction, especially where ceiling heights and aesthetic preferences favor low-profile solutions. This diversified demand mix encourages manufacturers to tailor product lines rather than push a uniform offering across segments.
Supply Chain and Cost Structure Evolution
On the input side, the LED component market has experienced sustained price compression as capacity expands and manufacturers transition to larger wafer formats such as 8-inch GaN-on-Si. This shift supports lower assembly costs and enables more aggressive pricing in volume segments. At the same time, sourcing of critical materials remains sensitive to trade policy and licensing conditions, creating pockets of uncertainty for product lines heavily dependent on specific raw-material pathways. The net result is a market where cost advantages from components can be partially offset by geopolitical and logistics variability, reinforcing the value of diversified sourcing and forward hedging for larger producers. Recent trade-show presentations have highlighted energy efficiency and human-centric design as recurring themes, reflecting how suppliers are positioning these cost and performance dynamics as competitive differentiators.
Competitive Landscape and Leading Strategies
The competitive field includes established global players with broad portfolios and strong channel presence, alongside regional manufacturers that compete on price, responsiveness, and localized application support. Global leaders with heritage in lighting and component systems emphasize integrated smart controls, high efficacy, and application-optimized designs for offices, retail, and institutional environments. These firms often leverage brand trust, regulatory-compliance track records, and building-system integration capabilities to secure large commercial accounts. Component-oriented suppliers contribute high-performance LED modules and finished panels focused on reliability and commercial/industrial use, while North American manufacturers have built strong positions through established brand portfolios tailored to commercial, institutional, and architectural specifications.
LED Grow Lights Market
In the premium tier, some participants differentiate through advanced optics, tunable white, and human-centric lighting features, targeting architects and design-led projects where visual quality and flexibility carry premium value. Other manufacturers concentrate on energy-efficient solutions for both commercial and residential markets, emphasizing quality, longevity, and integration with building systems. Large industrial and electrical groups extend their reach through dedicated lighting portfolios that serve commercial, industrial, and hazardous-location applications, using existing distribution relationships and engineering support networks to win specification work. In Asia and export markets, cost-effective and mid-tier manufacturers have expanded their footprint by combining affordable pricing with broad product ranges, and specialized producers have carved out niches with customizable high-lumen panels, dimming options, and certification-ready configurations for commercial projects. Others focus on ceiling panel lights and linear systems for architectural and commercial work, maintaining visibility through trade-show participation and international distribution.
The landscape is evolving through a mix of consolidation and differentiation. Larger incumbents are strengthening portfolios through brand breadth, controls integration, and reliability credentials, while regional players compete by aligning product specifications closely with local code requirements, price sensitivity, and application needs. New entrants tend to succeed when they address specific gaps rather than attempting head-on competition across the entire spectrum. Recent market activity illustrates how firms are positioning themselves: one manufacturer emphasized energy efficiency and human-centric design in panel and linear solutions at a major Frankfurt fair, signaling an industry-wide pivot toward performance-plus-wellness narratives. Simultaneously, updated technical requirements for solid-state lighting raised efficacy thresholds by approximately 14%, compelling portfolio upgrades and creating a natural filter that favors suppliers with stronger R&D and faster compliance cycles. For buyers, the implication is that specification value increasingly resides in verified performance, interoperability, and documentation quality, not just initial price.
Future Outlook: Three Trends Shaping the Next 3–5 Years
The first trend is mainstream human-centric and tunable lighting. As circadian-supportive features and daylight-aligned tuning move from niche to standard expectations in commercial, healthcare, and higher-end residential projects, manufacturers that can deliver reliable color consistency, intuitive controls, and documented visual-comfort benefits will capture premium specifications. The commercial opportunity lies in bundled offerings that pair panels with sensing, scheduling, and integration tools, reducing the need for separate retrofit layers.
The second trend is controls and interoperability as a core product attribute rather than an add-on. Building operators increasingly want lighting that communicates with energy-management platforms, occupancy sensors, and daylight-harvesting systems. Products designed from the outset for interoperability will gain preference in specification work, particularly where efficiency mandates and operational cost pressures make integrated automation attractive. The opportunity is to streamline commissioning and data visibility so that lighting contributes measurable savings and maintenance intelligence.
The third trend is regional diversification of supply and product strategy. Given continued sensitivity around critical materials and shifting trade frameworks, participants are likely to expand multi-source procurement, adjust regional assembly footprints, and tailor portfolios to local code trajectories. For manufacturers, this creates opportunities in application-specific designs and localized compliance documentation. For buyers, it rewards suppliers with transparent sourcing and resilient delivery models. The principal risk is that tighter standards and material constraints could compress margins for undifferentiated products, while rapid product cycles may challenge inventory planning if demand shifts faster than forecasts anticipate.
PW Consulting
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with revised efficacy benchmarks and application-specific value propositions. Investing in optics, thermal design, and controls-ready architectures will protect eligibility for incentive-driven commercial work and support premium positioning where visual quality and wellbeing matter. Diversifying component sourcing and locking in compliant SKU transitions will reduce exposure to material and regulatory friction.
For investors, the most durable opportunities sit with suppliers that combine verified performance, interoperability, and regional execution capability. Preference should be given to businesses that can demonstrate repeatable compliance, clear differentiation beyond price, and the ability to serve both broad commercial accounts and specialized application niches. Monitoring portfolio refresh cycles and certification readiness is a useful leading indicator of resilience.
OLED Lighting Panels Market
For procurement and specification teams, the practical value lies in evaluating total cost of ownership, including energy performance, maintenance intervals, and integration effort, rather than minimizing upfront unit price. Verifying documentation, interoperability claims, and warranty terms will reduce long-term operational risk. Given the pace of regulatory change and portfolio evolution, maintaining access to detailed segment-level data and tailored procurement guidance can materially improve specification choices and budget planning, particularly when projects span multiple codes and application requirements.
Detailed breakdowns by region, product type, application, and competitive positioning can help translate these market-level dynamics into project-level decisions. Comprehensive research covering submarket sizes, adoption trajectories, and company-specific positioning is available for teams that need granular inputs for budgeting, sourcing, and strategic planning.
For detailed analysis of this topic, please visit the official page: Worldwide LED Panel Lights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com