

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Plasma Etch System Market: How 13.5% CAGR and Semis Drive 2032

Navigating the Plasma Etch System Market: Strategic Trends and Commercial Opportunities Through 2032
The plasma etch system market has entered a phase of sustained expansion, driven by relentless demand for miniaturization, advanced packaging, and specialized surface engineering across multiple high-tech sectors. Historical data from 2020 through 2025 shows a market trajectory that has consistently outpaced broader semiconductor equipment cycles, with revenues climbing from approximately 163 million to 215 million over that span. The forward curve suggests continued momentum, with the market projected to exceed 344 million by 2032, reflecting a compound annual growth rate of roughly 13.5 percent. This expansion is not merely a function of cyclical upturns; it represents structural shifts in how manufacturers approach material removal, surface modification, and precision patterning at increasingly aggressive technology nodes.
Yet the headline growth figures only tell part of the story. Beneath the surface, the market is navigating a complex set of operational, regulatory, and competitive pressures that are reshaping how equipment suppliers design, sell, and support plasma etch platforms. For executives and investors evaluating exposure to this space, understanding the interplay between technology roadmaps, cost structures, and policy mandates is essential to positioning for the next phase of value creation.
Mapping the Current Landscape and Defining Constraints
The revenue distribution across regions highlights a globally dispersed but increasingly interconnected demand base, with Asia Pacific and North America together accounting for the largest share of system placements. Europe maintains a meaningful footprint, while Latin America and the Middle East and Africa represent smaller but steadily developing markets. This geographic spread matters because it means equipment suppliers cannot rely on a single demand engine; they must calibrate product portfolios, service networks, and application expertise to reflect regional priorities ranging from logic and memory scaling to specialty compound semiconductor processing.
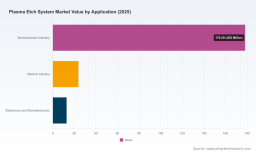
By technology type, inductively coupled plasma systems dominate the installed base, reflecting their versatility across a broad range of etching and surface treatment tasks. Reactive ion etching and deep reactive ion etching solutions occupy smaller but strategically important niches, particularly where vertical sidewall profiles, high aspect ratio features, or specialized throughput requirements dictate the choice of platform. On the application side, the semiconductor industry remains the dominant destination for plasma etch systems, with medical device manufacturing and electronics and microelectronics applications representing meaningful but comparatively smaller revenue pools. This concentration underscores a simple reality: semiconductor roadmaps continue to pull the bulk of investment and innovation, but adjacent sectors are increasingly willing to invest in tailored plasma processing capabilities when the performance argument is clear.
Dry Etching Equipment Market
Several structural challenges are testing the resilience of supplier strategies and buyer planning:
- Regulatory tightening around etch gases and chamber emissions. Environmental mandates are moving from aspirational targets to enforceable reduction pathways. In the United States, the EPA's AIM Act sets aggressive production and consumption reduction goals for hydrofluorocarbons over a fifteen-year horizon, directly affecting the use of gases common in plasma etch processes. In Europe, F-gas regulations are compressing allowable emissions of HFCs and hydrofluoroolefins, with targets to cut emissions to two-thirds of 2014 levels by 2030. These policies are not abstract: utilities and fabs are increasingly scrutinizing system-level emissions, and chamber clean configurations that reduce CF4 generation through remote plasma retrofits are already demonstrating measurable reductions against earlier emission factors.
- Specialty gas supply volatility and input cost pressure. High-purity specialty gases essential to plasma etch processes continue to face supply chain friction in key regions, where limited domestic production amplifies price sensitivity. Helium, a critical gas used in plasma etching, has experienced price volatility with costs rising by more than fifty percent over the past two years. For equipment and flip-to-play service providers, this translates into procurement risk and margin pressure that must be managed through contract structures, yield optimization, and system efficiency improvements rather than simple pass-through pricing.
- Performance expectations at advanced nodes and packaging complexity. As feature sizes continue to shrink and 3D architectures proliferate, etch systems must deliver tighter control over profile, selectivity, and variability while maintaining throughput. Buyers are increasingly unwilling to accept trade-offs that slow cycle time or compromise yield; at the same time, they demand greater flexibility to handle diverse materials, including compound semiconductors and advanced packaging substrates. This pushes suppliers to balance deep specialization with adaptable platform architectures.
These challenges are not isolated headwinds; they are reshaping the basis of competition. Suppliers that treat regulatory compliance and gas efficiency as afterthoughts risk being penalized by procurement criteria and operating economics. Conversely, those that embed low-emission chamber designs, robust gas management, and predictable consumable strategies into their platforms are creating a more durable value proposition.
Forces Shaping the Next Phase of Growth
Several drivers are converging to determine how the market expands over the forecast period, and each carries distinct implications for product roadmaps, customer engagement, and capital allocation.
Technology innovation and system-level differentiation. The pace of advancement in plasma etch tools is increasingly defined by how well platforms integrate precision, repeatability, and process flexibility. Recent product introductions point toward a clear emphasis on single-wafer capability, high-temperature processing, and surface treatment enhancements that address both front-end patterning and back-end passivation or cleaning. One notable example is the introduction of a single-wafer Aqua Plasma system alongside a 700°C high-temperature PECVD system for etch applications, signaling a push toward platforms that can support demanding thermal profiles and advanced surface engineering in tighter footprint configurations. Exhibit showcases at industry events further reinforce this trajectory, as suppliers highlight etching and surface treatment advancements that map directly to next-generation device architectures.
For buyers, the implication is that best-in-class is no longer a single metric; it is a combination of etch uniformity, sidewall quality, temperature control, and compatibility with a growing library of materials. Suppliers that can demonstrate measurable improvements in these dimensions, while minimizing rework and consumable consumption, are better positioned to command premium positioning and longer replacement cycles.
Policy and regulatory dynamics as a design constraint and differentiator. Environmental regulation is evolving from a compliance checkbox into a design parameter. The mandated reduction targets for HFCs and associated gases compel equipment developers to reconsider how chamber cleans, gas delivery, and remote plasma configurations affect both process performance and emissions. Practical experience already shows that retrofitting chamber cleans to remote plasma systems can reduce CF4 generation by more than thirty-five percent, providing a tangible example of how system design choices translate into regulatory alignment and potential total cost advantages over the lifecycle of the tool.
Semiconductor Etch Equipment Market
This matters for strategy because it creates two reinforcing opportunities: first, differentiation through lower-emission, more efficient plasma architectures that reduce operating risk for fabs; second, value creation through service models that help customers sustain compliance while maintaining throughput. Companies that treat these mandates as innovation drivers rather than constraints can convert regulatory pressure into competitive advantage, especially in markets where environmental due diligence is increasingly integrated into procurement decisions.
Demand-side shifts across semiconductor and adjacent applications. The semiconductor segment continues to be the central engine of demand, fueled by advanced logic and memory roadmaps and the expansion of advanced packaging. At the same time, medical and microelectronics applications are building their own cases for plasma processing, where surface modification, cleanliness, and reproducibility directly affect product quality and regulatory conformance. Demand is also becoming more application-specific: rather than uniform growth across all uses, certain workflows require tailored etch chemistries, smaller lot sizes, or pilot-line flexibility before commitment to full production. This is reshaping how suppliers think about platform modularity, service responsiveness, and application engineering support.
Supply chain and cost structure recalibration. The volatility in specialty gases, combined with the need for high-purity inputs and reliable consumables, is prompting a broader reckoning with cost structures. Equipment buyers are increasingly focused on total cost of ownership rather than sticker price, weighing factors such as gas utilization efficiency, uptime, chamber life, service coverage, and the predictability of consumables spend. Suppliers are responding with a mix of engineering improvements and commercial flexibility, including refurbished and custom configurations, pilot-line and production-oriented variants, and partnerships that extend capabilities across the value chain.
One relevant development is the collaboration between a leading plasma etch provider and a quantum manufacturing initiative to enable scalable quantum manufacturing via plasma processes. This kind of partnership illustrates how demand can emerge from new application domains and how incumbents can extend relevance by aligning process expertise with frontier fabrication needs, rather than relying solely on incremental improvements within established segments.
Competitive Positioning and the Evolution of the Field
The competitive landscape is a mix of specialized suppliers, regional experts, and large-scale equipment manufacturers, each pursuing different strategies to win share and defend positioning.
Niche and mid-tier specialists are leveraging deep application knowledge, customized configurations, and flexible commercial terms to serve customers with narrower process requirements or pilot-line needs. One U.S.-based manufacturer focused on plasma cleaning, etching, stripping, ashing, and reactive ion etching systems for surface preparation and modification, including custom and refurbished models, exemplifies a strategy built on applicability breadth and optionality. Another provider delivering premium wafer-based plasma etch, deposition, and advanced packaging equipment for microelectronics manufacturing emphasizes high-quality, application-focused platforms that map to demanding production requirements. A U.K.-based supplier known for advanced plasma etch systems including silicon, dielectric, and compound semiconductor etching and dicing platforms has built a reputation around specialized process capability and platform families tailored to specific materials and workflows. A Japanese developer and manufacturer of deposition, etching, and surface treatment systems, including plasma-enhanced ALD and high-temperature PECVD tools, has leaned into process integration and thermal capability as a point of differentiation. A U.S. manufacturer of plasma etch, strip, and deposition systems for semiconductor applications, and a French provider of plasma etch and deposition equipment with a focus on pilot-line and production systems, both reflect strategies oriented toward practical deployment flexibility and customer-specific adaptation. A Korean supplier of plasma etching equipment for semiconductor fabrication processes adds a regional processing strength, while the recent demonstration focus on etching and surface treatment advancements further signals continued investment in showcasing process maturity.
On the other side of the field, major equipment manufacturers with plasma etch systems integrated into advanced node fabrication lines and global chip fabrication and advanced packaging portfolios bring scale, broad material coverage, and deep integration with overall manufacturing ecosystems. A global supplier with plasma etch systems for chip fabrication and advanced packaging, and a developer of dry etch systems for advanced logic and memory device fabrication, illustrate how scale players compete on breadth, roadmap alignment, and the ability to support high-volume manufacturing with consistent process control. A Japanese producer whose equipment is integrated into advanced node fabrication lines underscores the importance of alignment with leading-edge ramp scenarios and yield-critical processing.
The resulting competitive dynamics are evolving along several axes:
- Differentiation through application depth. Specialists are competing on process fit, customization, and responsive engineering for specific materials and workflows, which can be especially valuable in compound semiconductors, advanced packaging, and smaller-volume medical or microelectronics applications.
- Differentiation through scale and integration. Large players are competing on platform reliability, throughput, global service footprint, and the ability to address the most demanding high-volume logic and memory production environments.
- Commercial flexibility as a strategic lever. Refurbished and custom models, pilot-line configurations, and partnership-enabled expansions are increasingly used to broaden addressable demand and reduce barriers to adoption, particularly in cost-sensitive or emerging application segments.
- Ecosystem alignment and new application gateways. Collaborations aimed at scalable quantum manufacturing and other frontier domains indicate that incumbents are seeking growth vectors beyond traditional semiconductor etch, using process expertise to enter adjacent high-value fabrication domains.
Market concentration, as measured by leading competitor shares, remains moderate, reflecting a field where value is distributed across multiple capable suppliers rather than dominated by a single platform family. This is important because it means competitive outcomes will be determined less by raw scale alone and more by how effectively each supplier can match product, service, and commercial flexibility to customer needs across a widening set of applications and geographies.
Looking Ahead: Three Trends Shaping the 2026 to 2032 Horizon
Based on the interplay of technology roadmaps, regulatory trajectories, and cost dynamics, several forward-looking trends are likely to define the next phase of market development.
Trend one: process efficiency and emissions control become core purchasing criteria. As regulatory reduction pathways tighten and input costs remain sensitive, buyers will increasingly evaluate plasma etch platforms on lifecycle emissions, gas utilization, chamber clean efficiency, and serviceability, alongside traditional metrics of profile quality and throughput. Systems that demonstrably lower emissions, reduce specialty gas dependence, and simplify compliance maintenance will gain traction, particularly in regions with strict environmental frameworks and in fabs managing multiple process gases across demanding schedules. The commercial opportunity here is twofold: for suppliers, it opens the door to design-led differentiation and value-added service packages; for buyers, it can translate into lower operating risk and more predictable long-term economics.
Trend two: platform modularity and application breadth will determine addressable demand. The widening range of applications, from advanced node patterning to compound semiconductors, advanced packaging, medical devices, and emerging fabrication domains, rewards suppliers that can offer adaptable architectures without abandoning process quality. Flexibility in configuration, the availability of pilot-line and production variants, and the ability to provide custom or refurbished options will become important enablers of market entry and expansion. Suppliers that combine a credible core process capability with a modular approach to add-ons, chamber options, and service modules are better positioned to capture demand from customers who need to de-risk scaling before committing to full production systems.
Trend three: partnerships and ecosystem extensions will create new growth vectors. The emergence of collaborations focused on scalable quantum manufacturing and other frontier processing needs suggests that plasma etch expertise is increasingly relevant beyond the traditional semiconductor core. For established players, partnerships can extend reach into high-value domains that demand specialized plasma control, while for suppliers with deep application knowledge, alignment with new fabrication initiatives can open routes to participate in next-generation technology scaling. This trend carries the potential for incremental revenue growth and brand reinforcement, but it also introduces execution risk: new applications require rapid learning, rigorous process validation, and close alignment with customer roadmaps that may still be evolving.
These trends imply both opportunity and uncertainty. On the upside, demand for higher-performance, lower-emission, and more flexible plasma etch systems is broad-based and likely to persist as technology nodes advance and new application sets mature. On the downside, policy implementation pace, gas supply conditions, and the timing of technology ramps can shift the rate of adoption. Buyers and suppliers alike should therefore plan for a market that is growing strongly over the horizon but where the timing and mix of demand are sensitive to external factors beyond any single company's control.
Strategic Actions for Executives, Investors, and Procurement Teams
For manufacturers and equipment suppliers, the priority is to convert regulatory and cost pressures into design and service advantages. This means continuing to invest in chamber and gas management architectures that reduce emissions and improve consumable efficiency, while building flexible product lines that span pilot-line, production, custom, and refurbished configurations. Equally important is service and application engineering: customers will increasingly choose platforms based on predictable uptime, compliance support, and the ability to adapt processes to new materials and workflows. Suppliers that align their commercial models with total cost of ownership, rather than unit price alone, will be better placed to defend margins and extend replacement cycles.
For investors, the key is to differentiate between cyclical demand and structural tailwinds. The broader market trajectory remains robust, but the distribution of value will likely skew toward suppliers that demonstrate process differentiation, regulatory alignment, and commercial agility across multiple applications and regions. Attention should be paid to signs of successful entry into adjacent application domains, evidence of emissions-reducing platform features, and the ability to manage specialty gas exposure through engineering and contractual mechanisms. Portfolio positioning should account for both the strong headline growth and the possibility that regional and application-level demand will shift at different rates.
For procurement and operations leaders evaluating plasma etch systems, the focus should broaden from specification sheets to lifecycle economics and risk management. Evaluate platforms for gas utilization efficiency, emissions profile, chamber clean strategy, service coverage, and the supplier's ability to support custom or pilot requirements without sacrificing process quality. Where feasible, structure engagements to test performance under real production conditions, and negotiate terms that align consumable and service costs with actual usage patterns. In an environment where input volatility and regulatory requirements are not going away, the most resilient buying decisions are those that balance performance with long-term operating predictability.
The strategic stakes in this market are rising as growth continues but the basis of competition becomes more demanding. Decision-makers who pair a clear understanding of the regulatory and cost environment with rigorous evaluation of process fit, flexibility, and supplier capabilities will be best positioned to extract value as the market moves toward 2032. For those seeking fully segmented data, regional and application-level detail, and customized recommendations aligned to specific investment or operational objectives, a comprehensive research report can provide the deeper granularity needed to inform precise decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Plasma Etch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com