

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Vacuum Suction Cups Market: How 6.5% CAGR and 253.5M Scale Redefine Growth

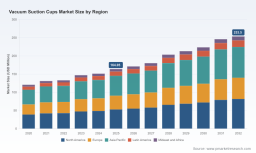
Vacuum Suction Cups Market: Strategic Trends and Business Opportunities in Automation-Driven Handling
The global vacuum suction cups market has entered a phase of steady, technology-led expansion, underpinned by consistent compound annual growth of 6.5 percent between 2020 and 2032. After a baseline period shaped by industrial recalibration and supply chain adjustments, revenue growth accelerated through the mid-2020s as automation adoption matured across discrete and process manufacturing. The market trajectory reflects a structural shift rather than a cyclical recovery: vacuum handling is increasingly integrated into core production workflows, with demand concentrated in high-throughput environments where precision, repeatability, and material compatibility are non-negotiable. This expansion is not evenly distributed across applications or materials. Instead, it is shaped by the intersection of product design innovation, regulatory expectations, and regional manufacturing priorities, creating a landscape where differentiation depends on how well suppliers align with application-specific requirements.
Beneath this growth narrative, several structural challenges define the current inflection point. First, performance expectations are rising faster than standardization, forcing suppliers to respond to highly variable surface conditions, material sensitivities, and cycle-time demands without sacrificing reliability. Second, compliance and hygiene requirements are becoming embedded in procurement decisions, particularly in food, packaging, and electronics handling, where material certification and process validation carry increasing weight. Third, the supply base is expanding in capability and geography, which intensifies competition on price and lead times while simultaneously raising the bar for technical support, customization, and integration services. These dynamics mean that market success is increasingly determined by application expertise, material science, and the ability to deliver repeatable performance in demanding environments.
Key Drivers Shaping Market Direction
Technology Innovation and Material-Specific Performance
Innovation in suction cup design and material composition is one of the most influential drivers of demand segmentation. Buyers are moving beyond generic handling components toward solutions engineered for specific substrates, surface textures, and process conditions. This is especially visible in electronics, precision assembly, and sheet handling, where mark-free contact, controlled pressure distribution, and static discharge protection are becoming baseline expectations. The expansion of specialized product families—such as ESD-focused designs for sensitive components and single-lip configurations for heavy flat objects—reflects a broader industry shift toward application-tailored handling rather than universal parts.
Worldwide Cupping Therapy Kits Market
Material selection is also shaping adoption patterns. Suction cups manufactured from silicone and nitrile-based compounds account for a substantial share of production, with silicone-based models representing a significant portion of domestic demand. Bellows-style designs remain widely used for uneven surface handling, highlighting the continued importance of geometry in achieving reliable grip across variable contours. At the same time, material grades that satisfy hygiene and process standards are gaining prominence in packaging environments, where cleanliness and compliance directly influence line design choices.
Regulatory and Hygiene Standards as Purchasing Filters
Regulatory expectations and food-safety standards have become practical filters in procurement, particularly in automated packaging lines. FDA-compliant, food-grade suction cups are no longer treated as niche accessories; they are increasingly specified where hygienic handling is essential. In meat and dairy packaging, a meaningful share of automated lines now relies on suction cups made from compliant materials, reflecting the growing importance of contamination control, cleanability, and material traceability. In packaging operations more broadly, compliance-oriented suction solutions contribute to a notable portion of consumption where hygiene requirements shape equipment specification.
This regulatory influence does more than expand a product category; it changes the buying process. Procurement teams increasingly evaluate material certifications, chemical compatibility, clean-in-place compatibility, and documentation alongside mechanical performance. Suppliers that can provide verified material compliance and application guidance gain an advantage in environments where downtime, audit risk, and line validation are costly.
Demand-Side Shifts in Automation and Line Throughput
Demand is being reshaped by the expansion of automated pick-and-place, transfer, and assembly operations across multiple sectors. Automotive assembly remains a significant application anchor, but the market is increasingly diversified by woodworking and furniture production, general industrial handling, and specialized material transfer. Two forces are especially important. The first is the push for faster cycle times with less manual intervention, which increases the share of handling tasks assigned to vacuum-based systems. The second is the need for gentler, more consistent handling of fragile or sensitive materials, which favors purpose-built geometries and material grades over generic components.
These demand-side changes are also changing how end users evaluate performance. Reliability across shift patterns, ease of integration with existing vacuum systems, and consistency across production batches are becoming as important as unit cost. As a result, buyers are increasingly willing to differentiate by specification when the application justifies it, rather than defaulting to the lowest-priced option.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures in this market are influenced by raw material availability, manufacturing precision, and the level of customization required. While commodity-style components remain price-sensitive, higher-specification solutions—especially those involving specialized materials, smaller diameters for delicate handling, or certifications for regulated environments—command different value logic. This creates a two-tier competitive environment: one shaped by volume and cost efficiency, and another shaped by technical value, integration support, and application reliability.
At the same time, suppliers are responding to lead-time and service expectations by expanding configurable options, standardizing core families, and reserving customization for cases where performance or compliance demands it. This approach helps balance flexibility with manufacturing efficiency, an important consideration in markets where demand is broad but application requirements vary sharply.
Competitive Landscape and Leading Strategies
Strategic Positioning Across the Supply Base
The competitive field includes established European and North American manufacturers, Asian suppliers with expanding configuration options, and automation-focused providers that emphasize modular integration. Leadership in this market is not defined solely by scale; it is increasingly defined by how clearly a company positions itself against application needs. Some manufacturers compete through broad reference libraries and highly configurable product ranges, enabling them to serve diverse industrial handling requirements. Others compete through specialization, such as ESD protection for electronics, food-grade compliance for packaging, or geometries designed for heavy flat objects and demanding surfaces.
This differentiation matters because buyers often evaluate suction cups not as standalone parts but as part of a handling solution. Companies that offer clear material categorization, application-specific series, and integration-friendly designs are better positioned to capture demand in environments where handling consistency and process compatibility determine purchasing decisions.
Recent Product Activity as a Signal of Direction
Recent product activity highlights where innovation is concentrated. In early to mid-2026, several suppliers introduced or expanded lines intended for sensitive handling, surface complexity, and heavy flat objects. One notable development was the introduction of an ESD-focused suction cup material designed for sensitive electronics handling, with emphasis on minimized marking and maximized static protection. This aligns with demand in battery, fuel cell, and electronic component handling, where surface integrity and electrostatic control are critical.
At the same time, a major supplier expanded its mini ESD suction cup range with smaller diameters aimed at battery, fuel cell, and electronic components, while also launching new families for demanding surface handling and single-lip designs for flat heavy objects such as glass and sheet metal. These moves indicate a dual trajectory: one toward finer handling of sensitive components, and another toward robust handling of large or irregular surfaces. The pattern suggests that product strategy is becoming more application-specific, with material and geometry treated as enablers of performance rather than interchangeable specifications.
Market Structure and Evolutionary Trends
The market remains moderately concentrated, with the largest players holding a meaningful but not dominant share of total revenue. This structure creates room for both differentiation and selective consolidation. Larger suppliers benefit from broader portfolios, integration capabilities, and established distribution relationships, while smaller or regionally focused manufacturers can compete through specialization, responsiveness, and niche application expertise.
Bra Cups Market
Looking ahead, the competitive landscape is likely to evolve along three paths. First, differentiation will increasingly depend on material certification, ESD and hygiene capabilities, and application documentation, especially in regulated or high-value handling environments. Second, integration and modularity will become more important as buyers seek components that fit cleanly into automated systems and simplify changeover. Third, regional supply dynamics will continue to shape competition, with buyers weighing local support, lead times, and configuration flexibility against price. New entrants may find opportunities in specialized materials, smaller-component handling, or regional service models, while incumbents will need to keep expanding application coverage without diluting manufacturing efficiency.
Future Trends and Commercial Opportunities
Trend One: Application-Tailored Solutions Will Outperform Generic Components
Over the next three to five years, demand is likely to shift further toward suction cups designed for specific materials, surface conditions, and compliance contexts. Generic handling components will continue to serve cost-sensitive or lower-specification applications, but higher-value demand will favor solutions that reduce mark formation, improve grip on variable surfaces, and meet electrostatic or hygiene requirements. For suppliers, this creates an opportunity to build value around application series, material grades, and configuration support rather than competing solely on volume pricing.
Trend Two: Regulated and Sensitive Handling Will Expand as a Strategic Segment
Food-grade, ESD-safe, and otherwise compliance-oriented suction solutions are expected to remain important growth vectors, particularly where automated lines must satisfy hygiene, safety, or component-integrity standards. This trend favors manufacturers that can provide verified materials, clear certification pathways, and application guidance. It also increases the strategic importance of technical sales and integration support, since specification choices often depend on line design, cleaning protocols, and handling risk.
Trend Three: Integration and Modularity Will Redefine Supplier Value
As handling systems become more tightly integrated into automated workflows, buyers will increasingly evaluate suction cups alongside connectors, mounting options, vacuum circuit compatibility, and changeover efficiency. Suppliers that design for modular integration and offer consistent families across sizes and materials can reduce engineering friction and improve total cost of ownership perceptions. The commercial opportunity lies in shifting from component sales to solution enablement, where performance, compatibility, and documentation collectively justify specification choices.
These trends carry risks. Demand may fragment across more application categories, raising complexity for manufacturers that over-standardize. Regulatory expectations may continue to evolve, requiring ongoing material validation and documentation. In addition, regional cost pressures and expanding supplier options may intensify price competition in commoditized segments, squeezing margins for players that lack application differentiation or service depth.
Strategic Actions for Decision-Makers
For Manufacturers and Product Leaders
Focus product roadmaps on application differentiation rather than broad catalog expansion alone. Prioritize material grades and geometries that address high-value handling needs, including ESD-sensitive components, heavy flat surfaces, and hygienic packaging environments. Balance configurable standard families with targeted customization to preserve manufacturing efficiency while meeting specialized demand. Equally important, strengthen application documentation and technical support so specification decisions are easier to justify inside end-user engineering and procurement processes.
For Investors and Corporate Development Teams
Evaluate opportunities based on application specificity, certification readiness, and integration capability rather than volume alone. Companies with strong positions in sensitive handling, food-grade compliance, or demanding surface applications may offer more resilient value propositions than those competing primarily on price in commoditized segments. Watch for consolidation patterns among suppliers with complementary portfolios, especially where product breadth, regional support, or material expertise can be combined to serve broader handling requirements.
For Procurement and Operations Teams
Treat specification as a risk and performance decision, not just a cost decision. Where handling involves sensitive surfaces, food contact, or high variability, prioritize material certification, mark-free performance, and compatibility with existing vacuum infrastructure. Standardize where possible to reduce changeover complexity, but preserve the ability to specify application-specific designs when process requirements justify them. Build internal evaluation criteria that include cleanability, compliance documentation, and integration fit alongside mechanical performance and unit price.
For organizations seeking a more granular view of market size by segment, regional dynamics, material and application splits, and company-level positioning, a full market research report can provide the detailed data and custom perspective needed for planning. Detailed breakdowns, scenario-based sizing, and supplier benchmarking can help translate the strategic themes outlined here into procurement decisions, product priorities, and investment theses aligned with specific operational goals.
For detailed analysis of this topic, please visit the official page: Vacuum Suction Cups Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com