

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Far Infrared Fabric Market: Why 8.01% CAGR Growth Changes Everything

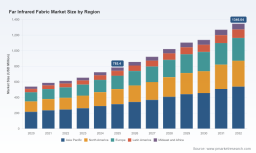
The Far Infrared Fabric Revolution: Strategic Trends and Commercial Opportunities in a $1.3 Billion Market
Market Overview: Growth Trajectory and Structural Challenges
The global far infrared (FIR) fabric market has evolved from a niche experimental segment into a substantial commercial category, demonstrating consistent expansion over the past half-decade. Valued at approximately $540 million in 2020, the market crossed the $785 million threshold in 2025 and is projected to reach $1.35 billion by 2032, reflecting a compound annual growth rate of roughly 8 percent. This trajectory signals that infrared-integrated textiles are no longer confined to emerging wellness trends but have established themselves as a viable functional material category across multiple consumer and industrial verticals.
Despite this momentum, the sector faces structural friction that separates sustainable growth from speculative hype. One pressing challenge revolves around claim validation and regulatory fragmentation. Far infrared textiles operate through emissivity mechanisms that depend on ceramic nanoparticle integration, mineral compounding, or graphene loading, but translating laboratory emissivity results into reproducible end-user performance remains difficult. Standards such as GB/T 30127-2013 are referenced in select markets, yet buyers encounter divergent certification requirements across regions. A product validated for temporary local circulation support in one jurisdiction may face entirely different claim constraints in another, forcing manufacturers to navigate multiple compliance pathways before scaling commercial rollouts.
A second challenge lies in balancing functional efficacy with cost structures. Graphene-enhanced variants and high-loading ceramic composites typically command price premiums of fifteen to forty percent over conventional performance fabrics. While melt-spinning processes can maintain mechanical stability across more than one hundred fifty wash cycles, achieving that durability requires precise compounding control and consistent polymer integration. Fabricators that underinvest in production discipline risk losing the thermal and circulatory benefits that justify the premium in the first place, eroding customer trust and margin resilience over time.
A third issue concerns market concentration and competitive differentiation. The top three participants collectively account for approximately thirty-two percent of global revenue, while the top five reach just under half of total market value. This distribution indicates a landscape where established players hold meaningful share but still leave considerable room for regional specialists and innovators. The strategic risk for incumbents is complacency in product iteration, while newer entrants must differentiate beyond ingredient marketing and prove that their FIR yarns or finished fabrics deliver measurable benefits in real-world use cases such as active recovery, thermal comfort, or sleep support.
Key Drivers Shaping the FIR Fabric Landscape
Technological Innovation and Material Breakthroughs
Materials science continues to reshape what far infrared textiles can deliver. Ceramic-infused polyester remains the dominant fiber architecture, while carbon and graphene-infused variants and bio-ceramic nylon are expanding the functional envelope. Advances in polymer nanotechnology allow manufacturers to refine mineral powders derived from gemstones, volcanic mud, or engineered ceramics and embed them more uniformly within base fibers during melt-spinning or polymerization. The result is a set of yarns and fabrics that can absorb body heat or ambient energy and re-emit it within the eight-to-twelve micrometer range, supporting perceived improvements in circulation, recovery, and thermal comfort.
Recent commercial activity underscores how material innovation is moving from R&D benches into branded product lines. In April 2025, The LYCRA Company promoted its THERMOLITE® FAR INFRARED technology for socks and legwear, emphasizing lightweight hollow fibers with permanent ceramic pigments designed to harness body infrared energy for gentle warming. This launch intersected with broader retail collaborations involving NEXT jeans and H&M collections featuring related infrared technologies, illustrating how fiber-level innovation is being translated into mainstream apparel categories rather than remaining confined to specialty therapeutic products.
Regulatory Clarity and Claim Environments
The regulatory landscape is increasingly shaping how FIR fabrics are positioned and sold. CELLIANT® infrared technology, for instance, has been determined as a general wellness product and reviewed under the FDA 513(g) process for appropriate claims regarding temporary increase in local circulation in healthy individuals. In parallel, the technology has been designated a Class 1 Medical Device in multiple markets including the EU, Japan, the UK, and Australia, with additional clearance pathways pursued in regions such as China. This layered classification structure creates both opportunity and complexity. Manufacturers that proactively align product claims with recognized regulatory categories can build stronger credibility with retailers, healthcare-adjacent buyers, and performance-focused consumers.
Simultaneously, the emphasis on third-party lab certifications and emissivity testing is becoming a differentiator in buyer evaluation. As markets reference testing protocols such as GB/T 30127-2013 and require documented emissivity performance, suppliers that invest in transparent validation can separate themselves from competitors relying on vague wellness assertions. This shift favors companies capable of supporting marketing narratives with repeatable test data and consistent production quality.
Demand-Side Shifts Across Consumer and Institutional Channels
Demand for far infrared fabrics is expanding through converging consumer and institutional behaviors. Performance-oriented consumers increasingly look for apparel that supports circulation, recovery, and thermal comfort without adding bulk or sacrificing breathability. In healthcare and therapeutic settings, textile buyers are exploring functional fabrics that can complement rest, rehabilitation, and patient comfort protocols. At the same time, home textiles and sleep-focused products are drawing interest from shoppers seeking non-invasive comfort enhancement in bedding and loungewear.
This demand diversification is visible in how manufacturers are broadening their SKU and service offerings. In May 2025, Sportingtex highlighted customizable FIR fabric options with certified technology for sportswear, health tech, and apparel, stressing OEM/ODM capabilities, sustainable production practices, and proven wellness benefits. Earlier catalog activity from other players reflects similar positioning, with FIR yarns being adapted for athletic wear, medical care, pet apparel, equestrian gear, and bedding. The practical implication is clear: FIR fabrics are crossing from single-purpose therapeutic niches into multi-category functional textiles, which expands total addressable demand but also raises the bar for category-specific performance validation.
Worldwide Heated Fabric Market
Supply-Side and Cost Structure Dynamics
Supply chain considerations are becoming more decisive as the market scales. Far infrared fabrics commonly incorporate ceramic nanoparticles, mineral powders, or graphene into polyester or nylon via melt-spinning or polymerization. The quality of this integration directly affects emissivity consistency, wash durability, and end-product cost. Suppliers that master compounding uniformity and process control can maintain mechanical properties across repeated laundering while preserving functional claims, whereas weaker process discipline leads to variability that undermines performance reliability.
Cost structure dynamics are also evolving as premium materials become more embedded in mainstream categories. Graphene-enhanced variants can add a substantial price premium, so commercial success depends on pairing the material upgrade with defensible value: thermal retention in cold-weather apparel, recovery support in activewear, or comfort benefits in sleep and therapeutic products. At the same time, sustainability pressures are encouraging EcoMade variants and resource-efficient manufacturing approaches, which can be leveraged as secondary differentiators when positioned carefully alongside functional performance rather than as standalone marketing claims.
PW Consulting
Competitive Landscape: Positioning, Differentiation, and Evolution
The competitive field in far infrared fabrics is diverse, spanning medical-device-aligned innovators, performance fiber specialists, and regional textile manufacturers with strong OEM/ODM capabilities. Hologenix, LLC, through its CELLIANT® technology, occupies a distinctive position by embedding a proprietary blend of natural minerals into fibers, yarns, and fabrics and by pursuing regulatory recognition across multiple markets. Its status as a Class 1 Medical Device in the EU, Japan, the UK, and other regions provides a credibility anchor, while its focus on performance, recovery, and sleep applications gives it relevance in both wellness and athletic recovery segments.
The LYCRA Company differentiates through THERMOLITE® FAR INFRARED fiber and technology, using lightweight hollow fibers with permanent ceramic pigments to deliver gentle warmth in legwear, socks, hosiery, activewear, denim, and outerwear. Its emphasis on permanent warming performance and sustainability-oriented EcoMade variants reflects a strategy that pairs functional benefits with mainstream apparel compatibility. Hitek Textile Co., Ltd. takes a different approach, specializing in SiTEX® FIR Yarn and related jacquard, lace, and tricot knit fabrics that use over twenty natural minerals refined with polymer nanotechnology for energized resonance effects, while offering patented yarn and OEM/ODM services for global brands.
Regional manufacturers such as NUREL Synthetic Fibers, Sportingtex, Acelon, and FIRBEST Co., Ltd. illustrate how localized expertise can translate into strong category niches. NUREL produces NERIDE FIR PA6 nylon yarn with gemstone mineral additives aimed at sportswear, therapeutic clothing, sleepwear, and cold-weather use. Sportingtex manufactures far infrared thermal fabrics using ceramic nanoparticles with emissivity values in the 0.83–0.92 range, serving sportswear, medical care, petswear, equestrian applications, and bedding. Acelon supplies AceVitality® medical yarn with far-infrared microelements for healthcare, sports, and rehabilitation textiles with antibacterial and FIR benefits, while FIRBEST produces KODENSHI® functional material with patented compounding technology across multiple countries.
Larger industrial players also participate in the space. Hyosung Corporation develops aerogear far-infrared yarn with embedded minerals for blood circulation benefits, combined with moisture management in polyester yarns. RadiciGroup offers Radilon® Enjoy polyamide fabrics with far-infrared emission properties for energy and wellness benefits, and Energy Textiles, LLC manufactures Radiance™ far-infrared textiles using ceramic particles in yarn to recycle body energy and support performance, recovery, and sleep products.
The strategic pattern across leading players is divergence in how they convert material science into commercial trust. Some emphasize regulatory alignment and medical-device-adjacent positioning, others prioritize fiber architecture and wash durability, and still others lean on OEM/ODM agility and application breadth. This fragmentation is likely to evolve in two directions. First, consolidation may accelerate as larger textile and fiber groups seek to internalize FIR capabilities and reduce reliance on single-source specialty suppliers. Second, new entrants may continue to emerge around specific applications such as athletic recovery, sleep comfort, therapeutic textiles, or even pet and equine segments, where narrower use cases allow faster proof-of-value. The winners will be those that combine reproducible emissivity performance, credible claim management, and reliable production scale rather than ingredient novelty alone.
Future Outlook: Trends and Commercial Implications for the Next Three to Five Years
One defining trend over the next several years will be the migration of far infrared fabrics from specialty wellness products toward broader functional textiles with more rigorous claim discipline. As buyers in apparel, home textiles, and therapeutic channels demand third-party validation and repeatable emissivity performance, the market will likely reward suppliers that can standardize testing, documentation, and production controls across SKUs. This creates commercial opportunities for manufacturers that can offer certified, application-specific fabric systems rather than generic “infrared” labels, especially in activewear, sleep products, and medical-adjacent textiles.
A second trend is the increasing layering of functional benefits. Far infrared is rarely evaluated in isolation anymore; it is being combined with moisture management, thermal regulation, antibacterial properties, and sustainability-oriented fiber choices. This convergence opens doorways for differentiated product architectures, such as hollow-fiber warming platforms paired with FIR emissivity, or polyamide systems that blend circulation-support benefits with rehabilitation and cold-weather performance. Companies that design around benefit stacking and category-specific use cases are better positioned to command price premiums without relying solely on raw material cost justification.
A third trend involves geographic and channel expansion, particularly where regulatory pathways and testing practices are becoming more defined. Markets that emphasize emissivity standards and recognize wellness or Class 1 device frameworks can provide faster routes to retail and institutional adoption, while regions with less harmonized claim environments may require longer education cycles. The strategic opportunity lies in matching product positioning to the destination market’s validation expectations early rather than retooling claims after launch. Still, uncertainty remains. Overstatement of health benefits, inconsistent wash durability, and fluctuating raw material costs can all weaken category credibility if not managed carefully. Premium pricing also introduces exposure to consumer sensitivity in cost-conscious segments, meaning that value communication must be precise and evidence-aligned.
Strategic Recommendations for Decision Makers
For manufacturers and fabric developers, the immediate priority is to make emissivity performance and wash durability measurable, repeatable, and transparent across product lines. Investing in compounding control, third-party validation, and application-specific testing will do more to protect margins than expanding ingredient claims. Where premium materials such as graphene or high-loading ceramics are used, the value proposition should be tied to clearly defined benefits in the target application, whether that is thermal warmth in legwear, recovery support in activewear, or comfort in sleep textiles.
For investors, the most attractive opportunities are likely to emerge where companies combine credible regulatory or validation positioning with scalable production and a diversified application base. Pure ingredient novelty is increasingly insufficient; commercial resilience depends on documentation, OEM/ODM flexibility, and the ability to serve multiple channels without diluting performance consistency. Due diligence should therefore focus on testing discipline, claim management, and the durability of differentiating technologies under repeated use and laundering.
For procurement and sourcing teams, the practical move is to evaluate FIR suppliers against reproducibility and compliance readiness rather than marketing language alone. Request emissivity data, wash-cycle performance evidence, and regulatory or certification alignment relevant to the end market. Where customization matters, prioritize partners with proven OEM/ODM capabilities and a track record of maintaining functional properties across batches. Given the pace of product launches, catalog expansions, and regulatory developments across the category, timely access to detailed segmentation data, competitive benchmarks, and market-specific entry information can materially improve sourcing and investment decisions. Readers seeking deeper segmentation detail, company-level comparisons, and region-level market data may find value in the full PW Consulting market report, which provides the supporting structure needed to translate these strategic themes into operational choices.
Worldwide Infrared Massage Therapy Bed Market
For detailed analysis of this topic, please visit the official page: Worldwide Far Infrared Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com