

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Calcium Aluminate Cement Market: How Asia Pacific’s 5.2% CAGR Trajectory and Refractory Demand Reshape the Sector

Calcium Aluminate Cement Market: Strategic Trends and Commercial Opportunities in a High-Performance Materials Landscape
The Calcium Aluminate Cement (CAC) market has evolved from a niche binder solution into a strategically critical materials segment that underpins industrial durability, infrastructure resilience, and next-generation thermal applications. With global revenue expanding from approximately $1.28 billion in 2020 to $1.69 billion in 2025, and a projected trajectory to $2.38 billion by 2032 at a five-year compound annual growth rate of 5.2 percent, the sector demonstrates steady, demand-led expansion. Growth is not uniform across regions or use cases; rather, it reflects concentrated industrial adoption, shifting engineering requirements, and deliberate capacity investments by established players. For executives and capital allocators, the CAC market represents a structurally attractive but operationally complex environment where differentiation hinges on material performance, supply chain stability, and alignment with decarbonization and durability mandates.
Market Landscape and Structural Challenges
The revenue progression over the past five years illustrates a market that has recovered from earlier cyclical softness and is now entering a phase of disciplined expansion. The baseline year of 2025 anchors a forecast window extending through 2032, during which the market is expected to add roughly $690 million in incremental revenue. This trajectory reflects an industrial materials segment characterized by relatively high barriers to entry, application-specific formulation requirements, and steady replacement and retrofit demand rather than speculative volume growth. The concentration profile of the market reinforces this structure: the top three firms collectively account for approximately 43 percent of revenue, while the top five approach 60 percent. Such concentration signals the presence of entrenched technical expertise, established customer relationships, and scale advantages in specialized production, but it also leaves room for differentiated entrants and regional specialists to capture value in targeted segments.
Key Challenges and Inflection Points
Several structural pressures are reshaping how incumbents and new entrants compete. First, raw material dependency remains a persistent volatility driver. Bauxite feedstock sourcing is concentrated in a limited set of geographies, and procurement friction is a material share of supply planning complexity. Even with expectations of a modest alumina price decline in 2025, cost volatility tied to high-purity bauxite availability continues to influence margin planning and formulation economics. Second, the industry is navigating a transition in end-use engineering requirements. Steelmakers are increasingly moving toward electric-arc furnace configurations that demand alumina-rich refractory linings capable of withstanding temperatures above 1,700 degrees Celsius. This shift is not a simple volume story; it changes specification expectations, lining design assumptions, and the performance thresholds that CAC-based products must meet. Third, regulatory and standards adoption is gradually expanding the addressable use base in municipal and industrial infrastructure. The inclusion of sulfate-resistant calcium aluminate mortars in wastewater standards such as Australia’s WSA 160:2021 illustrates how specification changes can unlock new procurement pathways, but only when paired with local technical support, testing validation, and specification familiarity.
For decision-makers, these challenges translate into a clear operational mandate: growth will be captured by firms that can stabilize input costs, adapt formulations to higher thermal and chemical demands, and align with evolving standards rather than compete solely on price.
Calcined Alumina Market
Core Demand Drivers Shaping the Market
Technological Innovation and Performance Breakthroughs
Performance differentiation is becoming the primary battleground. CAC suppliers are expanding beyond commodity-grade offerings into specialized binders and refractory matrices that address longer service life, faster strength development, and greater resistance to thermal shock and chemical attack. Recent product introductions targeting improved thermal resistance and durability in steel and foundry environments reflect a broader industry push to support heavier operational loads and more aggressive process conditions. At the same time, enhanced binder portfolios are being developed for sustainable construction and high-performance refractory applications, signaling that technical Roadmaps are increasingly tied to durability, reduced maintenance frequency, and lifecycle performance. The commercial implication is straightforward: customers in refractory, infrastructure repair, and demanding construction applications are willing to pay for formulations that reduce downtime and extend replacement cycles, provided the supplier can demonstrate consistent quality and application support.
Policy and Regulatory Environment
Regulatory frameworks and technical standards are quietly re-shaping demand patterns. In wastewater and sewer infrastructure, specification changes that recognize sulfate-resistant calcium aluminate mortars create new acceptance pathways where conventional materials may underperform. Similarly, the growing adoption of thermal energy storage systems is introducing requirements for matrices that can endure hundreds of 600 to 650 degree Celsius cycles without losing mechanical strength. These are not marginal adjustments; they are design-level shifts that influence material selection at the engineering and procurement stages. For CAC producers, regulatory alignment offers a route to specification-led demand, but it also requires investment in testing, documentation, and technical collaboration with end users and engineering firms. Markets rarely move on raw material availability alone; standard-setting and certification often determine which materials become defaults in public infrastructure and industrial projects.
Demand-Side Shifts in Industrial and Infrastructure Behavior
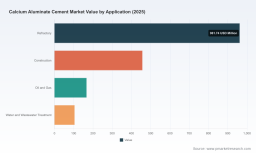
Demand is being shaped by two reinforcing behaviors. In heavy industry, there is a growing preference for materials that can withstand more severe operating conditions while reducing maintenance windows. This is evident in refractory applications, which represent the largest use segment and continue to drive volume as linings are specified for higher thermal loads and longer campaign life. In parallel, infrastructure repair and wastewater applications are increasingly valued for rapid strength gain and chemical resistance, making CAC-based binders attractive where downtime is costly or environmental exposure is significant. The construction segment, while smaller in relative terms, benefits from specialty uses where durability and fast setting are decisive. The broader message is that CAC demand is becoming more application-anchored: growth is tied to performance needs rather than generalized construction activity.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures remain influenced by feedstock concentration and the operational complexity of producing high-purity calcium aluminate products. Bauxite sourcing concentration in Guinea and China, combined with procurement challenges linked to raw-material cost volatility, keeps supply planning under scrutiny even as alumina prices are projected to ease modestly. This environment rewards companies that secure reliable feedstock arrangements, optimize energy and processing efficiency, and maintain flexibility in formulation to adapt to input cost movements. Regional capacity additions also play a role in shaping cost-to-serve. Localized production can reduce delivery lead times and improve service levels for large customers, which is particularly important in refractory and infrastructure applications where just-in-time supply and technical responsiveness can influence purchasing decisions. Cost efficiency in this market is less about absolute lowest input price and more about predictable availability, consistent quality, and the ability to serve demanding specifications without disruption.
Competitive Landscape and Leadership Strategies
The CAC market is defined by a mix of globally positioned specialists and regionally anchored producers with strong technical reputations. Leadership in this space is not determined by scale alone; it is increasingly tied to portfolio depth, application engineering capabilities, and strategic capacity deployment. Several firms have taken visible steps that highlight where the competitive frontier is moving.
Calucem has accelerated production at its New Orleans facility to meet rising demand from infrastructure and refractory applications, a move that underscores the importance of regional capacity in serving North American demand with shorter lead times and stronger local support. Imerys has expanded its calcium aluminate cement portfolio with advanced low-carbon binders for sustainable construction and high-performance refractories, reflecting a dual focus on performance and sustainability-oriented product design. Almatis introduced next-generation calcium aluminate cement products aimed at improved thermal resistance and durability in steel and foundry sectors, directly addressing the higher specification thresholds associated with modern furnace and casting environments. Cementos Molins increased R&D investment for high-performance calcium aluminate binders used in wastewater and infrastructure repair, signaling a deliberate push into specification-driven maintenance and municipal applications. In parallel, Calderys established a lightweight monolithics facility in Fulton, Missouri, increasing regional capacity by 60 percent and reducing delivery times, an example of how localized manufacturing can improve competitiveness in service-intensive segments.
Strategic Positioning and Differentiation
A few patterns emerge from these moves. First, portfolio premiumization is evident. Leading suppliers are not simply expanding volume; they are developing grades that target specific performance profiles, from high-alumina formulations to low-carbon binders and specialized mortar systems. Second, application proximity matters. Companies are investing where customer needs are most intense, whether that means refractory service for steel and foundry operations, marine and industrial flooring solutions, or wastewater and repair applications that require sulfate resistance and rapid strength development. Third, capacity is being aligned with demand geography and service expectations. Regional expansion is being used not only to increase output but also to improve responsiveness and reduce logistics friction for key accounts.
Market Structure Evolution
The market is likely to remain moderately concentrated, with room for both consolidation and targeted segmentation. Concentration at the top creates advantages in technical reputation, global supply coordination, and the ability to support large multinational customers across multiple regions. At the same time, the diversity of applications, grades, and regional standards creates opportunities for specialists that can dominate a particular use case or geography. New entrants face real barriers, including formulation know-how, qualification cycles, and feedstock access, but disruption is possible where a company brings a clearly differentiated value proposition, such as a novel binder architecture, superior cycle resistance for thermal storage applications, or a cost-effective regional supply model. The more probable evolution is not a single dominant wave of consolidation, but a continued mix of global leaders, regional specialists, and application-focused innovators competing on performance, service, and supply reliability.
Forward Outlook: Three Trends to Watch
Trend One: Specification-Led Demand in Infrastructure and Industrial Maintenance
Over the next several years, standards adoption and engineering preference shifts are expected to continue expanding CAC use in wastewater, sewer renewal, and industrial repair. The trend is not about sudden volume spikes; it is about a gradual but durable shift toward materials that meet more demanding chemical and durability requirements. Commercial opportunities lie in technical sales, specification support, and localized testing validation. Companies that invest in helping engineers and procurement teams understand sulfate resistance, rapid strength gain, and lifecycle cost advantages are better positioned to convert standards changes into recurring demand. The risk is that specification adoption can be slow and region-specific, requiring patience and sustained engagement rather than assuming immediate market pull.
Sodium Aluminate Market
Trend Two: Higher Thermal and Mechanical Performance Requirements in Refractories
As steelmaking and foundry operations adopt processes that push temperature and wear thresholds higher, refractory specifications will increasingly require alumina-rich linings and CAC-based matrices that maintain integrity under severe thermal cycling and mechanical stress. This trend favors suppliers with robust high-performance grades, consistent quality control, and the ability to support lining design and installation practices. The opportunity is to move from transactional supply to engineered solutions, where material selection is tied to campaign length, maintenance scheduling, and operational reliability. The uncertainty is that process changes can be uneven across regions and customers, and not every shift translates into immediate demand for premium grades if economics or operating strategies change.
Trend Three: Regional Capacity and Supply Chain Resilience Becoming Competitive Advantages
Given feedstock concentration and cost volatility, regional production and supply reliability are becoming differentiators rather than optional efficiencies. Near-customer capacity reduces delivery risk, supports large project timelines, and strengthens relationships with buyers who prioritize service continuity. Over the next few years, competitive advantage will increasingly accrue to companies that can combine formulation expertise with dependable supply and favorable cost-to-serve. This does not require universal scale; it requires strategic placement of capacity, disciplined feedstock management, and operational flexibility. The downside is that capacity additions and feedstock strategy carry capital and execution risk, and overinvestment in one region can leave a company exposed if demand patterns shift or input costs behave unexpectedly.
Strategic Implications for Decision-Makers
For Manufacturers and Suppliers
Focus on performance differentiation and application closeness rather than competing primarily on base commodity pricing. Develop and document grades that address specific high-value needs, such as higher thermal resistance, sulfate resistance, rapid strength development, and improved cycle durability for thermal storage environments. Invest in technical support and qualification assistance so that specification changes translate into actual adoption. Build feedstock and production strategies that reduce exposure to raw-material volatility while preserving the ability to serve key regions with shorter lead times. Consider targeted capacity additions where service levels and regional demand justify the investment, but avoid expanding without clear application pull and customer commitment.
For Investors and Capital Allocators
Evaluate CAC exposures through the lens of application mix, feedstock security, and regional service capability rather than headline market size alone. Segments tied to refractory performance, infrastructure repair, and specification-driven wastewater applications offer durable demand characteristics, but returns depend on execution, formulation leadership, and cost discipline. Watch for signals such as R&D emphasis on low-carbon binders and high-performance grades, localized capacity expansions, and standards adoption that broaden the specification base. Be mindful of concentration risk in feedstocks and the potential for margin pressure if input volatility persists despite easing alumina prices. The most resilient business models will likely be those that combine technical differentiation with dependable supply and the ability to serve demanding customers in multiple geographies.
For Procurement and Engineering Leaders
Treat CAC selection as a lifecycle decision rather than a transactional purchase. Where applications involve chemical exposure, thermal cycling, fast turnaround requirements, or long service life expectations, evaluate total cost of ownership including downtime, maintenance frequency, and replacement risk. Engage early with suppliers that can provide specification support, testing data, and application guidance, especially in projects governed by evolving standards or demanding operating conditions. Secure supply commitments where continuity matters, and consider regional sourcing options that reduce delivery risk for critical infrastructure and industrial maintenance programs. Procurement choices made with performance and reliability in mind can materially affect operational outcomes over the life of an asset.
Conclusion
The Calcium Aluminate Cement market is entering a phase where growth is increasingly tied to performance requirements, specification acceptance, and supply reliability. Steady revenue expansion toward the end of the decade reflects the material’s role in refractory durability, infrastructure resilience, and specialized industrial applications, but realizing commercial advantage requires more than exposure to a growing market. It demands formulation leadership, disciplined feedstock strategy, regional service capability, and the ability to convert engineering and standards shifts into qualified demand. For organizations operating in or adjacent to this space, the most valuable next step is to move from broad market awareness to precise segmentation, application-specific economics, and region-level supply strategy. Detailed segmentation data, regional breakdowns, and tailored strategic recommendations can sharpen those decisions and support more confident planning in a market where performance, standards, and supply chain resilience increasingly determine who captures value.
For detailed analysis of this topic, please visit the official page: Calcium Aluminate Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com