

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Medical Beauty Hyaluronic Acid Injection Market: 9.4% CAGR and Strategic Shifts Redefining Global Growth

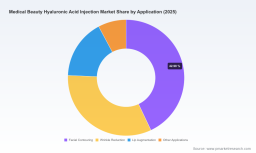
The Worldwide Medical Beauty Hyaluronic Acid Injection Market: Strategic Trends and Commercial Opportunities
At $6.45 billion in 2025, the global medical beauty hyaluronic acid injection market has transitioned from a niche aesthetic niche to a core pillar of the broader wellness and anti-aging economy. Over the past five years, steady expansion has been driven by rising disposable incomes, aging demographics, and the normalization of minimally invasive procedures. Forward projections indicate the market will approach $12.08 billion by 2032, reflecting a compound annual growth rate of 9.38 percent. This trajectory signals sustained demand, but it also underscores a landscape that is maturing rapidly. Growth is no longer solely a function of volume; it is increasingly shaped by product differentiation, regulatory navigation, and the ability to balance clinical performance with patient expectations. For executives and investors, the next phase will reward those who can read structural shifts rather than simply track headline numbers.
Navigating the Current Landscape: Scale, Shifts, and Pressures
The market today operates at a scale that commands strategic attention across multiple geographies and business models. Growth has been broad-based, but the composition of that growth is uneven. Regions with established aesthetic treatment cultures continue to anchor demand, while emerging markets are accelerating adoption through expanding clinic networks, rising middle-class spending, and greater access to trained practitioners. At the same time, the competitive field is consolidating around a small group of companies that collectively hold a majority share of the market. This concentration reflects the capital intensity of development, the importance of regulatory track records, and the value of established distribution relationships. Yet concentration does not guarantee uniform success; it raises the bar for differentiation and operational execution.
Three structural pressures are reshaping how companies compete and how purchasers evaluate options. First, the distinction between clinical credibility and aesthetic preference is narrowing. Patients and providers increasingly expect injectables that deliver visible results while preserving natural movement and minimizing downtime. Products that cannot articulate a clear positioning around longevity, integration, or dynamic tissue compatibility face margin pressure and substitution risk. Second, regulatory pathways are becoming more granular. Approval in one market does not automatically translate into commercial traction in another, and indications, labeling, and post-market expectations vary enough to affect launch sequencing and inventory strategy. Third, the raw material layer is tightening. Medical-grade hyaluronic acid is no longer a commodity input; pricing dispersion, availability, and quality thresholds are reshaping cost structures and forcing manufacturers to make deliberate choices about sourcing, formulation, and scale.
These pressures are not abstract. They influence pricing power, portfolio design, channel strategy, and the pace at which new entrants can establish a foothold. The market is large enough to absorb multiple winners, but it is also selective enough to marginalize undifferentiated offerings. The companies that thrive will be those that treat these dynamics as design constraints rather than background noise.
Core Drivers Reshaping the Market
Several forces are converging to redefine growth patterns and competitive advantage. The first is technical innovation in product architecture. The industry is moving beyond volume restoration alone toward formulations engineered for specific tissue environments and treatment goals. Differences in crosslinking, particle characteristics, and rheological behavior are increasingly used to signal fit for distinct clinical scenarios, from deep structural support to fine line correction and dynamic facial areas. This evolution is visible in how leading portfolios are positioned and in the scientific discourse at major aesthetic congresses, where manufacturers are emphasizing natural movement, integration, and long-term performance as key value propositions. The strategic implication is clear: innovation is shifting from broad claims to targeted clinical utility, and that shift changes how products are priced, prescribed, and adopted.
PW Consulting
The second driver is the regulatory and approval environment. Approval momentum has broadened the menu of available options and expanded the set of treatable indications. Recent approvals have included new hyaluronic acid gels for dynamic wrinkles and folds, as well as expanded indications for existing products in areas such as temple hollowing and infraorbital hollow. These developments matter because they do more than add SKUs; they alter treatment protocols, support practitioner education, and create new commercial pathways. For manufacturers, regulatory progress can unlock revenue faster than product development alone, but it also requires disciplined launch execution and clear communication around appropriate use. For clinics and buyers, a wider approved set of products can improve access and choice, while also increasing the need for training and protocol alignment.
The third driver is demand-side behavior. The consumer base has become more informed and more selective. Patients are comparing outcomes, longevity, downtime, and provider expertise rather than treating injectables as interchangeable commodities. This maturity is reinforced by the visibility of treatments on social platforms, the growth of reputable clinic networks, and a broader cultural shift toward preventative and maintenance-oriented aesthetics. For businesses, the implication is that marketing and sales cannot rely on category awareness alone. Differentiation must be supported by clinical data, consistent practitioner experience, and post-procedure credibility. Providers, in turn, are gravitating toward products and platforms that help them manage expectations, reduce complication risk, and maintain repeat demand.
The fourth driver is the supply-side and cost structure, especially around raw materials. Medical-grade hyaluronic acid now spans a wide price range depending on molecular weight, purity, and endotoxin limits, and the underlying raw material market is expanding as demand rises. In parallel, the commercial standard has shifted toward non-animal microbial fermentation-sourced HA for regulated applications, reducing variability and contamination risk but also consolidating the supplier base around manufacturers that can meet stringent quality requirements. This transition has two consequences. It raises the importance of supply reliability and technical control, and it gives an advantage to companies that can stabilize cost inputs while maintaining product performance. For vertically integrated players, raw material capability can become a source of margin resilience. For others, it becomes a negotiation and risk management priority.
Competitive Landscape and Leading Strategies
The market is anchored by a set of established companies that have built recognition around distinct product families, indications, and clinical narratives. AbbVie, through its JUVÉDERM collection, continues to use volume restoration and facial contouring as a foundation while pushing a more advanced narrative around undetectable, natural-looking outcomes in dynamic facial areas. Galderma has reinforced the Restylane portfolio with NASHA and OBT technology and has recently advanced syringe technology across facial and hand indications, improving handling and treatment consistency. Merz markets the Belotero range with an emphasis on integration into facial tissue for moderate to severe wrinkles and folds, while Teoxane has built its RHA collection around resilient formulations designed for natural movement. Each of these players has chosen a different point of emphasis, reflecting the reality that success depends on more than scale alone.
The field also includes companies using regulatory approvals and targeted launches to gain traction. Evolus introduced the Evolysse collection for dynamic facial wrinkles and folds after securing approval, creating an entry point into the U.S. market with a defined clinical focus. Hugel supplies fillers for global aesthetic markets and has continued to expand its international presence. Bloomage and LG Chem represent manufacturers with strong material and product capabilities, while Shanghai Haohai, HTL Biotechnology, and several other suppliers contribute to a broader ecosystem spanning raw material production and finished devices. This mix shows that the market supports both brand-led portfolio strategies and material-focused supply models, depending on capital, regulatory readiness, and geographic ambition.
Latest developments reinforce how competitive dynamics are playing out. At the 2026 Aesthetic & Anti-Aging Medicine World Congress, AbbVie framed the next phase of HA injectables around an “Undetectable Era,” signaling a shift toward outcomes that resist visible overcorrection. Galderma secured approvals across the EU, U.S., and Canada for a new Restylane syringe for use with its NASHA lidocaine range, an operational improvement that can affect clinician adoption and treatment workflow. Separately, Waldencast entered the U.S. market after FDA approval of Obagi saypha MagIQ, and Evolus launched Evolysse Form and Smooth following FDA approval, illustrating how approvals and launches are opening entry points even in a concentrated market. These moves suggest that incumbents are defending share through evolution and that new entrants are pursuing focused, indication-led openings rather than broad disruption.
The landscape is likely to continue splitting between consolidation and specialized entry. Consolidation favors companies that can combine regulatory credibility, distribution reach, and portfolio breadth. But it also creates room for specialized players if they can demonstrate a clear clinical fit, manage supply and quality, and build practitioner trust. The differentiating factors will increasingly be formulation intelligence, indication alignment, delivery experience, and the ability to support training and consistent outcomes. In that environment, broad presence is useful, but precise positioning is decisive.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape strategy. The first is the continued shift from generalized fillers to indication-specific and movement-aware products. As practitioners become more selective and patients more educated, formulations that align with tissue behavior and treatment zones will gain preference. This creates opportunities for companies that can demonstrate differentiated performance in defined clinical scenarios and that can support training, labeling, and protocol design accordingly.
The second trend is regulatory-driven expansion of usable indications and product formats. As approvals add new treatment areas and as delivery features improve, the addressable use cases will widen. That growth is commercially valuable, but it also introduces complexity in education, inventory planning, and post-market compliance. Businesses that can synchronize product launches with practitioner education and clear usage guidance are more likely to convert approval momentum into sustained adoption.
The third trend is supply-side refinement. As medical-grade HA continues to move toward fermentation-based sourcing and stricter purity standards, procurement resilience and cost discipline will become more important. Companies with stable material access and consistent quality will have an advantage in pricing and launch reliability, especially if raw material pricing remains variable. This also means that vertical integration, long-term supplier relationships, and formulation control will be increasingly strategic rather than optional.
These trends carry both opportunity and risk. Demand appears durable, but growth can be uneven across markets, indications, and provider types. Regulatory success does not guarantee commercial success if launch execution, education, and distribution are weak. And while innovation creates premium positioning potential, over-segmentation can complicate supply and slow scale if portfolios become too fragmented. The most resilient strategies will balance clinical specificity with operational simplicity.
Hyaluronic Acid Market
Strategic Actions for Decision-Makers
For manufacturers and brand owners, the priority is to sharpen product positioning around clear clinical use cases and to align formulation, delivery, and education with those use cases. A focused portfolio that maps to practitioner needs and patient expectations is more likely to defend pricing and build repeat use than an undifferentiated expansion strategy. Equally important is supply resilience: securing predictable access to medical-grade raw materials and maintaining quality control should be treated as a competitive capability, not just a procurement task.
For investors, the opportunity lies in identifying companies with credible regulatory records, defensible formulation or delivery advantages, and realistic launch execution plans. Market growth is strong, but returns will depend on execution quality, concentration dynamics, and the ability to convert approvals into uptake. Due diligence should therefore weigh indication strategy, supply security, and go-to-market discipline as closely as headline market size.
For clinics, procurement teams, and treatment providers, the practical imperative is to standardize evaluation around outcomes, safety, handling, and indication fit rather than price alone. Selecting products that match the intended treatment zone and supporting them with consistent training can reduce variability and improve patient satisfaction. On the purchasing side, building relationships with suppliers that demonstrate quality consistency and launch reliability will help manage supply risk as the market matures.
Hyaluronic Acid Dermal Filler Market
As the market scales toward the $12 billion range by 2032, the strategic edge will belong to organizations that can integrate technical differentiation, regulatory execution, and supply discipline into a coherent commercial model. For decision-makers seeking deeper segmentation data, competitor benchmarks, and tailored planning inputs, the full PW Consulting research report provides the detailed breakdown needed to translate these trends into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Beauty Hyaluronic Acid Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com