

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Hydraulic Fracturing Machine Market Poised to Hit USD 29,530.95 Million by 2032, Rising at a 4.85% CAGR Over 2026–2032
By pmarketresearch, 2026-07-17
Hydraulic Fracturing Machine Market — Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest Hydraulic Fracturing Machine Market study establishes a clear growth arc for the industry as operators, service companies and OEMs navigate tighter emissions targets, rising input costs and accelerating electrification. On a macro basis the global hydraulic fracturing machine market (base year 2025) is estimated at USD 21,200 Million, expanding to approximately USD 22,268 Million in 2026 and tracking toward roughly USD 29,531 Million by 2032 at a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. These headline numbers provide an unambiguous mandate: the sector is growing, but growth is uneven and sensitivity to cost, regulation and technology adoption will determine winners and losers in 2026 and beyond.
Hydraulic Fracturing Machine Market
Why this report matters to boardrooms and strategy teams in 2026
- Translate headline growth into capital prioritization: where to deploy CapEx for highest return and lowest technical/market risk.
- Prepare procurement and supply-chain playbooks to insulate projects from tariff-driven input-cost pass-throughs.
- Align product roadmap, fleet composition and service models with accelerating adoption of electric and natural-gas-powered frac fleets.
- Identify M&A, JV and partnership targets that deliver immediate capability (e.g., e-frac, low-emission engines, digital closed-loop operations).
- Design scenario-driven resilience plans for regulatory shocks and commodity-cycle volatility through 2032.
Market trajectory and strategic implications
From a recovery beginning in the early 2020s to the stabilization observed in 2024–2025, the fracturing machine market has returned to constructive growth. The trajectory from USD ~14.25 billion in 2020 to USD 21.2 billion in 2025 underscores the resurgence of stimulation activity and fleet modernization. The modest but steady CAGR of 4.85% projected for 2026–2032 indicates a maturing market: demand is not exploding, but it is persistent and receptive to technological differentiation.
Hydraulic Fracturing Machine Market
Strategic implication: growth will reward differentiated offerings—machines and service models that reduce lifecycle operating costs (emissions, fuel, maintenance), improve uptime through automation, and lower unit well costs. Generic product portfolios will face margin pressure as customers increasingly value TCO (total cost of ownership) rather than first-cost.
Hydraulic Fracturing Machine Market
Supply chain and input-cost dynamics: what to expect in 2026
Two structural headwinds are shaping vendor economics in 2026: trade policy and raw-material price volatility. U.S. Section 232 tariffs on steel and aluminum, which increased to elevated levels in 2025, continue to pressure the bill-of-materials for trailers, fluid ends and structural components. Steel prices remained elevated into early 2026 (reported at around USD 1,041/ton in April), directly affecting pump housings, frames and pressure-piping costs.
- Actionable mitigations for OEMs and fleet owners: implement hedging strategies for long-lead steel purchases, lock multiyear supply agreements with domestic mills where feasible, and evaluate design changes that reduce steel intensity without compromising reliability.
- For operators: re-negotiate service contracts to include cost pass-through triggers and incentivize fleet modernization programs that lower fuel and maintenance exposure.
- For financiers: stress-test CapEx cases for 10–15% input-cost volatility and require contingency funding for supply dislocations during procurement windows.
Technology evolution: electrification, gas-drive and digital closed-loop operations
2025–2026 marked an inflection in technology adoption. Two parallel shifts are critical: transition toward electric (e-frac) and large-displacement natural gas-powered fracturing fleets to cut diesel dependency and emissions, and the rapid maturation of digital closed-loop platforms for autonomous and optimized stimulation.
- Electric and gas-drive platforms materially reduce OPEX and site emissions; early deployments and partnerships (e.g., Liberty Energy’s collaboration on variable-speed natural-gas engines) demonstrate feasibility at scale.
- Digital closed-loop and autonomous systems—represented commercially by platforms showcased by major service providers—promise to reduce non-productive time and to enable predictive maintenance regimes for pressure-pumping fleets.
- Action items for 2026: run two parallel pilots—(1) retrofit a small fleet to electric/gas-drive for a full-season cost and emission trial; (2) integrate a digital closed-loop control stack with one operator’s realtime telemetry to quantify production uplift and service cost reductions.
Competitive landscape — what to watch in 2026
The hydraulic fracturing equipment and services market retains meaningful concentration: the top three firms account for nearly half of market activity, while the top five account for over 60%—a structural reality that shapes pricing, technology rollout speed and aftermarket dynamics.
- Halliburton (Houston): Leading with integrated service platforms and digital-first solutions. Halliburton’s ZEUS electric pumping units and the ZEUS IQ closed-loop platform indicate a strategy focused on combining hardware modernization with software-driven service monetization. Strategic path for partners/operators: secure early-access trials and co-development agreements to influence product roadmaps.
- Liberty Energy Inc. (Denver): Focused on low-emission fleets (digiFrac/digiPrime). Their partnership activity on gas-drive engines is a model for agile, lower-capex fleet refresh cycles. For investors: Liberty represents a compound play on fleet electrification and near-term diesel-displacement adoption.
- Baker Hughes (Houston): Delivers diversified frac pump line-ups and integrated surface systems, emphasizing reliability at scale. Baker’s breadth makes it a preferred vendor for large operators seeking single-source solutions.
- GD Energy Products (Tulsa): Product innovation on the pump side (e.g., High Flow Series) shows OEM-driven performance gains. Monitor product trials and component durability claims closely—extended component life is a wedge into aftermarket economics.
- ProFrac (Willow Park), NOV (Houston), GOES GmbH (Celle), Forum Energy Technologies (Houston): Each plays differentiated roles—customized fleets, high-horsepower pumpers, regional manufacturing strengths, and power-end specialization respectively. These vendors are potential targets for tactical alliances or bolt-on acquisitions to access technology niches or regional manufacturing footprints.
Recent developments to incorporate into 2026 planning
- Product launches and capability upgrades—new high-flow pump models and electric pumping units—require operators to reassess fleet replacement cycles and retrofit economics.
- Strategic partnerships (natural-gas engine development, digital services) are signaling where integration value will accrue—expect premium pricing for combined hardware+software offerings.
- Tariff and material-price trends necessitate proactive sourcing and flexible contracting. Companies that lock supply and innovate on material use will enjoy durable margin advantages.
Risk and scenario planning: recommended constructs
Successful 2026 strategies will be scenario-driven. PW Consulting recommends building three prioritized scenarios for board approval:
- Base Case (most likely): Moderate demand growth aligned with the 4.85% CAGR, steady migration to electric/gas-drive solutions, and manageable supply-chain friction with periodic cost spikes.
- Upside Case: Accelerated electrification and regulatory incentives lead to faster fleet retirements and higher demand for new-build electric frac fleets—opportunities for OEMs with first-mover advantage.
- Downside Case: Renewed tariff escalation, a sharp downturn in upstream drilling, or a commodity-price shock that defers stimulation activity—necessitates demand-flexible manufacturing and fleet redeployment strategies.
Each scenario should be tested across three tactical levers: CAPEX timing, vendor selection (own vs. outsource), and digital enabling investments. Require a two-year near-term liquidity buffer for downside conditions.
What the PW Consulting report delivers (practical outputs)
We engineered the study to be a decision-grade toolkit for 2026. Key deliverables include (excerpted):
- Top-down and bottom-up market sizing and a demand-driver model calibrated to 2020–2025 historicals and 2026–2032 forecasts.
- Unit-economics models for fleet types, with break-even curves, fleet replacement timing matrices and CapEx/Opex sensitivity dashboards.
- Supply-chain maps highlighting single-source risks, tariff exposure analyses and alternative sourcing scenarios.
- Technology readiness and adoption curve evaluations for e-frac, gas-drive and digital closed-loop systems, plus vendor capability matrices and vendor scorecards.
- M&A and partnership playbooks, including target profiles, valuation frameworks and integration checklists tailored to mid-market and incumbent service firms.
- A regulatory-impact matrix and policy watchlist that connects regional rule changes to procurement and operating-cost implications.
Note: in keeping with our “trailer” approach, core subsegment tables (regional and application splits, and per-product revenue schedules) are summarized in the report and are available through the PW Consulting portal for licensed users. We intentionally surface strategic takeaways here while preserving detailed proprietary tables for report subscribers.
Conclusion — near-term actions for 2026
For executives setting 2026 priorities, the prescription is straightforward: 1) Reassess fleet and CapEx plans through e-frac/gas-drive pilot economics; 2) Harden supply chains against tariff-driven and raw-material volatility; 3) Invest selectively in digital closed-loop capabilities that can be monetized as services; and 4) Rebalance M&A screening to favor capability acquisitions that accelerate low-emission and automation advantages.
PW Consulting’s Hydraulic Fracturing Machine Market report is designed to convert the headline growth into concrete board-level decisions—by providing transparent scenario tools, vendor comparisons and operational playbooks that translate forecasts into executable plans. For access to the full dataset, proprietary segment-level tables, and to book a strategy workshop with our fracturing-machine practice, visit PW Consulting’s report page or contact our industrial energy team.
For detailed analysis of this topic, please visit the official page: Hydraulic Fracturing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automated Marine Debris Collection Equipment Market to Surge from USD 856.0 Million in 2025 to USD 1,945.85 Million by 2032 at a 12.45% CAGR
By pmarketresearch, 2026-07-17
Automated Marine Debris Collection Equipment Market — Strategic Outlook for 2026
PW Consulting’s new market study on Automated Marine Debris Collection Equipment arrives at a crucial inflection point for coastal and inland water management. The segment has moved from niche pilots into repeatable procurement cycles: our analysis shows market value rising from a modest base in 2020 to an estimated USD 856.0 Million in 2025, and, under our core forecast, growing at a 12.45% CAGR through the 2026–2032 horizon to approach roughly USD 1.95 Billion by 2032. For public-sector program managers, corporate sustainability leads, infrastructure investors and technology OEMs, this report is designed as a practical, strategy-grade playbook for 2026 decision-making.
Automated Marine Debris Collection Equipment Market
Why 2026 Is a Pivotal Year
-
Policy acceleration: International and national policy trajectories are hardening around measurable collection and accountability targets. The UN Global Plastics Treaty negotiations and subsequent domestic implementation pathways are creating clearer obligations and funding mechanisms for collection technologies.
Automated Marine Debris Collection Equipment Market -
Funding and procurement momentum: Several governments and multilateral development banks have elevated autonomous and semi-autonomous cleanup systems in their capital programs. This is shifting projects from grant-funded pilots to competitively procured, multi-year service contracts.
Automated Marine Debris Collection Equipment Market -
Technology maturation: Advances in autonomy, low-power propulsion, and AI-based object classification are moving more deployments from proof-of-concept to operational scale—reducing unit operating costs and increasing measurable throughput per deployment.
-
Circularity and materials innovation: Recycled polymers recovered from collected waste are being reused in equipment components, reducing raw material dependency and creating new product lifecycle narratives for procurement specifications.
What the Report Delivers — Operational, Financial and Competitive Tools
The study is deliberately practical. We focus on the decisions you need to make in 2026 and the operational steps to execute them. Key deliverables include:
-
Market sizing and scenarios: A base-case and two alternative adoption scenarios (policy-driven upside and conservative adoption) with clear assumptions so procurement teams can stress-test planning horizons.
-
Procurement & contract templates: Performance-based RFP structures, service-level agreements, maintenance schedules and KPI frameworks that align vendor incentives with quantifiable collection outcomes.
-
TCO and ROI models: End-to-end total cost of ownership models, including capex, variable operating costs, lifecycle replacement schedules, and revenue/offset pathways from recycled material recovery and carbon/ESG credits.
-
Deployment playbooks: Site selection criteria, seasonality risk maps, modular fleet design guidance (mixing stationary collectors, skimmers and autonomous vessels), and stepwise scaling roadmaps from pilot to city/regional operations.
-
Technology assessment: Maturity matrices for autonomy stacks, sensor suites, energy systems and materials; vendor-agnostic evaluation checklists for interoperability and data integration.
-
Supply chain & manufacturing risk maps: Critical component sourcing analyses, lead-time stress tests and mitigation strategies including local manufacturing, parts pooling and material substitution options.
-
Financing and partnership playbook: Options for blended finance, public–private partnerships, concessional funding eligibility, and commercial leasing/as-a-service models tailored to municipal balance sheet constraints.
-
Regulatory and stakeholder map: A jurisdictional guide that matches likely procurement pathways to regulatory environments and civil-society expectations.
Competition and Market Structure — How to Read the Landscape
The segment is neither atomistic nor monopolistic. Our concentration analysis indicates a moderately consolidated supply base—enough scale to standardize best practices while leaving ample room for technology-focused entrants and local integrators. For purchasers and investors this means two practical realities: there are credible partners with proven deployment track records, and there remain opportunities to secure differentiated value via partnerships, performance contracts, and localized service offerings.
Representative vendor archetypes we profile in the report include:
-
Large-scale, river-interceptor organizations focused on high-throughput installations and system-wide programs. These players are advancing programmatic deployments and city-scale partnerships.
-
Autonomous surface vessel specialists that deliver flexible, scalable fleets for ports, harbors and riverine corridors—suited to scalable service models and modular fleet operations.
-
Low-cost, high-density surface collection units optimized for marinas and calm waterways that offer rapid deployment and community-led maintenance models.
-
Engineering firms and system integrators providing containment booms, skimmers and heavy-capacity vessels tailored for industrial port operations and ecosystem restoration projects.
We include company profiles and capability maps for leading producers and integrators, examining business model fit, deployment track records, service capabilities and strategic trajectories. Notable developments that inform our 2026 view include recent large-scale removal milestones and program expansions by established river-interceptor programs, and pilot-to-scale initiatives by autonomy-focused vendors with multilateral bank partners.
Technology and Business Model Inflection Points to Watch
-
Autonomy and sensing: Accurate classification, adaptive routing and swarming strategies materially improve throughput per deployed unit. Procurement decisions in 2026 should favor systems with upgradeable autonomy stacks rather than closed legacy architectures.
-
Energy & propulsion: Battery energy density, modular swap systems and hybrid solar assist change uptime economics. Decision-makers should insist on transparent energy budgets and life-cycle replacement costs in vendor bids.
-
Materials circularity: Designs that incorporate recycled polymers—both as a sustainability narrative and as a risk mitigation strategy against raw material volatility—deliver downstream cost and brand advantages.
-
Service models: As-a-service contracts that bundle deployment, monitoring and disposal/recycling reduce municipal procurement friction. However, they require rigorous performance verification mechanisms to prevent scope creep.
Strategic Imperatives for 2026 Decision-Makers
-
Move from pilots to procurement-ready pilots: Design pilots with procurement-ready KPIs, data collection standards and lifecycle costing so successful pilots can be contracted at scale without repeated bid cycles.
-
Prioritize data and M&V frameworks: Collection volume alone is a weak metric. Invest in standardized monitoring, chain-of-custody for recovered material, and impact reporting aligned with national and international reporting frameworks.
-
Co-design procurement with financing partners: Early involvement of development banks, blended finance providers and ESG investors can convert capital-intensive projects into affordable multi-year service agreements.
-
Stress-test supply chains: Insist on dual-sourcing strategies for critical components and evaluate vendors on the basis of their manufacturing resilience and local content strategies.
-
Lock in circular pathways: Build off-take agreements for recycled outputs into procurement mandates to create revenue offsets and support circular-economy outcomes.
-
Engage in standards development: Participating in standard-setting forums and the early implementation of interoperable data standards yields competitive advantages and helps shape procurement specifications.
How Executives Should Use the Full PW Consulting Report
The executive summary you are reading now is a strategic "trailer" that highlights the report’s core implications. The full study provides the granular decision-support tools you will need in 2026: region- and segment-level forecasts, vendor scorecards with capability matrices, detailed TCO spreadsheets and procurement templates, contract negotiation playbooks, and multi-scenario impact models. These assets enable procurement teams to build evidence-backed RFPs, investors to size and structure deals, and technology vendors to prioritize product roadmaps aligned to buyer willingness-to-pay.
To preserve strategic value and to support active procurement cycles, we have intentionally withheld full segmentation tables and in-depth vendor-by-vendor revenue breakdowns from this release. Stakeholders seeking the complete dataset, full forecast tables, and the operational toolkits should request the full report through PW Consulting’s publication portal.
Concluding Perspective
The automated marine debris collection equipment market is entering a phase in which technology capability, procurement sophistication and policy clarity converge. For organizations making 2026 decisions, the imperative is not merely to buy equipment but to design resilient programs — integrating procurement, financing, operations and downstream recycling. PW Consulting’s study provides the empirical foundation and practical toolset to convert strategic ambition into measurable outcomes.
Contact PW Consulting to obtain the complete report and the accompanying operational toolkits that will allow your organization to translate the 2026 market inflection into durable environmental and financial returns.
For detailed analysis of this topic, please visit the official page: Automated Marine Debris Collection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rubber Round Belt Market Reaches USD 1,850 Million in 2025, Poised for 4.3% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Rubber Round Belt Market — 2026 Strategic Brief (PW Consulting)
Executive snapshot
The global rubber round belt market is entering 2026 from a position of steady expansion and heightened strategic complexity. Our benchmarking model places the market at USD 1,850.0 Million in 2025, with near‑term growth lifting the 2026 estimate to roughly USD 2,013.7 Million and a compound annual growth rate (CAGR) of 4.3% across the 2026–2032 forecast window. By the end of the forecast period the industry is projected to exceed USD 2.4 billion, underscoring a predictable, investible market that nevertheless hides structural inflection points companies must address in 2026.
Rubber Round Belt Market
Why this report matters for 2026 decision cycles
-
Actionable market sizing and scenario analytics that convert a multi‑year forecast into quarter‑by‑quarter implications for supply chain, pricing and capacity planning.
Rubber Round Belt Market -
Concentration metrics that inform competitive strategy — the top tiers of suppliers account for a meaningful share of industry revenue, but the sector remains sufficiently fragmented to reward nimble players with focused execution.
Rubber Round Belt Market -
Real‑world operational levers: raw‑material exposure, regulatory certification, and product differentiation are the primary variables that will determine winners and losers in 2026.
What we found: five strategic forces shaping 2026
-
Material volatility: natural rubber pricing has shown notable short‑term swings. Independent industry measures put a benchmark near USD 1.92 per kg in February 2026, while commodity price series recorded a reading of 222 U.S. cents per kg in May 2026 — a reminder that input cost shock remains a persistent operational risk. Procurement and product teams must integrate volatile feedstock scenarios into commercial plans for 2026.
-
Regulatory and food‑grade demand: increasing adoption of rubber and polyurethane round belts in food processing elevates the importance of food‑grade certifications and hydrolysis resistance. Compliance is no longer a checkbox — it is an enabler for premium pricing and longer aftermarket life cycles.
-
Segment diversification: demand drivers span industrial machinery, conveyor systems, automotive and processing sectors. The resulting portfolio choices — whether to prioritize heavy‑duty power transmission, high‑precision conveyors or food‑safe materials — drive very different R&D and sales strategies.
-
Technology and materials substitution: thermoplastic and engineered polyurethane variants are gaining ground alongside traditional natural and synthetic rubber. Performance tradeoffs (wear, stretch, hydrolysis resistance) are now being optimized across a broader materials palette.
-
Channel and aftersales economics: service, fast‑fulfilment and local stocking are increasingly decisive for end users with uptime‑critical conveyors. Distribution strategy and aftermarket capability can materially increase lifetime value.
Competitive landscape — profiles and strategic implications
Our competitive map synthesizes strengths and strategic postures of established suppliers who will influence market dynamics in 2026. The report contains full profiles, but the following high‑level assessments highlight what buyers and investors should watch this year.
-
Gates Corporation (Denver, Colorado, USA; https://www.gates.com) — notable for heavy‑duty, OE‑exact fit offerings across power round and endless rubber belts. Strength lies in engineered fitment and aftermarket reach; strategic focus should be on cross‑selling service agreements and expanding turnkey solution packages.
-
Dura‑Belt, Inc. (Hilliard, Ohio, USA; https://www.durabelt.com) — specialist in elastic round belts and FDA‑approved urethane options. Their certification expertise positions them well for food processing and hygienic conveyor niches; partnerships with system integrators would accelerate penetration.
-
Habasit (Reinach, Switzerland; https://www.habasit.com) — offers Polycord round belts and has recent technical updates to improve industrial conveying performance. Habasit’s strength is in material science and global standards compliance; continued investment in hydrolysis‑resistant thermoplastic variants is a likely path to premium differentiation.
-
BEHAbelt (Glinde, Germany; https://www.behabelt.com) — focused on weldable PU/TPE round belts and rubber‑like profiles. Their production flexibility supports fast customization; scale expansion or strategic alliances could increase share in modular conveyor builds.
-
Optibelt Corporation (Bartlett, Illinois, USA; https://www.optibelt.com) — supplies RR/HRR series polyurethane and rubber belts across industrial sectors. Their breadth makes them a desirable supplier to multisite manufacturers; value capture will depend on integrated services and contract logistics.
-
Fenner Drives (Manheim, Pennsylvania, USA; https://www.fennerdrives.com) — offers light‑duty Eagle urethane and rubber belting optimized for material transfer. Their channel presence in light industrial and OEM replacement markets is a platform for aftermarket growth.
Recent market signals
-
Buyer's intelligence: a recent third‑party buyer’s guide released in March 2026 highlighted top suppliers and underscored demand for certified rubber options in industrial applications, reflecting buyer focus on risk‑mitigating attributes.
-
Product evolution: in late 2025 a leading supplier updated Polycord data sheets to boost hydrolysis and conveying performance — a market cue that incremental material improvements continue to be a primary competitive lever.
-
Market concentration: our CR3 and CR5 measures indicate meaningful concentration at the top tiers, suggesting opportunities for mid‑market consolidation but also risk of pricing pressure from larger incumbents on commoditized product lines.
What the full report delivers (practical contents for 2026 execution)
PW Consulting’s full market study is designed as a playbook for commercial, procurement and corporate development teams. The report is structured to be immediately operational and includes:
-
Transparent forecasting model with base‑year reconciliation, sensitivity runs and scenario outputs (available as downloadable models).
-
Segment and regional demand dashboards with purchase and life‑cycle assumptions to support SKU prioritization.
-
Raw‑material impact analysis showing pass‑through dynamics and cost‑to‑price elasticity under alternate commodity paths.
-
Competitive benchmark with supplier scorecards, capability heatmaps and product positioning matrices.
-
M&A and partnership target screening criteria optimized to identify accretive bolt‑on assets by capability and geography.
-
Go‑to‑market and channel playbooks for direct OEM sales, distributor partnerships and aftermarket networks.
-
Regulatory and compliance roadmap for food‑grade and hydrolysis‑resistant product lines, including cost/benefit templates for certification investments.
Strategic recommendations for 2026 — a prioritized action checklist
-
Immediate (0–90 days): Stress‑test procurement against commodity scenarios and implement a layered hedging strategy for natural rubber exposure. Reconcile supplier contracts to introduce indexation clauses or fixed volume rebates to protect gross margin.
-
Near term (90–180 days): Accelerate certification lanes for food‑grade and hydrolysis‑resistant products where existing demand and margin uplift justify capital or process investment. Pilot a stocked SKU set with top regional integrators to shorten lead times and command premium service fees.
-
Medium term (180–365 days): Execute portfolio rationalization to favor higher‑margin variants (e.g., engineered PU/thermoplastic blends and certified rubber compounds). For manufacturers, consider modularizing lines to switch between rubber and thermoplastic production with minimal downtime.
-
Strategic (12–24 months): Evaluate roll‑up or alliance opportunities for regional players that add local stocking capabilities or proprietary formulations. Use acquisition targets to plug gaps in aftermarket services and digital ordering platforms.
How buyers, manufacturers and investors should use the report
For procurement leaders: use the forecast and sensitivity analyses to reset contract terms and develop a multi‑supplier hedging playbook. For product managers: the materials roadmap and competitor scorecards will clarify where to prioritize R&D spend. For corporate development teams: the market consolidation mapping and target screening tools will accelerate identification of value‑accretive targets and joint‑venture candidates.
Closing — the PW Consulting difference
This market brief demonstrates the kinds of practical, decision‑ready insight our full report provides: a blended view of macro trajectory (USD 1,850.0 Million in 2025, rising into 2026 at approximately USD 2,013.7 Million and expanding at ~4.3% CAGR through 2032), coupled with operational scenarios and supplier intelligence that translate forecasts into executable 2026 actions. Our intent is to give you enough strategic visibility to act confidently, while preserving the granular tables, models and proprietary supplier metrics that are included in the full deliverable.
Access the complete Rubber Round Belt Market report and downloadable forecast models on the PW Consulting research portal to unlock the detailed segmentation, supplier share matrices and scenario spreadsheets that will be required to finalize budgets, procurement strategies and M&A mandates for 2026.
For detailed analysis of this topic, please visit the official page: Rubber Round Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wearable Power-Assisted Exoskeleton Robots Market Poised to Grow at 24.85% CAGR, Reaching USD 2.285 Billion by 2032
By pmarketresearch, 2026-07-15
Wearable Power-Assisted Exoskeleton Robots Market — Strategic Briefing for 2026 Corporate Decision-Makers
Market snapshot and near-term runway
By PW Consulting's assessment, the global market for wearable power-assisted exoskeleton robots reached an estimated USD 482.5 Million in 2025 (base year). With a robust compound annual growth rate (CAGR) of approximately 24.85% projected through our 2026–2032 forecast window, the market is set to scale into the low‑billions by the end of the decade. This trajectory is being driven by converging forces — accelerating clinical validation, expanding industrial adoption for ergonomic augmentation, and stepped-up product innovation in lightweight materials and embedded AI control.
Wearable Power-Assisted Exoskeleton Robots Market
Why this report matters to 2026 strategy
- Timing: 2026 is a pivot year when trial evidence, regulatory precedents and early reimbursement decisions coalesce into investable commercial pathways. Senior leaders who translate these signals into focused pilots and strategic partnerships now will capture disproportionate learning and customer mindshare.
- Prioritization: With limited deployment budgets and competition for clinical trial and industrial pilot slots, the report helps executives prioritize segments, use-cases and customer cohorts that convert fastest to recurring revenue.
- Risk-adjusted planning: The growth profile is steep, but capital intensity, integration complexity and regulatory hurdles remain. Our analysis provides scenario-based stress-testing to align investment pacing with program milestones and cash‑flow tolerances.
What PW Consulting’s Wearable Exoskeleton Report delivers
This is not a high-level market memo — the report is designed to be a go‑to operational playbook for commercial, clinical and corporate development teams preparing choices in 2026. Key deliverables include:
Wearable Power-Assisted Exoskeleton Robots Market
- Market sizing and demand curves: a detailed top‑down and bottom‑up assessment anchored to 2025 base metrics, with transparent assumptions and sensitivity checks for uptake rates, reimbursement adoption and unit economics.
- Adoption path maps: staged adoption frameworks for medical rehabilitation, industrial augmentation and defense uses, identifying typical buyer journeys, procurement cycles and integration points with existing workflows.
- Go‑to‑market playbooks: tailored commercial strategies for OEMs, startups and system integrators — covering channel models, pricing approaches, pilot design templates, and outcome‑based contracting constructs.
- Regulatory and reimbursement roadmaps: pragmatic guides through regulatory classifications, key safety controls, and payer engagement sequences; includes a repository of precedent decisions and payer coverage language templates.
- Technology and supply‑chain diagnostics: component cost drivers, sourcing risk heatmaps, and engineering benchmarks — including material and actuator trends that materially affect device mass, battery endurance and per‑unit cost.
- Vendor capability matrices and M&A playbook: in‑depth profiles, capability gaps, integration risks and a transaction scoring tool to evaluate buy vs. partner vs. build choices.
- Commercial KPIs and ROI models: downloadable financial models and clinical outcome-to-revenue conversion calculators designed for board-level decision support.
Competitive landscape — who to watch and why
The industry remains concentrated among specialized robotics and medtech firms, with the leading players capturing a substantial share of established commercial and clinical deployments. Rather than publish a static leaderboard, the report analyzes competitive vectors — technology stack, clinical evidence depth, distribution reach and channel partnerships — to show where each rival is positioned to win specific use-cases.
Wearable Power-Assisted Exoskeleton Robots Market
- German Bionic (Augsburg, Germany): pushing AI-enabled worker assistance solutions with a focus on dynamic, task‑aware support. Recent trade‑show activity and product showcases underline a strategy of close collaboration with large industrial employers to demonstrate safety and productivity gains.
- Wandercraft (Paris, France): differentiates with self‑balancing control architectures targeted at early mobilization and complex rehabilitation scenarios. Active clinical pilots in intensive care and mobility rehab mark it as a company to monitor for downstream hospital adoption.
- Ekso Bionics (San Rafael, USA): with bifurcated product lines across medical and industrial spaces, Ekso is an archetype of a firm seeking to translate rehabilitation clinic credibility into broadened enterprise solutions for worker augmentation.
- Lifeward / ReWalk (Israel / USA): remains a clinical poster‑child for personal mobility exoskeletons, with recent long‑term safety data strengthening reimbursement conversations and adoption among spinal cord injury beneficiaries.
- CYBERDYNE (Japan), Ottobock (Germany), B‑Temia (Canada), Parker Hannifin (Indego), Auxivo (Switzerland), Fourier Intelligence (Singapore): collectively these firms illustrate varied strategic postures — from bioelectric signal control to lightweight industrial devices — and form the competitive fabric that buyers evaluate for reliability, service coverage and evidence packages.
Recent, company‑level developments (e.g., clinical enrollments, trade show showcases, and the publication of long‑term safety datasets) are flagged in the report and mapped to prospective procurement triggers — enabling procurement and clinical leaders to time pilots and submissions for maximum impact.
Regulatory, reimbursement and materials dynamics
Three non‑market forces will shape 2026 decisions:
- Regulation: Established device classifications and special controls are reducing approval uncertainty in rehabilitation use-cases. Our regulatory playbook translates classification precedents into product development requirements and testing priorities.
- Reimbursement: Early payer approvals for personal exoskeletons are changing the calculus on total addressable market and unit economics. The report includes tracer cases showing how outcome metrics were translated into coverage decisions and the negotiation levers that mattered.
- Materials & components: Advances in composites, actuator designs and energy density are reducing device weight and improving usability — the report quantifies the performance thresholds (for example, contemporary engineering targets for per‑leg mass and battery endurance) that unlock broader end‑user acceptance, and maps supplier landscapes where sourcing constraints could bottleneck scale.
Technology, service and integration imperatives for 2026
Our fieldwork and interviews highlight three imperatives for winning deployments in 2026:
- Outcome‑centric device design: buyers (clinicians and industrial safety managers alike) prioritize demonstrable improvements in functional outcomes, not just technical specs. Embedding robust data capture and standardized outcome measures into devices reduces procurement friction.
- Service and ecosystem play: successful vendors are those that combine hardware with training, integration services and outcome-based contracting. Early adopters value vendors who can deliver predictable onboarding and measurable productivity or functional improvement within defined time horizons.
- Interoperability and standards: as installations grow, interoperability with electronic health records, workforce management systems and industrial safety platforms becomes a competitive differentiator. Our recommendations include concrete API and data standards adoption paths to minimize integration cost.
Actionable recommendations for executives planning 2026 moves
To convert growth projections into durable market positions, boards and executive teams should consider the following prioritized actions this year:
- Run 2–3 high‑quality pilots that embed clinical or productivity endpoints into contracts; design pilots to produce publishable evidence within 9–12 months to accelerate payer and enterprise credibility.
- Secure strategic supplier agreements for critical lightweight components to de‑risk time to scale and protect margins as demand accelerates.
- Negotiate outcome‑linked pilot terms with early enterprise customers to share upside and reduce buyer resistance; pair pilots with training and service guarantees to shorten the path to renewal.
- Invest in a centralized data and analytics capability to capture usage, safety and outcomes; these data will be the currency in payer conversations and enterprise renewals.
- Use M&A selectively to fill capability gaps (service networks, clinical trial expertise, or key IP) rather than as a substitute for building in‑house commercialization capabilities.
Why PW Consulting’s report is a unique tool for 2026
PW Consulting has combined primary interviews with device manufacturers, payers and early adopter customers, granular supply‑chain analysis, and a transparent financial model calibrated to observed procurement behaviors. The result is an executable intelligence product — not merely forecasts. Companies will find in it the templates, scenario models and negotiation playbooks needed to convert the market’s rapid growth into profitable, defensible revenue streams.
Next steps and how to access the full intelligence
This briefing is a strategic précis — the full report contains the granular segmentation, proprietary scenario models, company scorecards and downloadable financial tools that your commercial, clinical and corporate development teams can use immediately. For executives preparing board memos, pilot funding requests or M&A diligence in 2026, the report shortens time‑to‑decision and reduces execution risk.
To request a copy of the full report or to schedule a briefing with PW Consulting’s exoskeleton practice team, please follow the link on our official distribution page where you can also access executive summaries and sample model extracts.
For detailed analysis of this topic, please visit the official page: Wearable Power-Assisted Exoskeleton Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Drawer-Type Switchgear Cabinets Market Poised for 6.0% CAGR Through 2032
By pmarketresearch, 2026-07-15
Drawer Type Switchgear Cabinets Market: A 2026 Strategic Briefing for C-Suite Decision Makers
Executive snapshot
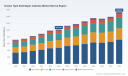
The global drawer type switchgear cabinets market is entering 2026 from a position of steady expansion and increasing strategic complexity. Our PW Consulting benchmark shows the market surpassing the one‑billion USD threshold in the base year (2025), rising to an anticipated 1.13 billion USD in 2026, and tracking to roughly 1.53 billion USD by 2032 on a 6.0% compound annual growth rate (forecast period 2026–2032). Market concentration is moderate: the largest three players account for just under 40% of the market while the top five capture roughly 53%, underscoring both global leadership and remaining room for regional or niche challengers.
Drawer Type Switchgear Cabinets Market
Why this briefing matters for 2026 decisions
- Translate macro momentum into executable plans: With predictable growth at a mid-single-digit CAGR and accelerating opportunities in data center, industrial modernization and critical power distribution, 2026 is a pivotal planning year to convert strategic intent into capacity, product and go‑to‑market moves.
- Manage margin pressure while investing for differentiation: Raw material volatility and trade policy shifts are compressing margins at OEMs. Firms that can re‑engineer cost structures and monetize higher‑value features (safety, digital telemetry, rapid serviceability) will widen competitive gaps.
- Prioritize capital allocation with optionality: Facility expansions, automation, and software-enabled product upgrades carry different lead times and return profiles. Scenario planning now reduces exposure to execution risk over the 2026–2032 horizon.
Market dynamics shaping 2026 strategy
Three structural dynamics will define the near term:
Drawer Type Switchgear Cabinets Market
- Demand composition is shifting toward modular, withdrawable drawer architectures that enable faster maintenance, safer operations and higher service revenues. Buyers increasingly favor systems that support both traditional distribution and emerging critical loads such as AI data centers.
- Input cost and policy volatility. Copper and electrical steel cost swings and targeted tariffs are elevating procurement and product‑cost risk. Organizations that implement robust raw‑material hedging, local sourcing strategies and product redesigns to reduce material intensity will protect margin.
- Consolidation and capability play. The market’s concentration metrics reflect a dual reality: established global players control a material share, yet regional OEMs and specialists retain tactical advantages in local channels and cost positions. Expect targeted M&A, JV activity and capacity plays in 2026 as incumbents shore up service footprints and niche technology stacks.
Competitive landscape: What industry leaders are doing
Our analysis of leading suppliers shows clear, differentiated strategic postures that buyers and investors should factor into their 2026 planning.
Drawer Type Switchgear Cabinets Market
- ABB (Zurich) — Platform scale and vertical integration: ABB’s investment in a major European manufacturing facility and its continued push to pair modular drawer systems with advanced breakers and digital protection positions it to capture high‑specification demand (notably AI‑ready data centers and large industrial users). Expect ABB to compete on system integrability, digital services and scale economics.
- Siemens AG (Munich) — Systems & services bundling: Siemens continues to emphasize turnkey distribution systems and lifecycle services. Their strength is in integrating switchgear into broader electrification and automation projects, which favors clients seeking single‑vendor accountability for complex installations.
- Schneider Electric (Rueil‑Malmaison) — End‑to‑end energy management: Schneider blends modular drawer‑type hardware with energy management software and service programs, enabling premium pricing for bundled lifecycle outcomes, especially in commercial and critical power applications.
- Eaton Corporation (Dublin) — Safety and power‑handling innovation: Eaton’s product innovations (e.g., rotating contact mechanisms and arc‑flash mitigation) aim to differentiate on safety, uptime and high current ratings—attributes that command warranty and service premium margins.
- Regional and specialist OEMs — China‑based suppliers and smaller global players continue to hold relevance by offering competitive pricing, rapid local delivery and customization. These vendors are often preferred for volume and retrofit work where cost and lead time are decisive.
Recent industry moves and what they imply
- Capacity investments by global incumbents signal an expectation of premium, specification‑driven demand growth (e.g., investments supporting AI‑ready data centers). For executives, this raises the bar on product development—if you want to compete at that level, your R&D and certification roadmaps must be fully funded in 2026.
- Product launches focused on higher amperage ratings, reduced arc flash risk and increased modularity indicate an ongoing migration up the value chain. Feature parity is reducing, so differentiation will come from integration of safety, digital telemetry, and proven field reliability.
- Regional OEMs’ continued strength underscores the need for layered go‑to‑market strategies—global OEMs will push platform standardization while regional players win on channel intimacy and cost agility.
Supply chain and cost pressures you cannot ignore
Raw material and trade developments are immediate tactical considerations for 2026:
- Copper and grain‑oriented electrical steel price volatility is materially impacting BOM costs and can reduce OEM margins if not mitigated. Procurement strategies must now include longer‑term contracts, formula pricing, and material‑substitution roadmaps where technically feasible.
- Protectionist trade measures and tariffs introduce localized cost differentials and may justify near‑market production or tariff‑aware sourcing. Scenario planning should evaluate the ROI of regionalizing capacity versus accepting tariff exposure.
- Supply chain resilience investments—dual sourcing, safety stock optimization, digitized supplier scorecards—deliver disproportionate value in a market characterized by intermittent commodity shocks and lead‑time variability.
Strategic imperatives for executives in 2026
Based on our scenario modelling and client advisory engagements, PW Consulting recommends five priority actions:
- Rebalance portfolio toward modular, serviceable, higher‑margin configurations. Where feasible, accelerate certifications and interoperability capabilities demanded by hyperscalers and large industrial OEMs.
- Lock in cost and supply through creative procurement: multi‑year offtake agreements, regional supplier partnerships, and design for material efficiency to offset copper/steel pressure.
- Invest selectively in factory modernization and digital test capabilities that shorten product time‑to‑market and reduce warranty exposure—especially if you target the upper end of the market spectrum.
- Use M&A and strategic partnerships to close capability gaps (digital protection, arc‑flash mitigation, aftermarket field services) rather than building all capabilities organically.
- Formalize a 2026 commercial playbook that differentiates on lifecycle economics, not just upfront hardware cost—warranty programs, performance SLAs and remote diagnostics are rapidly becoming differentiators.
What the PW Consulting report delivers (practical content)
Our full Drawer Type Switchgear Cabinets Market report is built as an operational toolkit for 2026 decision cycles. Key deliverables include:
- A validated market model with historical (2020–2025) and forecast (2026–2032) revenue series, scenario toggles and sensitivity levers that allow you to stress test assumptions across commodity, tariff and demand scenarios.
- A detailed competitive map with capability matrices, go‑to‑market archetypes and supplier scorecards to guide sourcing and partnership decisions.
- Actionable strategic playbooks: product development roadmaps, CapEx prioritization frameworks, M&A screens, and commercial pricing strategies tailored to different customer verticals and risk appetites.
- Operational templates: SKU rationalization tools, factory modernization ROI calculators, and a two‑year implementation schedule for supply chain resilience measures.
- Risk registers and mitigation playbooks covering raw‑material exposure, regulatory shocks and channel disruption—designed for board‑level oversight and auditability.
What we intentionally withheld — and why
To preserve the report’s role as the definitive source for executable detail, we have deliberately not published the granular regional and application revenue splits or the full proprietary company-level revenue breakdowns in this briefing. Those detailed segment tables, competitor revenue lines and downloadable financial models are available in the full report and are essential for transaction diligence, detailed pricing strategy and localized capacity planning.
How to use the report in your 2026 planning cycle
- CEOs & Boards — Use the scenario model to stress test strategy choices (build vs. buy; regionalize vs. centralize). Set funding thresholds for capability development and M&A screening informed by the model’s ROI outputs.
- COOs & Supply Chain — Implement procurement and sourcing playbooks immediately; use our supplier scorecards to reprioritize suppliers and restructure contracts before commodity shocks escalate.
- Product & Engineering — Prioritize modularity, safety and digital telemetry in the 2026 roadmap; leverage the report’s feature‑value matrices to optimize BOM redesign and certification sequencing.
- Commercial & Service — Reframe go‑to‑market offers around lifecycle value. Pilot bundled service agreements with selected accounts to validate pricing and operational readiness.
Final perspective
The drawer type switchgear cabinets market in 2026 presents both a continuity of steady, predictable growth and a set of accelerating strategic inflection points—material cost pressure, demand for higher‑value modular systems, and a competitive field split between global platforms and nimble regional specialists. Firms that treat 2026 as a year to reallocate capital, shore up supply resilience, and invest in differentiated product‑service propositions will enter the 2026–2032 window with optionality and defensibility.
For the exhaustive segment datasets, competitor revenue breakdowns, downloadable financial models, and a customized briefing for your management team, consult the full PW Consulting Drawer Type Switchgear Cabinets Market report on our website.
For detailed analysis of this topic, please visit the official page: Drawer Type Switchgear Cabinets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rack‑mounted Full Liquid CDU Market Poised for a 9.85% CAGR — A New Era in Data Center Cooling
By pmarketresearch, 2026-07-15
Rack-mounted Full Liquid CDU Market: Strategic Imperatives for 2026 Decision‑Makers
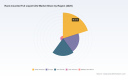
As hyperscale cloud operators, colocation providers and high‑performance compute (HPC) adopters accelerate the shift to direct liquid cooling, rack‑mounted Coolant Distribution Units (CDUs) have moved from niche enablers to foundational infrastructure. PW Consulting’s latest market study — the Rack‑mounted Full Liquid CDU Market Report (base year 2025, forecast 2026–2032) — synthesizes five years of historical data and a forward model that forecasts sustained double‑digit expansion in installed base value. The market reached USD 105.0 Million in 2025 and, under our central scenario, expands to USD 203.45 Million by 2032, representing a compound annual growth rate (CAGR) of 9.85% across the 2026–2032 forecast window.
Rack-mounted Full Liquid CDU Market
Why this report matters for 2026 strategy
-
Timing matters: 2026 is the inflection year for many operators who committed to liquid cooling pilots through 2023–2025. The window for locking in preferred CDU architectures, supplier relationships and thermal‑electrical co‑design practices is now.
Rack-mounted Full Liquid CDU Market -
Investment trade‑offs are complex: the report quantifies the tradeoffs between centralized plant scaling and rack‑level distribution, and translates thermal performance into realistic CAPEX/OPEX scenarios for next‑generation AI and HPC deployments.
Rack-mounted Full Liquid CDU Market -
Risk and compliance vectors are intensifying: updated ASHRAE guidance and testing addenda, together with supply‑chain dynamics from global refrigerant policies, will reframe procurement and service contracts.
Market trajectory and what the numbers mean
PW Consulting’s modeling integrates vendor shipment data, validated field deployments and component cost trends to produce an annualized view of market value and growth. The market climbed from a measured base in 2020 through rapid adoption during 2021–2024, culminating in USD 105.0 Million in 2025. Our forecast indicates a continuation of that trend, more than doubling market value by 2032 under the central growth scenario (CAGR 9.85% for 2026–2032).
For technology buyers this translates into three operational realities: first, a growing aftermarket and service economy for CDU maintenance and spare‑parts; second, accelerating innovation around modular, hot‑swap, and high‑temperature water systems that alter site PUE and water‑side integration; and third, a maturing procurement market where buyers can leverage competitive supplier tiers for risk mitigation and lifecycle cost optimization.
Competitive landscape: established OEMs and fast movers
The rack‑mounted CDU ecosystem is characterized by a mix of specialized thermal OEMs, legacy power & thermal suppliers, and turn‑key systems integrators. Our vendor analysis highlights capabilities and strategic positioning across the supplier set:
-
CoolIT Systems (Calgary, Canada) — deep in‑rack liquid‑to‑liquid expertise with compact CHx series solutions tuned for high‑density HPC and AI racks.
-
Super Micro Computer / Supermicro (San Jose, USA) — integrates redundant, hot‑swappable pump architectures into in‑rack and in‑row CDUs, focusing on high‑availability AI and HPC installations.
-
DCX Liquid Cooling Systems (Warsaw, Poland) — pursues a compact, high‑capacity 4U form factor aimed at dense AI deployments.
-
LiquidStack (Carrollton, USA) — targets ultra‑high capacity and narrow approach temperature use cases with thin‑gap direct‑to‑chip strategies and elevated water temperatures.
-
Flex (via JetCool, Austin, USA) — recently launched a modular rack‑level CDU platform designed to scale across multi‑hundred‑kilowatt to megawatt‑class racks, signaling a systems integrator play into GPU‑dense deployments.
-
Motivair (Schneider Electric, Lancaster, USA) — leveraging Schneider’s channel and service footprint with scalable in‑rack to floor variants for AI factory use cases.
-
Asetek (Denmark, global operations) — provides warm‑water InRack CDU solutions optimized for energy efficiency and simplified plumbing.
-
nVent (Minneapolis, USA) — focuses on reliability and chilled‑coolant delivery systems for high‑uptime environments.
-
Dell Technologies (Round Rock, USA) — brings OEM server/CDU integration with a rack‑mount CDU for dense AI and HPC racks, leveraging installed base relationships with enterprise buyers.
-
Eaton (Dublin/US operations) — positions CDU capability as part of broader thermal and power management portfolios for data center OEM customers.
Competitive dynamics are shifting quickly. Recent product activity — including Flex’s modular JetCool launch (Sept 2025), Motivair’s MCDU‑70 scaled offering (Jan 2026), and Dell’s continued promotion of higher‑capacity rack CDUs — underscores a race for both feature differentiation and scale economics. PW Consulting’s vendor matrices in the full report evaluate these suppliers across technology fit, integration risk, serviceability, and TCO impact to help procurement teams prioritize pilots and rollouts.
Consolidation and concentration: market power matters
The market exhibits moderate concentration by value: the three largest vendors account for a significant share of the market’s commercial value, and the top five participants establish a clear second tier. This structure creates both negotiating leverage for large buyers and a bifurcated channel where specialist integrators and OEMs compete on service depth versus scale. Our competitiveness heatmaps and procurement playbook help buyers navigate preferred‑supplier selection while preserving optionality for future architecture shifts.
Standards, regulation and supply‑chain shocks
-
Standards: ASHRAE Technical Committee updates — notably the inclusion of liquid‑to‑liquid CDU test methods in Standard 127 and guidance from ASHRAE TC 9.9 on isolating facility water from technology cooling loops — are raising the bar for performance certification and installation practice. Compliance will increasingly be table stakes in enterprise RFPs.
-
Regulatory and materials pressure: global refrigerant phase‑down measures (Kigali Amendment) and related certification requirements are increasing production and compliance costs across thermal components. Suppliers with diversified coolant strategies and robust materials sourcing will be advantaged.
-
Operational risk: as liquid cooling moves deeper into mission‑critical stacks, failure modes, service SLAs and spare parts logistics become material to availability. The full report quantifies downtime dollar exposures and models maintenance contract structures suitable for different risk appetites.
Report practicalities: what’s inside and how it helps buyers in 2026
PW Consulting’s study is designed as a practical director‑level toolkit rather than a purely descriptive market brief. Key deliverables inside the report include:
-
Market sizing and scenario models — transparent inputs and sensitivity analysis for CAPEX/OPEX tradeoffs across 2026–2032.
-
Vendor scorecards — comparative evaluation of technical fit, integration risk, service footprint, and supplier financial resilience.
-
Deployment playbooks — step‑by‑step checklists for pilot planning, site plumbing & mechanical integration, commissioning and lifecycle maintenance.
-
TCO and ROI tools — downloadable calculators that convert thermal metrics (approach temp, delta‑T, pumping energy) into financial outcomes under multiple electricity and water price scenarios.
-
Procurement templates — RFP language, SLA constructs, and acceptance test plans that align with ASHRAE test addenda and industry best practices.
-
Risk & compliance matrix — mapping of regulatory drivers, product certification needs, vendor mitigation options, and contractual language to manage transition risks.
Deliberately, the report follows a “trailer” principle in its public outputs: we demonstrate analytical depth and operational rigor, but we withhold the full granular segmentation tables, confidential supplier scoring and unit‑level pricing models from the public summary. These datasets are integral for procurement negotiations and scenario planning; qualified buyers are invited to access the full data package via our report portal.
Actionable recommendations for 2026
-
Convert pilots into modular rollouts where possible. The economics of rack‑level CDUs improve materially at scale when paired with predictable maintenance contracts and integrated monitoring.
-
Embed ASHRAE‑aligned acceptance tests into procurement. Demand vendor certification against the updated test methods to de‑risk integration and operational performance.
-
Negotiate spare‑parts and hot‑swap agreements. Given the criticality of pump assemblies and heat‑exchange modules, defined MTTR targets and logistically enabled spares will reduce exposure to costly downtime.
-
Stress‑test total cost scenarios against water and electricity sensitivity. Our TCO tools show threshold points where liquid cooling achieves decisive cost advantage — these should be used to set internal gating criteria for wider adoption.
-
Prioritize vendors with demonstrable system‑level experience. Firms that can manage both server integration and facility interfacing reduce project friction and accelerate time‑to‑value.
Next steps
Organizations preparing procurement strategies, capital plans or technical roadmaps for 2026 should treat rack‑mounted CDUs not as peripheral accessories but as strategic components that influence server architecture, site planning and long‑term energy strategy. PW Consulting’s Rack‑mounted Full Liquid CDU Market Report supplies the modeling, vendor intelligence and operational playbooks required to convert opportunity into measurable business outcomes.
To request the full report package, detailed vendor scorecards, and access to our interactive TCO models, visit PW Consulting’s research portal or contact our industry team for a briefing tailored to your deployment profile.
For detailed analysis of this topic, please visit the official page: Rack-mounted Full Liquid CDU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Indirect Auto Finance Market Poised to Expand at a 6.85% CAGR Through 2032
By pmarketresearch, 2026-07-15
Indirect Auto Finance Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
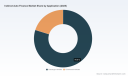
As companies set priorities for 2026, leaders in auto finance face a pivotal inflection point. PW Consulting’s new Indirect Auto Finance Market report — anchored on a 2025 base year, a 2020–2025 historical series, and a 2026–2032 forecast horizon — translates macro trends into executable choices. The market we model has expanded materially over the past half‑decade and, under our central case, continues to grow at a compounded annual growth rate of 6.85% through the forecast window. This briefing summarizes the report’s practical value for boardrooms and C‑suites while preserving the granular segment intelligence that we reserve for the full release.
Indirect Auto Finance Market
Why this report matters to 2026 decision-makers
-
Market momentum: After several years of accelerated expansion, indirect auto finance is entering a phase of more heterogeneous growth. Knowing the absolute market trajectory — and the pace implied by the 6.85% CAGR — is essential for calibrating return hurdles, capital allocation, and product shelf sizes for the year ahead.
Indirect Auto Finance Market -
Regulatory inflection: The regulatory backdrop has shifted meaningfully into 2025–2026. Recent CFPB activity and legislative analysis have elevated compliance and supervisory risk for nonbank participants; firms must understand how regulatory thresholds and enforcement posture could affect business models, dealer relationships, and origination strategies.
Indirect Auto Finance Market -
Competitive repositioning: Our analysis shows that market concentration is meaningful but not prohibitive — with the three‑firm and five‑firm concentration metrics indicating room for both scale players and specialist entrants to prosper. That dynamic shapes M&A, partnership, and pricing strategies for 2026.
-
Operational resilience: Macroeconomic and credit cycles are creating asymmetric risks between new‑vehicle and used‑vehicle exposures, underwriting tiers, and dealer channels. The report converts these risks into prioritized investments in underwriting, dealer portal experience, and collections playbooks.
What the PW Consulting report delivers — operationally usable insights
-
Proprietary market sizing and trajectory: A full historical series (2020–2025) and a detailed forecast (2026–2032) that quantify the market’s evolution and provide scenario runs for downside stress and upside acceleration. These are modeled to support budgeting, balance‑sheet planning, and securitization shelf sizing.
-
Revenue and concentration metrics: We provide top‑line market measures and market concentration analytics to support strategic benchmarking, including CR3 and CR5 analysis to inform M&A appetite and pricing discipline.
-
Dealer channel diagnostics: Practical playbooks for optimizing indirect origination through franchise and independent dealerships, including dealer economics, funding cadence, and dealer portal best practices.
-
Regulatory & compliance toolkits: A structured assessment of current and prospective regulatory actions (including CFPB rulemaking trajectories and supervisory focus areas), with a compliance “to‑do” matrix for 2026 to reduce legal and remediation exposure.
-
Underwriting & pricing playbooks: Tactical scoring updates, vintage performance stress tests, and model re‑calibration guidance that translate observed behavioral shifts into rate card and collateral strategies.
-
Capital & funding scenarios: Funding stack playbooks, securitization readiness checklists, and sensitivity analyses tying interest‑rate paths and originator mix to funding cost and liquidity buffers.
-
Technology and vendor shortlists: Evaluated vendor options across dealer portals, e‑contracting, decisioning engines, and collections/portfolio management, with implementation roadmaps mapped to expected ROI horizons.
-
M&A and partnership thesis: A pragmatic framework for evaluating targets — from non‑prime specialists to bank players and captive finance divestitures — with valuation sensitivities and integration risk matrices.
Competitive landscape — what we see and what it means
Indirect channels remain the dominant origination route for auto lending. Our report profiles established captives, bank portfolios, and specialized finance companies, and draws strategic implications for each category. Major participants include leading bank lenders, independent finance companies, and captive arms of manufacturers — each following distinct playbooks:
-
Banks and large non‑captives: These institutions are leveraging scale, depositor funding advantages, and increasingly sophisticated digital dealer integrations to defend and expand indirect share. Their focus for 2026 will center on optimizing dealer economics and improving approval velocity without compromising credit discipline.
-
Captive finance companies: Manufacturer captives remain central to OEM go‑to‑market strategies, especially for purchase and lease programs that support sales targets. Captives will continue to deploy product bundles, loyalty incentives, and sales‑aligned programs to retain channel primacy.
-
Independent and specialty lenders: Niche players are exploiting underwriting sophistication and nonprime expertise to capture incremental volume. However, they face higher regulatory scrutiny and funding premia — forcing tradeoffs between growth and capital resiliency.
The report includes company‑level profiles and strategic assessment for the leading participants, distilled from public disclosures and proprietary interviews. For example, we examine how major non‑captives are reengineering dealer relationships, how captives are aligning product suites to lifecycle financing, and how independents are segmenting credit risk to sustain yields.
Regulatory and macro dynamics shaping 2026 choices
Regulation and macro forces are converging to shape the competitive calculus for next year:
-
Supervisory focus and rulemaking: Recent CFPB activity — including notice on large participant definitions and interpretive guidance affecting fair‑lending claims — requires firms to revisit sampling, fair‑lending controls, and adverse action processes. The report prescribes specific governance and remediation playbooks to reduce supervisory risk and potential enforcement costs.
-
Originations trend sensitivity: Industry sources point to a modest near‑term softening in overall originations driven by affordability pressures. PW Consulting models alternative origination trajectories and demonstrates how modest volume contractions materially affect unit economics, portfolio turnover, and liquidity needs.
-
Dealer finance dynamics: Growth in dealer‑finance debt and shifting party shares underscore the need to rethink dealer advance facilities, buy‑rate/mark‑up economics, and reconciliation practices to limit credit leakage.
Strategic imperatives and recommended actions for 2026
Based on our modeling and competitive analysis, PW Consulting recommends a prioritized set of actions for executives planning 2026 strategies:
-
Recalibrate dealer economics: Redesign dealer compensation and funding offers to reward volume that aligns with risk‑adjusted margins. Invest in dealer-facing digital tools that compress time‑to‑fund while increasing transparency.
-
Harden compliance posture: Implement a near‑term compliance sprint focused on fair‑lending controls, model governance, and originations reporting to prepare for heightened supervisory attention.
-
Stress‑test funding plans: Run alternative funding scenarios and securitization stress tests that incorporate both mild demand erosion and sudden spread widening to ensure liquidity resilience.
-
Targeted portfolio optimization: Use granular vintage analysis to reweight originations toward the most attractive risk/return cohorts, and consider selling or hedging stressed vintages where economics deteriorate.
-
Pursue selective partnerships: For firms lacking scale, partnering with established bank platforms or technology providers can accelerate capability builds with lower up‑front capital consumption than full build‑outs.
-
Prepare for M&A optionality: Given market concentration metrics, scalable acquirers should accelerate target screening and pre‑deal integration planning — and non‑scale players should develop defensive consolidation strategies.
Scenarios to prioritize in 2026 planning
Three scenarios in our forecast require board attention:
-
Base case (policy steady, demand modest growth): Continuation of current trajectories with moderate growth consistent with the modeled CAGR; management focus on execution and efficiency gains.
-
Downside (affordability shock): A near‑term contraction in originations driven by affordability pressures requires rapid redeployment of capital to preserve liquidity and margin‑enhancing originations.
-
Regulatory tightening: Elevated enforcement or new rules imposing higher compliance costs that compress returns and alter the economics of smaller originators.
Each scenario in the full report includes quantified P&L and balance‑sheet impacts and recommended tactical responses tied to timing horizons (0–6 months, 6–18 months, 18–36 months).
Final notes — the trailer approach
PW Consulting’s Indirect Auto Finance Market report is designed as a strategic decisioning tool for 2026. This briefing highlights the report’s actionable insights and strategic implications while intentionally withholding detailed segment and regional breakout figures. The detailed segment sizes, regional matrices, and per‑company benchmarking tables — along with our full financial models — are available in the report and the accompanying data annex.
If your team is preparing 2026 budgets, capital plans, regulatory remediation roadmaps, or M&A pipelines, the report will convert the market’s macro trajectory and competitive forces into operational moves. For boards and senior leadership teams, it provides the scenarios, diagnostic tools, and tactical playbooks necessary to preserve optionality while capturing profitable growth.
Contact PW Consulting to access the full Indirect Auto Finance Market report, including the granular segment data, competitive scorecards, and the downloadable Excel model that powers our forecasts and scenario analyses.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Sound Insulation NVH Market to Grow at 5.85% CAGR, Rising from USD 14.19B in 2025 to USD 21.12B by 2032 — Asia Pacific Leads with USD 8.11B
By pmarketresearch, 2026-07-15
Automotive Sound Insulation NVH Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research — the Automotive Sound Insulation NVH Market Report (base year 2025) — positions 2026 as a pivotal year for automotive original equipment manufacturers (OEMs), suppliers, and tier‑1 integrators. Drawing on a comprehensive historical review (2020–2025) and a forward forecast to 2032, the study quantifies an expanding total addressable market and maps the practical routes organizations must follow to convert regulatory pressure, electrification dynamics, and material innovation into durable competitive advantage.
Automotive Sound Insulation NVH Market
Headline macro view
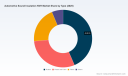
Key macro takeaways from the study are unambiguous: the global sound insulation NVH market has recovered and accelerated through the early 2020s and reached an inflection at the 2025 base year. Our top‑line forecast shows the market continuing to expand through 2032 at a compound annual growth rate (CAGR) of 5.85%, reflecting a multi‑year structural upswing driven by regulatory tightening, the spread of electric vehicles, and heightened customer expectations for in‑cabin acoustic comfort. In monetary terms this growth translates into a material increase in industry revenue over the forecast horizon (reported in USD Million), underscoring both volume and value opportunities for strategically positioned players.
Automotive Sound Insulation NVH Market
Why 2026 matters: regulatory and technology accelerants
-
Regulatory inflection points. Two regulatory milestones compress timelines and compress the decision window for sound insulation investments: the EU’s phased noise limits (tied to tighter dB(A) thresholds) and the UNECE R51.03 Phase 3 update effective from July 2026, with revised urban weighting and high‑load testing. Together, these require automotive OEMs and suppliers to validate acoustic performance under more stringent and diverse test conditions — not a future consideration but an immediate procurement and design constraint for 2026 VINs.
Automotive Sound Insulation NVH Market -
Electrification alters the NVH problem set. Battery and electric drive architectures reduce engine masking and shift subjective noise drivers toward road, tire, aerodynamic and electrical tonal content. That pivot increases the relative value of passive insulation materials, tuned damping systems, and hybrid solutions (materials + architectural decoupling + targeted active control) — and expands the role of acoustics earlier in vehicle architecture programmes.
-
Sustainability and lightweighting converge with NVH. Suppliers that can deliver high acoustic performance per unit mass and demonstrate recycled‑content credentials will secure preferential design slots. This is not incremental: it materially affects supplier selection, bill‑of‑materials (BOM) economics, and crash/packaging trade‑offs in 2026 platform specifications.
Practical value of the report for 2026 corporate decisions
Clients engaging with PW Consulting will find this report is structured as an operational playbook, not an academic paper. It converts the macro trend (5.85% CAGR and the quantified market trajectory) into prioritized, executable choices across product development, sourcing, pricing, and M&A to be decided in 2026:
-
Product roadmap sequencing — which material technologies and NVH system architectures to fast‑track for 2026 platform launches versus those that can be phased for 2027–2028.
-
Procurement and supplier risk matrices — supplier concentration heatmaps, dual‑sourcing thresholds, and inbound logistics sensitivity to raw material price and recycling policy shifts.
-
Technology investment case templates — NPV and payback analyses for investments in new material lines, adhesive application systems, and active sound control integration, calibrated for 2026 regulatory compliance timing.
-
Go‑to‑market and pricing playbooks — value capture strategies for OEMs and tier‑1s seeking to monetize improved NVH packages while preserving list‑price discipline under cost pressure.
Report contents at a glance (operational modules)
-
Market sizing and growth modelling (2020–2025 historical, 2026–2032 forecast) with scenario stress tests tied to regulatory and EV adoption pathways.
-
Materials performance compendium — comparative matrices (mass, absorption/damping performance, recyclability, cost per effective dB reduction) and targeted application use cases (interiors, powertrain enclosures, underbody, cavity filling).
-
Commercial benchmarking and margin archetypes — supplier margin corridors by technology approach and integration depth.
-
Competitive intelligence dossiers — strategic profiles, recent moves, capability maps and alliance matrices for leading NVH participants.
-
Implementation toolkits — BOM optimization templates, compliance roadmaps for UNECE and EU regimes, supplier selection scorecards, and M&A diligence checklists.
-
Proprietary scenario models — run‑time decision dashboards that let teams quantify trade‑offs between weight, cost, manufacturability and acoustic performance for immediate use in 2026 programme gates.
Competitive landscape and strategic implications
The NVH supply base remains neither fragmented nor oligopolistic — a market structure where leading specialists capture meaningful value but nimble challengers can still win program content through technology or sustainability differentiation. Our report highlights the following strategic archetypes among incumbent and emerging suppliers:
-
Platform specialists (e.g., Autoneum) — firms that combine lightweight fiber‑based systems with high recycled content are consolidating their role in interior acoustic architecture. Their public showcases and conference engagements underscore a two‑pronged strategy: lift acoustic performance while advancing mono‑material and recyclable carpet systems that ease end‑of‑life recovery.
-
Materials innovators (e.g., BASF, Dow) — chemical majors are extending foam, elastomer and engineered polymer portfolios to serve chassis mounts, cavity fillers and tailored dampers. Their advantage lies in material science depth and scale‑up capabilities, enabling faster translation of lab innovations into validated OEM releases.
-
System integrators with specialty know‑how (e.g., Vibracoustic, Sumitomo Riko) — these players focus on engineered mounts, air springs and decoupling systems optimized for EV NVH signatures. Recent program wins for electric pickup trucks and premium segments highlight the premium OEM need for integrated mechanical NVH solutions beyond passive insulation alone.
-
Adjacency players (e.g., 3M, Henkel, ElringKlinger) — firms supplying acoustic adhesives, thin‑film insulations, and sealing solutions are moving up the value chain through higher‑performance laminates and application engineering capabilities, enabling faster in‑vehicle validation cycles.
Observed strategic moves during 2024–2025 demonstrate clear priorities: product showcases at major industry fora; targeted program supply for premium EVs; and the roll‑out of mono‑material and recycled‑content solutions. These moves are consistent with the broader market trajectory and the CR3/CR5 concentration dynamics we map in the report — a competitive field where scale, IP in material science, and early OEM co‑development wins translate into outsized program containment.
Operational recommendations for 2026 planning cycles
-
Accelerate acoustic targets into early architecture phases. Make NVH an explicit 1.0 requirement in 2026 platform definition rather than a later optimization task — test cases in our modelling show this reduces retrofit cost and program risk.
-
Adopt a hybrid sourcing model. Combine long‑term partnerships with material innovators for core acoustic modules and flexible spot contracts for commodity foam and adhesive supply to manage input volatility.
-
Prioritize mono‑material and recycled‑content solutions where mass and end‑of‑life policy overlap; include recyclability KPIs in supplier scorecards to align with regulatory and consumer pressures.
-
Embed regulatory compliance pathways in programme gates. With UNECE R51.03 Phase 3 and tightened EU noise limits becoming binding, acoustic validation and documentation must be completed earlier in the verification chain to avoid costly redesigns.
-
Use M&A selectively to accelerate capability — small bolt‑on acquisitions of acoustic software, measurement houses, or niche materials producers often yield quicker in‑vehicle integration than greenfield investments.
Where the report stops — and why you should read the full study
In keeping with PW Consulting’s “trailer” principle, this press briefing surfaces the strategic implications of the market trajectory and competitive dynamics while intentionally omitting granular segmentation tables and line‑item regional splits that are central to procurement and M&A modelling. The decision‑useful, proprietary segmentation (by region, material type and application), supplier share breakdowns and the downloadable scenario workbooks are available exclusively in the full report and the client portal.
For teams preparing 2026 budgets, platform specifications, or sourcing roadmaps, the full report provides the specific segmented metrics, supplier scorecards, and downloadable modelling templates you will need to move from insight to execution.
Next steps
-
Contact PW Consulting to obtain the full Automotive Sound Insulation NVH Market Report and request an executive briefing tailored to your product line or procurement exposure.
-
Book a workshop to run the report’s scenario models on your vehicle programmes — accelerate compliance planning for UNECE R51.03 Phase 3 and EU noise limits.
-
Request a supplier due diligence deep dive (including on‑site capability assessments) to validate partner claims on recyclability and acoustic performance ahead of 2026 program approvals.
PW Consulting’s team of industry strategists and acoustic engineering specialists stand ready to translate the market’s 5.85% CAGR trajectory and the 2026 regulatory inflection into prioritized actions that protect margin, speed time‑to‑market, and secure acoustic leadership in the electric era.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: L6 & L7 Quadricycles Market Set to Reach USD 3,887 Million by 2032
By pmarketresearch, 2026-07-15
L7 and L6 Quadricycles Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest L7 and L6 Quadricycles Market study (base year 2025) offers a concise, actionable roadmap for companies positioning themselves for growth in the evolving light-quadricycle ecosystem. This preview highlights the report’s strategic value for 2026 decision-making: we demonstrate the market trajectory, competitive dynamics, regulatory pressures, and practical playbooks that senior executives and investment teams need — while reserving the full, granular segment models and company-level datasets for the complete report.
L7 and L6 Quadricycles Market
Market trajectory in one picture
The market for L6 and L7 quadricycles has shifted from niche to mainstream over the last five years. Global market value rose from approximately USD 1,425.5 million in 2020 to USD 2,350.0 million in 2025 (base year). Looking forward, our forecast (2026–2032) projects the sector to expand at a compound annual growth rate of 7.45%, reaching an estimated USD 3,887.0 million by 2032. This sustained expansion reflects accelerating electrification, municipal and commercial fleet procurement, and OEM engagement with micro‑mobility platforms.
L7 and L6 Quadricycles Market
What this means for 2026: companies must treat the quadricycle arena as a growth market that rewards speed of execution, platform modularity, and targeted go‑to‑market playbooks rather than incremental product tweaks.
L7 and L6 Quadricycles Market
Why 2026 is a strategic inflection point
- Regulatory clarity and constraints: EU technical frameworks for L6e and L7e vehicle categories are well-established, creating predictable engineering and homologation boundaries. That regulatory certainty reduces development risk but increases competitive pressure to deliver differentiated value within defined weight, power and speed envelopes.
- Electrification is now the default path: Recent market behavior shows that the majority of new quadricycles in key markets are fully electric. Battery-pack performance, thermal management, and cost per kWh now materially influence product acceptance and lifetime cost of ownership.
- Demand migration from personal to commercial use: Municipal fleets, logistics providers and last‑mile operators are emerging as high‑value customers, creating durable order pipelines and opportunities for recurring service revenue through fleet telematics and battery-as-a-service models.
- Industry consolidation and partnership acceleration: Strategic M&A and platform partnerships are reshaping capability maps — from OEMs leveraging micro‑mobility brands to established quadricycle specialists partnering with battery and e‑powertrain players to scale.
- Moderate market concentration: The sector exhibits a measurable concentration: the top three players account for a significant share of market revenue while the top five consolidate more than half of the market. That structure rewards differentiation for challengers and scale for incumbents.
Competitive landscape — who’s shaping the market
The competitive field blends legacy European specialists, established OEM micro‑mobility arms, and emerging electric‑vehicle specialists. Each archetype follows a distinct strategic playbook:
- European quadricycle specialists: Companies with deep product heritage in light quadricycles continue to dominate in product breadth and dealer networks. These firms are advancing both ICE and electric variants, refreshing model lineups and leveraging brand recognition for urban and professional segments.
- Electric vehicle niche players: Smaller EV-focused manufacturers are capitalizing on lightweight vehicle expertise and fast product cycles to offer high-efficiency, city-optimized platforms that appeal to urban commuters and private buyers.
- OEM micro‑mobility arms: Large automakers and group brands are introducing city‑ready, low‑speed quadricycle offerings, leveraging procurement scale, marketing reach, and platform engineering to accelerate adoption.
Representative industry actors covered in our competitive analysis include established light-quadricycle manufacturers, utility-focused electric vehicle firms, and OEM micro‑mobility initiatives. The report profiles each player’s strategic positioning, product architecture, distribution footprint and recent strategic moves — from partnerships and municipal contracts to acquisitions and product launches.
Recent strategic moves that matter to 2026 planning
- Strategic partnerships to accelerate electrification and modular platforms — incumbent manufacturers are moving quickly to integrate advanced battery and motor systems through alliances rather than in-house development alone.
- Municipal fleet wins are validating utility-focused EV propositions; large municipal tenders are becoming a repeatable revenue channel for manufacturers that can meet customization and service-level demands.
- Targeted acquisitions have broadened product portfolios and geographic reach, enabling faster scaling of electric quadricycle offerings and aftermarket ecosystems.
- High‑visibility product refreshes and new model debuts at major motor shows are serving to reframe brand perceptions and stimulate consumer interest in micro‑mobility ownership.
What’s inside the full PW Consulting report (practical deliverables)
Our full L7 and L6 Quadricycles Market report translates market signals into executable priorities. Key deliverables include:
- Comprehensive market model: Five‑year historical series and seven‑year forecast (2026–2032) with bottom‑up revenue build, sensitivity scenarios and a break‑out of the market’s growth drivers. (Note: full segment tables and company‑level revenue splits are available in the complete report.)
- Scenario analysis and stress tests: Three forward scenarios (Base, Accelerated Electrification, Supply‑Chain Shock) with financial outcomes and strategic implications for product roadmaps, capex timing and inventory policies.
- Regulatory and compliance map: Actionable checklist for homologation, license class implications and country‑level go‑to‑market constraints in major European markets.
- Go‑to‑market playbooks: Tailored commercial strategies for personal-use, last‑mile logistics and municipal customers — including channel economics, pricing matrices, dealer vs direct sales decision trees and service revenue models.
- Technology and cost benchmarking: Comparative analysis of battery pack architectures, e‑motor options, and modular platform approaches to help engineering and procurement teams prioritize supplier partnerships.
- Competitive product matrix and capability gaps: Side‑by‑side comparisons of feature sets, warranty structures and telematics integrations to inform product positioning (full matrices available in the paid report).
- M&A and partnership playbook: Target screening criteria, valuation heuristics and integration checklists for companies seeking inorganic growth or capability partnerships.
- Risk register and mitigation plans: Identification of top value‑chain risks (supply, regulation, technology obsolescence) with prioritized mitigation measures and monitoring KPIs.
- Primary research appendix: Summaries of stakeholder interviews, OEM supplier discussions and municipal procurement officers that underpin our recommendations.
Recommended strategic moves for 2026
Based on our market model and field interviews, PW Consulting recommends five priority actions for executive teams:
- Commit to modular EV platforms: Prioritize vehicle architectures that accept multiple battery sizes and powertrain options to serve both personal and commercial customers without prohibitive retooling costs.
- Target fleet and municipal pilots early: Secure pilot agreements with city administrations and logistics operators to build proof points for reliability, total cost of ownership and service economics. Winning municipal tenders establishes reputational momentum.
- Forge capability partnerships: Where battery and motor expertise is not core, pursue joint development or procurement alliances to accelerate time-to-market while preserving product differentiation.
- Design for service revenue: Embed telematics, battery‑life guarantees, and modular maintenance packages into pricing to extend lifetime value and reduce churn.
- Use staged M&A to fill capability gaps: Consider small, capability‑focused acquisitions to add software, battery remanufacturing or local distribution scale rather than large horizontal deals that dilute focus.
Who should read this report and how to use it
The report is designed for C‑suite leaders, product and engineering heads, corporate development teams, and private equity investors considering exposure to micro‑mobility. It functions as both a strategic playbook and an operational toolkit: use the market model to stress‑test business cases, the scenario work to set investment gates, and the competitive matrices to benchmark offerings before pricing or channel decisions.
As a preview we have shared the headline market trajectory, concentration metrics and the strategic themes that will define winners in 2026. The full report contains the granular segmentations, price and unit models, competitor revenue tables, and procurement tender templates necessary to execute the strategies summarized here.
Next steps
- Download the full report and data workbook to access the detailed segment models, product matrices and company profiles.
- Request a tailored executive briefing with PW Consulting to align the findings to your 2026 business plan and investment priorities.
- Engage our deal team for target screening if you are evaluating acquisitions or partnerships in the quadricycle space.
PW Consulting’s L7 and L6 Quadricycles Market report synthesizes market evidence, regulatory realities and competitive motion into a pragmatic guide for 2026 decision-making. For teams that must move from strategy to execution this year, the right choices now — on platform design, partner selection and customer targeting — will determine who captures the disproportionate share of growth over the coming business cycle.
For detailed analysis of this topic, please visit the official page: L7 and L6 Quadricycles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Paint Booth Market to grow from USD 855.0 Million in 2025 to USD 1,254.45 Million by 2032 at a 5.65% CAGR
By pmarketresearch, 2026-07-15
Automatic Paint Booth Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting's latest market research — Automatic Paint Booth Market: 2026–2032 Strategic Outlook — provides an executive-grade, actionable intelligence package designed to shape capital allocation, procurement, and product strategy for industrial manufacturers, body shops, OEM paint shops, and private equity investors entering the space in 2026. Drawing on an evidence base that spans the 2020–2025 historical period and a robust forecast horizon of 2026–2032, the report frames near-term tactical choices within a long‑range view of demand growth, regulatory pressure, and technology adoption.
Automatic Paint Booth Market
Market trajectory at a glance
Using 2025 as the base year, PW Consulting’s model shows the global automatic paint booth market expanded from USD 612.45 Million in 2020 to USD 855.0 Million in 2025. Our scenario-driven forecast projects continued expansion through 2032, reaching approximately USD 1,254.45 Million by the end of the forecast period (2026–2032 CAGR: 5.65%). These headline numbers reflect a balancing of cyclical capital expenditure patterns, accelerating automation adoption in higher-volume segments, and the capital intensity of regulatory and sustainability-driven upgrades that are reshaping buying criteria.
Automatic Paint Booth Market
Important nuance: the 2026–2032 path is not linear — the model embeds near-term variability driven by macroeconomic cycles, supply-chain friction (notably steel and specialized filtration media pricing), and a rapid pivot toward waterborne coatings in many end-markets. PW Consulting’s forecast therefore provides both point estimates and alternative scenarios to support contingency planning and capital phasing decisions.
Automatic Paint Booth Market
Why 2026 is a tipping point for procurement and capex
- Regulatory and compliance inflection: Enforcement and guidance under OSHA (29 CFR 1910.107) and EPA NESHAP Subpart HHHHHH are tightening expectations for ventilation, fire-safety construction, and filter capture efficiency. Buyers must now embed compliance validation into procurement specifications rather than treating it as an add-on.
- Coatings technology transition: The industry-wide shift to waterborne coatings increases the importance of precise climate control (typical targets in the sector span 18–25°C and 50–65% relative humidity). Booth selection and HVAC design must be assessed against these operational envelopes to avoid rework costs and warranty exposure.
- Automation and flexibility: Demand is bifurcating: high-throughput OEM and contract finishers prioritize multi-stage automated solutions and robotic integration, while smaller repair and specialty shops favor modular, energy-efficient booths that optimize floor space and TCO.
- Input-price volatility: Raw-material swings — steel and filtration media in particular — are material to manufacturing margins and should inform contract terms, inventory strategies, and supplier selection.
Practical strategic imperatives for 2026
For executives making procurement, manufacturing, or investment decisions in 2026, the PW Consulting report recommends a prioritized, pragmatic playbook:
- Adopt a phased-capex approach: Break large paint-shop projects into validated modules. Prioritize investments that unlock capacity or compliance quickly (e.g., filtration upgrades, climate control retrofits) and defer lower‑ROI automation stages until throughput is proven.
- Require end-to-end TCO metrics in RFPs: Move beyond purchase price — require bidders to provide lifecycle energy consumption, filter replacement schedules and costs, expected production throughput under waterborne coatings, and compliance validation documentation.
- Insist on interoperability and upgrade paths: Specify modular control architectures and open-communication standards (for robotics and IoT) so that initial systems can host future automation or process controls without full replacement.
- Hedge supply‑chain exposure: Secure multi-year or indexed contracts for critical inputs where possible; evaluate regional sourcing and pre-formed kits to reduce lead times and exposure to raw-material spikes.
- Test before scale: Run pilot installations or staged proofs-of-concept to validate waterborne-coating performance and climate-control regimes at production scale before committing to full-array automation.
- Quantify sustainability as an economic lever: Model energy savings and emissions reductions from LED curing, heat-recovery HVAC, and optimized booth airflow — these often produce measurable operating-cost improvements that shorten payback periods.
- Factor in aftermarket and service economics: Prioritize vendors offering fast local service, parts availability, and remote diagnostics; downtime at finishing stages has outsized operational impact.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms hold a meaningful but not dominant share of revenue, and the top five account for roughly half of market receipts. This dynamic creates room for both incumbent expansion and nimble regional or specialist providers to win deals — particularly where local code knowledge, rapid service, and tailored engineering matter.
- Garmat USA (USA) — Strength: code-compliant automotive and heavy-duty repair booths with strong regional support and an emphasis on airflow and safety. Best for repair shops prioritizing regulatory alignment and proven designs.
- Accudraft Paint Booths (SAIMA of North America) (USA) — Strength: high-production automotive and commercial booths plus prep and finishing solutions accumulated over decades; strong option for high-throughput body shops seeking integrated systems.
- Global Finishing Solutions (GFS) (Osseo, WI) — Strength: wide portfolio spanning industrial, automotive, and automated booths including multi-stage options; attractive where turnkey finishing lines and automation are required.
- Blowtherm USA (USA) — Strength: energy-efficient systems with demonstrable case-study outcomes in quality and sustainability; a vendor to watch where energy costs and emissions goals drive procurement.
- RTT Finishing Solutions (Rockwall, TX) (USA) — Strength: engineering focus across diverse applications; recent leadership changes signal an integration phase following acquisition, which may affect vendor strategy and go-to-market execution.
- Spray‑Tech (Rialto, CA) (USA) — Strength: custom-engineered, high-performance booths suited to specialized auto, aerospace, and manufacturing applications where bespoke solutions are required.
- Taikisha USA (Troy, MI) (USA) — Strength: downdraft robotic paint spray booths with a focus on automotive manufacturing environments; best-in-class for large OEM paint shops seeking scale and integration.
- Dürr Systems (Germany, global) — Strength: world-leading automated paint-shop and robotic application technology; strong capability for future-proofed, flexible paint lines — evidenced by public showcases of “paint shop of the future” solutions.
- Marathon Finishing Systems (USA) — Strength: high-performance booths for automotive, industrial, and aerospace customers; useful where performance and reliability are prioritized.
Recent vendor moves in 2025–2026 illustrate the market dynamics: executive appointments following acquisitions, case-study installations demonstrating sustainability and efficiency gains, and vendor showcases of flexible, future-ready paint-shop architectures. These developments highlight two trends: consolidation among service-capable suppliers and a marketing pivot toward sustainability and automation as primary differentiators.
What the PW Consulting report delivers — operational, actionable content
Beyond headline forecasts, the report is explicitly built for practitioners who must convert insight into action in 2026. Key deliverables include:
- Decision frameworks for retrofit vs. greenfield projects, with stepwise capex phasing and break‑even timelines.
- Vendor scorecards and RFP templates calibrated to regulatory compliance, energy consumption, automation readiness, and aftermarket service KPIs.
- Detailed TCO models that quantify energy, maintenance, filter replacement, labor, and downtime exposures under alternative coating regimes (including waterborne scenarios).
- Scenario planning modules for supply‑chain disruption and raw-material price shocks, with mitigation playbooks.
- Regulatory compliance checklists aligned to OSHA and EPA NESHAP requirements and practical verification steps for procurement and acceptance testing.
- Integration roadmaps for staged automation, digital monitoring, and remote diagnostics to protect optionality while reducing upfront risk.
Note: to preserve commercial sensitivity and to guide decision-makers to validated data sources, this public briefing intentionally omits granular splits by region, booth type, and application — those detailed segmentations and vendor-level market share matrices are available in the full report.
Implications for buyers, OEMs, and investors in 2026
- Buyers: Treat 2026 as an inflection year to reframe booth acquisitions as long-lived production assets with embedded software, HVAC, and filtration lifecycles. Require warranty and service clauses that reflect modern operating profiles (waterborne coatings, robotic processes).
- OEMs / Contract Finishers: Prioritize modular automation that can be scaled with demand, and negotiate supplier commitments for upgrades and spare-part availability to reduce time-to-revenue during ramp phases.
- Investors / PE: Look for targets with strong regional service footprints, proprietary installation methodology, and differentiated energy-efficiency offerings — these attributes materially improve exit multiples in this market.
Next steps
PW Consulting’s Automatic Paint Booth Market: 2026–2032 Strategic Outlook is designed to be a working tool for the C-suite, procurement teams, and investors. The full report contains the granular segmentation, vendor share matrices, and downloadable decision tools referenced above. For organizations planning capex or M&A in 2026, early engagement with PW Consulting will enable customized scenario modeling and a tailored vendor selection process that accelerates implementation while controlling compliance and operating risk.
Issued by: PW Consulting — Advanced Industry Practice, Automatic Paint Booth Markets
For detailed analysis of this topic, please visit the official page: Automatic Paint Booth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com