

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Indirect Auto Finance Market Poised to Expand at a 6.85% CAGR Through 2032

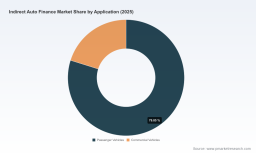
Indirect Auto Finance Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
As companies set priorities for 2026, leaders in auto finance face a pivotal inflection point. PW Consulting’s new Indirect Auto Finance Market report — anchored on a 2025 base year, a 2020–2025 historical series, and a 2026–2032 forecast horizon — translates macro trends into executable choices. The market we model has expanded materially over the past half‑decade and, under our central case, continues to grow at a compounded annual growth rate of 6.85% through the forecast window. This briefing summarizes the report’s practical value for boardrooms and C‑suites while preserving the granular segment intelligence that we reserve for the full release.
Indirect Auto Finance Market
Why this report matters to 2026 decision-makers
-
Market momentum: After several years of accelerated expansion, indirect auto finance is entering a phase of more heterogeneous growth. Knowing the absolute market trajectory — and the pace implied by the 6.85% CAGR — is essential for calibrating return hurdles, capital allocation, and product shelf sizes for the year ahead.
Indirect Auto Finance Market -
Regulatory inflection: The regulatory backdrop has shifted meaningfully into 2025–2026. Recent CFPB activity and legislative analysis have elevated compliance and supervisory risk for nonbank participants; firms must understand how regulatory thresholds and enforcement posture could affect business models, dealer relationships, and origination strategies.
Indirect Auto Finance Market -
Competitive repositioning: Our analysis shows that market concentration is meaningful but not prohibitive — with the three‑firm and five‑firm concentration metrics indicating room for both scale players and specialist entrants to prosper. That dynamic shapes M&A, partnership, and pricing strategies for 2026.
-
Operational resilience: Macroeconomic and credit cycles are creating asymmetric risks between new‑vehicle and used‑vehicle exposures, underwriting tiers, and dealer channels. The report converts these risks into prioritized investments in underwriting, dealer portal experience, and collections playbooks.
What the PW Consulting report delivers — operationally usable insights
-
Proprietary market sizing and trajectory: A full historical series (2020–2025) and a detailed forecast (2026–2032) that quantify the market’s evolution and provide scenario runs for downside stress and upside acceleration. These are modeled to support budgeting, balance‑sheet planning, and securitization shelf sizing.
-
Revenue and concentration metrics: We provide top‑line market measures and market concentration analytics to support strategic benchmarking, including CR3 and CR5 analysis to inform M&A appetite and pricing discipline.
-
Dealer channel diagnostics: Practical playbooks for optimizing indirect origination through franchise and independent dealerships, including dealer economics, funding cadence, and dealer portal best practices.
-
Regulatory & compliance toolkits: A structured assessment of current and prospective regulatory actions (including CFPB rulemaking trajectories and supervisory focus areas), with a compliance “to‑do” matrix for 2026 to reduce legal and remediation exposure.
-
Underwriting & pricing playbooks: Tactical scoring updates, vintage performance stress tests, and model re‑calibration guidance that translate observed behavioral shifts into rate card and collateral strategies.
-
Capital & funding scenarios: Funding stack playbooks, securitization readiness checklists, and sensitivity analyses tying interest‑rate paths and originator mix to funding cost and liquidity buffers.
-
Technology and vendor shortlists: Evaluated vendor options across dealer portals, e‑contracting, decisioning engines, and collections/portfolio management, with implementation roadmaps mapped to expected ROI horizons.
-
M&A and partnership thesis: A pragmatic framework for evaluating targets — from non‑prime specialists to bank players and captive finance divestitures — with valuation sensitivities and integration risk matrices.
Competitive landscape — what we see and what it means
Indirect channels remain the dominant origination route for auto lending. Our report profiles established captives, bank portfolios, and specialized finance companies, and draws strategic implications for each category. Major participants include leading bank lenders, independent finance companies, and captive arms of manufacturers — each following distinct playbooks:
-
Banks and large non‑captives: These institutions are leveraging scale, depositor funding advantages, and increasingly sophisticated digital dealer integrations to defend and expand indirect share. Their focus for 2026 will center on optimizing dealer economics and improving approval velocity without compromising credit discipline.
-
Captive finance companies: Manufacturer captives remain central to OEM go‑to‑market strategies, especially for purchase and lease programs that support sales targets. Captives will continue to deploy product bundles, loyalty incentives, and sales‑aligned programs to retain channel primacy.
-
Independent and specialty lenders: Niche players are exploiting underwriting sophistication and nonprime expertise to capture incremental volume. However, they face higher regulatory scrutiny and funding premia — forcing tradeoffs between growth and capital resiliency.
The report includes company‑level profiles and strategic assessment for the leading participants, distilled from public disclosures and proprietary interviews. For example, we examine how major non‑captives are reengineering dealer relationships, how captives are aligning product suites to lifecycle financing, and how independents are segmenting credit risk to sustain yields.
Regulatory and macro dynamics shaping 2026 choices
Regulation and macro forces are converging to shape the competitive calculus for next year:
-
Supervisory focus and rulemaking: Recent CFPB activity — including notice on large participant definitions and interpretive guidance affecting fair‑lending claims — requires firms to revisit sampling, fair‑lending controls, and adverse action processes. The report prescribes specific governance and remediation playbooks to reduce supervisory risk and potential enforcement costs.
-
Originations trend sensitivity: Industry sources point to a modest near‑term softening in overall originations driven by affordability pressures. PW Consulting models alternative origination trajectories and demonstrates how modest volume contractions materially affect unit economics, portfolio turnover, and liquidity needs.
-
Dealer finance dynamics: Growth in dealer‑finance debt and shifting party shares underscore the need to rethink dealer advance facilities, buy‑rate/mark‑up economics, and reconciliation practices to limit credit leakage.
Strategic imperatives and recommended actions for 2026
Based on our modeling and competitive analysis, PW Consulting recommends a prioritized set of actions for executives planning 2026 strategies:
-
Recalibrate dealer economics: Redesign dealer compensation and funding offers to reward volume that aligns with risk‑adjusted margins. Invest in dealer-facing digital tools that compress time‑to‑fund while increasing transparency.
-
Harden compliance posture: Implement a near‑term compliance sprint focused on fair‑lending controls, model governance, and originations reporting to prepare for heightened supervisory attention.
-
Stress‑test funding plans: Run alternative funding scenarios and securitization stress tests that incorporate both mild demand erosion and sudden spread widening to ensure liquidity resilience.
-
Targeted portfolio optimization: Use granular vintage analysis to reweight originations toward the most attractive risk/return cohorts, and consider selling or hedging stressed vintages where economics deteriorate.
-
Pursue selective partnerships: For firms lacking scale, partnering with established bank platforms or technology providers can accelerate capability builds with lower up‑front capital consumption than full build‑outs.
-
Prepare for M&A optionality: Given market concentration metrics, scalable acquirers should accelerate target screening and pre‑deal integration planning — and non‑scale players should develop defensive consolidation strategies.
Scenarios to prioritize in 2026 planning
Three scenarios in our forecast require board attention:
-
Base case (policy steady, demand modest growth): Continuation of current trajectories with moderate growth consistent with the modeled CAGR; management focus on execution and efficiency gains.
-
Downside (affordability shock): A near‑term contraction in originations driven by affordability pressures requires rapid redeployment of capital to preserve liquidity and margin‑enhancing originations.
-
Regulatory tightening: Elevated enforcement or new rules imposing higher compliance costs that compress returns and alter the economics of smaller originators.
Each scenario in the full report includes quantified P&L and balance‑sheet impacts and recommended tactical responses tied to timing horizons (0–6 months, 6–18 months, 18–36 months).
Final notes — the trailer approach
PW Consulting’s Indirect Auto Finance Market report is designed as a strategic decisioning tool for 2026. This briefing highlights the report’s actionable insights and strategic implications while intentionally withholding detailed segment and regional breakout figures. The detailed segment sizes, regional matrices, and per‑company benchmarking tables — along with our full financial models — are available in the report and the accompanying data annex.
If your team is preparing 2026 budgets, capital plans, regulatory remediation roadmaps, or M&A pipelines, the report will convert the market’s macro trajectory and competitive forces into operational moves. For boards and senior leadership teams, it provides the scenarios, diagnostic tools, and tactical playbooks necessary to preserve optionality while capturing profitable growth.
Contact PW Consulting to access the full Indirect Auto Finance Market report, including the granular segment data, competitive scorecards, and the downloadable Excel model that powers our forecasts and scenario analyses.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com