

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: L6 & L7 Quadricycles Market Set to Reach USD 3,887 Million by 2032

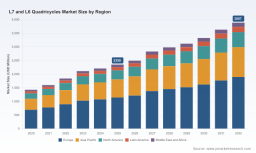
L7 and L6 Quadricycles Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest L7 and L6 Quadricycles Market study (base year 2025) offers a concise, actionable roadmap for companies positioning themselves for growth in the evolving light-quadricycle ecosystem. This preview highlights the report’s strategic value for 2026 decision-making: we demonstrate the market trajectory, competitive dynamics, regulatory pressures, and practical playbooks that senior executives and investment teams need — while reserving the full, granular segment models and company-level datasets for the complete report.
L7 and L6 Quadricycles Market
Market trajectory in one picture
The market for L6 and L7 quadricycles has shifted from niche to mainstream over the last five years. Global market value rose from approximately USD 1,425.5 million in 2020 to USD 2,350.0 million in 2025 (base year). Looking forward, our forecast (2026–2032) projects the sector to expand at a compound annual growth rate of 7.45%, reaching an estimated USD 3,887.0 million by 2032. This sustained expansion reflects accelerating electrification, municipal and commercial fleet procurement, and OEM engagement with micro‑mobility platforms.
L7 and L6 Quadricycles Market
What this means for 2026: companies must treat the quadricycle arena as a growth market that rewards speed of execution, platform modularity, and targeted go‑to‑market playbooks rather than incremental product tweaks.
L7 and L6 Quadricycles Market
Why 2026 is a strategic inflection point
- Regulatory clarity and constraints: EU technical frameworks for L6e and L7e vehicle categories are well-established, creating predictable engineering and homologation boundaries. That regulatory certainty reduces development risk but increases competitive pressure to deliver differentiated value within defined weight, power and speed envelopes.
- Electrification is now the default path: Recent market behavior shows that the majority of new quadricycles in key markets are fully electric. Battery-pack performance, thermal management, and cost per kWh now materially influence product acceptance and lifetime cost of ownership.
- Demand migration from personal to commercial use: Municipal fleets, logistics providers and last‑mile operators are emerging as high‑value customers, creating durable order pipelines and opportunities for recurring service revenue through fleet telematics and battery-as-a-service models.
- Industry consolidation and partnership acceleration: Strategic M&A and platform partnerships are reshaping capability maps — from OEMs leveraging micro‑mobility brands to established quadricycle specialists partnering with battery and e‑powertrain players to scale.
- Moderate market concentration: The sector exhibits a measurable concentration: the top three players account for a significant share of market revenue while the top five consolidate more than half of the market. That structure rewards differentiation for challengers and scale for incumbents.
Competitive landscape — who’s shaping the market
The competitive field blends legacy European specialists, established OEM micro‑mobility arms, and emerging electric‑vehicle specialists. Each archetype follows a distinct strategic playbook:
- European quadricycle specialists: Companies with deep product heritage in light quadricycles continue to dominate in product breadth and dealer networks. These firms are advancing both ICE and electric variants, refreshing model lineups and leveraging brand recognition for urban and professional segments.
- Electric vehicle niche players: Smaller EV-focused manufacturers are capitalizing on lightweight vehicle expertise and fast product cycles to offer high-efficiency, city-optimized platforms that appeal to urban commuters and private buyers.
- OEM micro‑mobility arms: Large automakers and group brands are introducing city‑ready, low‑speed quadricycle offerings, leveraging procurement scale, marketing reach, and platform engineering to accelerate adoption.
Representative industry actors covered in our competitive analysis include established light-quadricycle manufacturers, utility-focused electric vehicle firms, and OEM micro‑mobility initiatives. The report profiles each player’s strategic positioning, product architecture, distribution footprint and recent strategic moves — from partnerships and municipal contracts to acquisitions and product launches.
Recent strategic moves that matter to 2026 planning
- Strategic partnerships to accelerate electrification and modular platforms — incumbent manufacturers are moving quickly to integrate advanced battery and motor systems through alliances rather than in-house development alone.
- Municipal fleet wins are validating utility-focused EV propositions; large municipal tenders are becoming a repeatable revenue channel for manufacturers that can meet customization and service-level demands.
- Targeted acquisitions have broadened product portfolios and geographic reach, enabling faster scaling of electric quadricycle offerings and aftermarket ecosystems.
- High‑visibility product refreshes and new model debuts at major motor shows are serving to reframe brand perceptions and stimulate consumer interest in micro‑mobility ownership.
What’s inside the full PW Consulting report (practical deliverables)
Our full L7 and L6 Quadricycles Market report translates market signals into executable priorities. Key deliverables include:
- Comprehensive market model: Five‑year historical series and seven‑year forecast (2026–2032) with bottom‑up revenue build, sensitivity scenarios and a break‑out of the market’s growth drivers. (Note: full segment tables and company‑level revenue splits are available in the complete report.)
- Scenario analysis and stress tests: Three forward scenarios (Base, Accelerated Electrification, Supply‑Chain Shock) with financial outcomes and strategic implications for product roadmaps, capex timing and inventory policies.
- Regulatory and compliance map: Actionable checklist for homologation, license class implications and country‑level go‑to‑market constraints in major European markets.
- Go‑to‑market playbooks: Tailored commercial strategies for personal-use, last‑mile logistics and municipal customers — including channel economics, pricing matrices, dealer vs direct sales decision trees and service revenue models.
- Technology and cost benchmarking: Comparative analysis of battery pack architectures, e‑motor options, and modular platform approaches to help engineering and procurement teams prioritize supplier partnerships.
- Competitive product matrix and capability gaps: Side‑by‑side comparisons of feature sets, warranty structures and telematics integrations to inform product positioning (full matrices available in the paid report).
- M&A and partnership playbook: Target screening criteria, valuation heuristics and integration checklists for companies seeking inorganic growth or capability partnerships.
- Risk register and mitigation plans: Identification of top value‑chain risks (supply, regulation, technology obsolescence) with prioritized mitigation measures and monitoring KPIs.
- Primary research appendix: Summaries of stakeholder interviews, OEM supplier discussions and municipal procurement officers that underpin our recommendations.
Recommended strategic moves for 2026
Based on our market model and field interviews, PW Consulting recommends five priority actions for executive teams:
- Commit to modular EV platforms: Prioritize vehicle architectures that accept multiple battery sizes and powertrain options to serve both personal and commercial customers without prohibitive retooling costs.
- Target fleet and municipal pilots early: Secure pilot agreements with city administrations and logistics operators to build proof points for reliability, total cost of ownership and service economics. Winning municipal tenders establishes reputational momentum.
- Forge capability partnerships: Where battery and motor expertise is not core, pursue joint development or procurement alliances to accelerate time-to-market while preserving product differentiation.
- Design for service revenue: Embed telematics, battery‑life guarantees, and modular maintenance packages into pricing to extend lifetime value and reduce churn.
- Use staged M&A to fill capability gaps: Consider small, capability‑focused acquisitions to add software, battery remanufacturing or local distribution scale rather than large horizontal deals that dilute focus.
Who should read this report and how to use it
The report is designed for C‑suite leaders, product and engineering heads, corporate development teams, and private equity investors considering exposure to micro‑mobility. It functions as both a strategic playbook and an operational toolkit: use the market model to stress‑test business cases, the scenario work to set investment gates, and the competitive matrices to benchmark offerings before pricing or channel decisions.
As a preview we have shared the headline market trajectory, concentration metrics and the strategic themes that will define winners in 2026. The full report contains the granular segmentations, price and unit models, competitor revenue tables, and procurement tender templates necessary to execute the strategies summarized here.
Next steps
- Download the full report and data workbook to access the detailed segment models, product matrices and company profiles.
- Request a tailored executive briefing with PW Consulting to align the findings to your 2026 business plan and investment priorities.
- Engage our deal team for target screening if you are evaluating acquisitions or partnerships in the quadricycle space.
PW Consulting’s L7 and L6 Quadricycles Market report synthesizes market evidence, regulatory realities and competitive motion into a pragmatic guide for 2026 decision-making. For teams that must move from strategy to execution this year, the right choices now — on platform design, partner selection and customer targeting — will determine who captures the disproportionate share of growth over the coming business cycle.
For detailed analysis of this topic, please visit the official page: L7 and L6 Quadricycles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com