

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rubber Round Belt Market Reaches USD 1,850 Million in 2025, Poised for 4.3% CAGR During 2026–2032

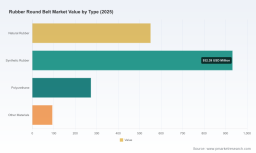
Rubber Round Belt Market — 2026 Strategic Brief (PW Consulting)
Executive snapshot
The global rubber round belt market is entering 2026 from a position of steady expansion and heightened strategic complexity. Our benchmarking model places the market at USD 1,850.0 Million in 2025, with near‑term growth lifting the 2026 estimate to roughly USD 2,013.7 Million and a compound annual growth rate (CAGR) of 4.3% across the 2026–2032 forecast window. By the end of the forecast period the industry is projected to exceed USD 2.4 billion, underscoring a predictable, investible market that nevertheless hides structural inflection points companies must address in 2026.
Rubber Round Belt Market
Why this report matters for 2026 decision cycles
-
Actionable market sizing and scenario analytics that convert a multi‑year forecast into quarter‑by‑quarter implications for supply chain, pricing and capacity planning.
Rubber Round Belt Market -
Concentration metrics that inform competitive strategy — the top tiers of suppliers account for a meaningful share of industry revenue, but the sector remains sufficiently fragmented to reward nimble players with focused execution.
Rubber Round Belt Market -
Real‑world operational levers: raw‑material exposure, regulatory certification, and product differentiation are the primary variables that will determine winners and losers in 2026.
What we found: five strategic forces shaping 2026
-
Material volatility: natural rubber pricing has shown notable short‑term swings. Independent industry measures put a benchmark near USD 1.92 per kg in February 2026, while commodity price series recorded a reading of 222 U.S. cents per kg in May 2026 — a reminder that input cost shock remains a persistent operational risk. Procurement and product teams must integrate volatile feedstock scenarios into commercial plans for 2026.
-
Regulatory and food‑grade demand: increasing adoption of rubber and polyurethane round belts in food processing elevates the importance of food‑grade certifications and hydrolysis resistance. Compliance is no longer a checkbox — it is an enabler for premium pricing and longer aftermarket life cycles.
-
Segment diversification: demand drivers span industrial machinery, conveyor systems, automotive and processing sectors. The resulting portfolio choices — whether to prioritize heavy‑duty power transmission, high‑precision conveyors or food‑safe materials — drive very different R&D and sales strategies.
-
Technology and materials substitution: thermoplastic and engineered polyurethane variants are gaining ground alongside traditional natural and synthetic rubber. Performance tradeoffs (wear, stretch, hydrolysis resistance) are now being optimized across a broader materials palette.
-
Channel and aftersales economics: service, fast‑fulfilment and local stocking are increasingly decisive for end users with uptime‑critical conveyors. Distribution strategy and aftermarket capability can materially increase lifetime value.
Competitive landscape — profiles and strategic implications
Our competitive map synthesizes strengths and strategic postures of established suppliers who will influence market dynamics in 2026. The report contains full profiles, but the following high‑level assessments highlight what buyers and investors should watch this year.
-
Gates Corporation (Denver, Colorado, USA; https://www.gates.com) — notable for heavy‑duty, OE‑exact fit offerings across power round and endless rubber belts. Strength lies in engineered fitment and aftermarket reach; strategic focus should be on cross‑selling service agreements and expanding turnkey solution packages.
-
Dura‑Belt, Inc. (Hilliard, Ohio, USA; https://www.durabelt.com) — specialist in elastic round belts and FDA‑approved urethane options. Their certification expertise positions them well for food processing and hygienic conveyor niches; partnerships with system integrators would accelerate penetration.
-
Habasit (Reinach, Switzerland; https://www.habasit.com) — offers Polycord round belts and has recent technical updates to improve industrial conveying performance. Habasit’s strength is in material science and global standards compliance; continued investment in hydrolysis‑resistant thermoplastic variants is a likely path to premium differentiation.
-
BEHAbelt (Glinde, Germany; https://www.behabelt.com) — focused on weldable PU/TPE round belts and rubber‑like profiles. Their production flexibility supports fast customization; scale expansion or strategic alliances could increase share in modular conveyor builds.
-
Optibelt Corporation (Bartlett, Illinois, USA; https://www.optibelt.com) — supplies RR/HRR series polyurethane and rubber belts across industrial sectors. Their breadth makes them a desirable supplier to multisite manufacturers; value capture will depend on integrated services and contract logistics.
-
Fenner Drives (Manheim, Pennsylvania, USA; https://www.fennerdrives.com) — offers light‑duty Eagle urethane and rubber belting optimized for material transfer. Their channel presence in light industrial and OEM replacement markets is a platform for aftermarket growth.
Recent market signals
-
Buyer's intelligence: a recent third‑party buyer’s guide released in March 2026 highlighted top suppliers and underscored demand for certified rubber options in industrial applications, reflecting buyer focus on risk‑mitigating attributes.
-
Product evolution: in late 2025 a leading supplier updated Polycord data sheets to boost hydrolysis and conveying performance — a market cue that incremental material improvements continue to be a primary competitive lever.
-
Market concentration: our CR3 and CR5 measures indicate meaningful concentration at the top tiers, suggesting opportunities for mid‑market consolidation but also risk of pricing pressure from larger incumbents on commoditized product lines.
What the full report delivers (practical contents for 2026 execution)
PW Consulting’s full market study is designed as a playbook for commercial, procurement and corporate development teams. The report is structured to be immediately operational and includes:
-
Transparent forecasting model with base‑year reconciliation, sensitivity runs and scenario outputs (available as downloadable models).
-
Segment and regional demand dashboards with purchase and life‑cycle assumptions to support SKU prioritization.
-
Raw‑material impact analysis showing pass‑through dynamics and cost‑to‑price elasticity under alternate commodity paths.
-
Competitive benchmark with supplier scorecards, capability heatmaps and product positioning matrices.
-
M&A and partnership target screening criteria optimized to identify accretive bolt‑on assets by capability and geography.
-
Go‑to‑market and channel playbooks for direct OEM sales, distributor partnerships and aftermarket networks.
-
Regulatory and compliance roadmap for food‑grade and hydrolysis‑resistant product lines, including cost/benefit templates for certification investments.
Strategic recommendations for 2026 — a prioritized action checklist
-
Immediate (0–90 days): Stress‑test procurement against commodity scenarios and implement a layered hedging strategy for natural rubber exposure. Reconcile supplier contracts to introduce indexation clauses or fixed volume rebates to protect gross margin.
-
Near term (90–180 days): Accelerate certification lanes for food‑grade and hydrolysis‑resistant products where existing demand and margin uplift justify capital or process investment. Pilot a stocked SKU set with top regional integrators to shorten lead times and command premium service fees.
-
Medium term (180–365 days): Execute portfolio rationalization to favor higher‑margin variants (e.g., engineered PU/thermoplastic blends and certified rubber compounds). For manufacturers, consider modularizing lines to switch between rubber and thermoplastic production with minimal downtime.
-
Strategic (12–24 months): Evaluate roll‑up or alliance opportunities for regional players that add local stocking capabilities or proprietary formulations. Use acquisition targets to plug gaps in aftermarket services and digital ordering platforms.
How buyers, manufacturers and investors should use the report
For procurement leaders: use the forecast and sensitivity analyses to reset contract terms and develop a multi‑supplier hedging playbook. For product managers: the materials roadmap and competitor scorecards will clarify where to prioritize R&D spend. For corporate development teams: the market consolidation mapping and target screening tools will accelerate identification of value‑accretive targets and joint‑venture candidates.
Closing — the PW Consulting difference
This market brief demonstrates the kinds of practical, decision‑ready insight our full report provides: a blended view of macro trajectory (USD 1,850.0 Million in 2025, rising into 2026 at approximately USD 2,013.7 Million and expanding at ~4.3% CAGR through 2032), coupled with operational scenarios and supplier intelligence that translate forecasts into executable 2026 actions. Our intent is to give you enough strategic visibility to act confidently, while preserving the granular tables, models and proprietary supplier metrics that are included in the full deliverable.
Access the complete Rubber Round Belt Market report and downloadable forecast models on the PW Consulting research portal to unlock the detailed segmentation, supplier share matrices and scenario spreadsheets that will be required to finalize budgets, procurement strategies and M&A mandates for 2026.
For detailed analysis of this topic, please visit the official page: Rubber Round Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com