

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automated Marine Debris Collection Equipment Market to Surge from USD 856.0 Million in 2025 to USD 1,945.85 Million by 2032 at a 12.45% CAGR

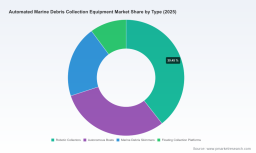
Automated Marine Debris Collection Equipment Market — Strategic Outlook for 2026
PW Consulting’s new market study on Automated Marine Debris Collection Equipment arrives at a crucial inflection point for coastal and inland water management. The segment has moved from niche pilots into repeatable procurement cycles: our analysis shows market value rising from a modest base in 2020 to an estimated USD 856.0 Million in 2025, and, under our core forecast, growing at a 12.45% CAGR through the 2026–2032 horizon to approach roughly USD 1.95 Billion by 2032. For public-sector program managers, corporate sustainability leads, infrastructure investors and technology OEMs, this report is designed as a practical, strategy-grade playbook for 2026 decision-making.
Automated Marine Debris Collection Equipment Market
Why 2026 Is a Pivotal Year
-
Policy acceleration: International and national policy trajectories are hardening around measurable collection and accountability targets. The UN Global Plastics Treaty negotiations and subsequent domestic implementation pathways are creating clearer obligations and funding mechanisms for collection technologies.
Automated Marine Debris Collection Equipment Market -
Funding and procurement momentum: Several governments and multilateral development banks have elevated autonomous and semi-autonomous cleanup systems in their capital programs. This is shifting projects from grant-funded pilots to competitively procured, multi-year service contracts.
Automated Marine Debris Collection Equipment Market -
Technology maturation: Advances in autonomy, low-power propulsion, and AI-based object classification are moving more deployments from proof-of-concept to operational scale—reducing unit operating costs and increasing measurable throughput per deployment.
-
Circularity and materials innovation: Recycled polymers recovered from collected waste are being reused in equipment components, reducing raw material dependency and creating new product lifecycle narratives for procurement specifications.
What the Report Delivers — Operational, Financial and Competitive Tools
The study is deliberately practical. We focus on the decisions you need to make in 2026 and the operational steps to execute them. Key deliverables include:
-
Market sizing and scenarios: A base-case and two alternative adoption scenarios (policy-driven upside and conservative adoption) with clear assumptions so procurement teams can stress-test planning horizons.
-
Procurement & contract templates: Performance-based RFP structures, service-level agreements, maintenance schedules and KPI frameworks that align vendor incentives with quantifiable collection outcomes.
-
TCO and ROI models: End-to-end total cost of ownership models, including capex, variable operating costs, lifecycle replacement schedules, and revenue/offset pathways from recycled material recovery and carbon/ESG credits.
-
Deployment playbooks: Site selection criteria, seasonality risk maps, modular fleet design guidance (mixing stationary collectors, skimmers and autonomous vessels), and stepwise scaling roadmaps from pilot to city/regional operations.
-
Technology assessment: Maturity matrices for autonomy stacks, sensor suites, energy systems and materials; vendor-agnostic evaluation checklists for interoperability and data integration.
-
Supply chain & manufacturing risk maps: Critical component sourcing analyses, lead-time stress tests and mitigation strategies including local manufacturing, parts pooling and material substitution options.
-
Financing and partnership playbook: Options for blended finance, public–private partnerships, concessional funding eligibility, and commercial leasing/as-a-service models tailored to municipal balance sheet constraints.
-
Regulatory and stakeholder map: A jurisdictional guide that matches likely procurement pathways to regulatory environments and civil-society expectations.
Competition and Market Structure — How to Read the Landscape
The segment is neither atomistic nor monopolistic. Our concentration analysis indicates a moderately consolidated supply base—enough scale to standardize best practices while leaving ample room for technology-focused entrants and local integrators. For purchasers and investors this means two practical realities: there are credible partners with proven deployment track records, and there remain opportunities to secure differentiated value via partnerships, performance contracts, and localized service offerings.
Representative vendor archetypes we profile in the report include:
-
Large-scale, river-interceptor organizations focused on high-throughput installations and system-wide programs. These players are advancing programmatic deployments and city-scale partnerships.
-
Autonomous surface vessel specialists that deliver flexible, scalable fleets for ports, harbors and riverine corridors—suited to scalable service models and modular fleet operations.
-
Low-cost, high-density surface collection units optimized for marinas and calm waterways that offer rapid deployment and community-led maintenance models.
-
Engineering firms and system integrators providing containment booms, skimmers and heavy-capacity vessels tailored for industrial port operations and ecosystem restoration projects.
We include company profiles and capability maps for leading producers and integrators, examining business model fit, deployment track records, service capabilities and strategic trajectories. Notable developments that inform our 2026 view include recent large-scale removal milestones and program expansions by established river-interceptor programs, and pilot-to-scale initiatives by autonomy-focused vendors with multilateral bank partners.
Technology and Business Model Inflection Points to Watch
-
Autonomy and sensing: Accurate classification, adaptive routing and swarming strategies materially improve throughput per deployed unit. Procurement decisions in 2026 should favor systems with upgradeable autonomy stacks rather than closed legacy architectures.
-
Energy & propulsion: Battery energy density, modular swap systems and hybrid solar assist change uptime economics. Decision-makers should insist on transparent energy budgets and life-cycle replacement costs in vendor bids.
-
Materials circularity: Designs that incorporate recycled polymers—both as a sustainability narrative and as a risk mitigation strategy against raw material volatility—deliver downstream cost and brand advantages.
-
Service models: As-a-service contracts that bundle deployment, monitoring and disposal/recycling reduce municipal procurement friction. However, they require rigorous performance verification mechanisms to prevent scope creep.
Strategic Imperatives for 2026 Decision-Makers
-
Move from pilots to procurement-ready pilots: Design pilots with procurement-ready KPIs, data collection standards and lifecycle costing so successful pilots can be contracted at scale without repeated bid cycles.
-
Prioritize data and M&V frameworks: Collection volume alone is a weak metric. Invest in standardized monitoring, chain-of-custody for recovered material, and impact reporting aligned with national and international reporting frameworks.
-
Co-design procurement with financing partners: Early involvement of development banks, blended finance providers and ESG investors can convert capital-intensive projects into affordable multi-year service agreements.
-
Stress-test supply chains: Insist on dual-sourcing strategies for critical components and evaluate vendors on the basis of their manufacturing resilience and local content strategies.
-
Lock in circular pathways: Build off-take agreements for recycled outputs into procurement mandates to create revenue offsets and support circular-economy outcomes.
-
Engage in standards development: Participating in standard-setting forums and the early implementation of interoperable data standards yields competitive advantages and helps shape procurement specifications.
How Executives Should Use the Full PW Consulting Report
The executive summary you are reading now is a strategic "trailer" that highlights the report’s core implications. The full study provides the granular decision-support tools you will need in 2026: region- and segment-level forecasts, vendor scorecards with capability matrices, detailed TCO spreadsheets and procurement templates, contract negotiation playbooks, and multi-scenario impact models. These assets enable procurement teams to build evidence-backed RFPs, investors to size and structure deals, and technology vendors to prioritize product roadmaps aligned to buyer willingness-to-pay.
To preserve strategic value and to support active procurement cycles, we have intentionally withheld full segmentation tables and in-depth vendor-by-vendor revenue breakdowns from this release. Stakeholders seeking the complete dataset, full forecast tables, and the operational toolkits should request the full report through PW Consulting’s publication portal.
Concluding Perspective
The automated marine debris collection equipment market is entering a phase in which technology capability, procurement sophistication and policy clarity converge. For organizations making 2026 decisions, the imperative is not merely to buy equipment but to design resilient programs — integrating procurement, financing, operations and downstream recycling. PW Consulting’s study provides the empirical foundation and practical toolset to convert strategic ambition into measurable outcomes.
Contact PW Consulting to obtain the complete report and the accompanying operational toolkits that will allow your organization to translate the 2026 market inflection into durable environmental and financial returns.
For detailed analysis of this topic, please visit the official page: Automated Marine Debris Collection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com