

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydraulic Fracturing Machine Market Poised to Hit USD 29,530.95 Million by 2032, Rising at a 4.85% CAGR Over 2026–2032

Hydraulic Fracturing Machine Market — Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest Hydraulic Fracturing Machine Market study establishes a clear growth arc for the industry as operators, service companies and OEMs navigate tighter emissions targets, rising input costs and accelerating electrification. On a macro basis the global hydraulic fracturing machine market (base year 2025) is estimated at USD 21,200 Million, expanding to approximately USD 22,268 Million in 2026 and tracking toward roughly USD 29,531 Million by 2032 at a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. These headline numbers provide an unambiguous mandate: the sector is growing, but growth is uneven and sensitivity to cost, regulation and technology adoption will determine winners and losers in 2026 and beyond.
Hydraulic Fracturing Machine Market
Why this report matters to boardrooms and strategy teams in 2026
- Translate headline growth into capital prioritization: where to deploy CapEx for highest return and lowest technical/market risk.
- Prepare procurement and supply-chain playbooks to insulate projects from tariff-driven input-cost pass-throughs.
- Align product roadmap, fleet composition and service models with accelerating adoption of electric and natural-gas-powered frac fleets.
- Identify M&A, JV and partnership targets that deliver immediate capability (e.g., e-frac, low-emission engines, digital closed-loop operations).
- Design scenario-driven resilience plans for regulatory shocks and commodity-cycle volatility through 2032.
Market trajectory and strategic implications
From a recovery beginning in the early 2020s to the stabilization observed in 2024–2025, the fracturing machine market has returned to constructive growth. The trajectory from USD ~14.25 billion in 2020 to USD 21.2 billion in 2025 underscores the resurgence of stimulation activity and fleet modernization. The modest but steady CAGR of 4.85% projected for 2026–2032 indicates a maturing market: demand is not exploding, but it is persistent and receptive to technological differentiation.
Hydraulic Fracturing Machine Market
Strategic implication: growth will reward differentiated offerings—machines and service models that reduce lifecycle operating costs (emissions, fuel, maintenance), improve uptime through automation, and lower unit well costs. Generic product portfolios will face margin pressure as customers increasingly value TCO (total cost of ownership) rather than first-cost.
Hydraulic Fracturing Machine Market
Supply chain and input-cost dynamics: what to expect in 2026
Two structural headwinds are shaping vendor economics in 2026: trade policy and raw-material price volatility. U.S. Section 232 tariffs on steel and aluminum, which increased to elevated levels in 2025, continue to pressure the bill-of-materials for trailers, fluid ends and structural components. Steel prices remained elevated into early 2026 (reported at around USD 1,041/ton in April), directly affecting pump housings, frames and pressure-piping costs.
- Actionable mitigations for OEMs and fleet owners: implement hedging strategies for long-lead steel purchases, lock multiyear supply agreements with domestic mills where feasible, and evaluate design changes that reduce steel intensity without compromising reliability.
- For operators: re-negotiate service contracts to include cost pass-through triggers and incentivize fleet modernization programs that lower fuel and maintenance exposure.
- For financiers: stress-test CapEx cases for 10–15% input-cost volatility and require contingency funding for supply dislocations during procurement windows.
Technology evolution: electrification, gas-drive and digital closed-loop operations
2025–2026 marked an inflection in technology adoption. Two parallel shifts are critical: transition toward electric (e-frac) and large-displacement natural gas-powered fracturing fleets to cut diesel dependency and emissions, and the rapid maturation of digital closed-loop platforms for autonomous and optimized stimulation.
- Electric and gas-drive platforms materially reduce OPEX and site emissions; early deployments and partnerships (e.g., Liberty Energy’s collaboration on variable-speed natural-gas engines) demonstrate feasibility at scale.
- Digital closed-loop and autonomous systems—represented commercially by platforms showcased by major service providers—promise to reduce non-productive time and to enable predictive maintenance regimes for pressure-pumping fleets.
- Action items for 2026: run two parallel pilots—(1) retrofit a small fleet to electric/gas-drive for a full-season cost and emission trial; (2) integrate a digital closed-loop control stack with one operator’s realtime telemetry to quantify production uplift and service cost reductions.
Competitive landscape — what to watch in 2026
The hydraulic fracturing equipment and services market retains meaningful concentration: the top three firms account for nearly half of market activity, while the top five account for over 60%—a structural reality that shapes pricing, technology rollout speed and aftermarket dynamics.
- Halliburton (Houston): Leading with integrated service platforms and digital-first solutions. Halliburton’s ZEUS electric pumping units and the ZEUS IQ closed-loop platform indicate a strategy focused on combining hardware modernization with software-driven service monetization. Strategic path for partners/operators: secure early-access trials and co-development agreements to influence product roadmaps.
- Liberty Energy Inc. (Denver): Focused on low-emission fleets (digiFrac/digiPrime). Their partnership activity on gas-drive engines is a model for agile, lower-capex fleet refresh cycles. For investors: Liberty represents a compound play on fleet electrification and near-term diesel-displacement adoption.
- Baker Hughes (Houston): Delivers diversified frac pump line-ups and integrated surface systems, emphasizing reliability at scale. Baker’s breadth makes it a preferred vendor for large operators seeking single-source solutions.
- GD Energy Products (Tulsa): Product innovation on the pump side (e.g., High Flow Series) shows OEM-driven performance gains. Monitor product trials and component durability claims closely—extended component life is a wedge into aftermarket economics.
- ProFrac (Willow Park), NOV (Houston), GOES GmbH (Celle), Forum Energy Technologies (Houston): Each plays differentiated roles—customized fleets, high-horsepower pumpers, regional manufacturing strengths, and power-end specialization respectively. These vendors are potential targets for tactical alliances or bolt-on acquisitions to access technology niches or regional manufacturing footprints.
Recent developments to incorporate into 2026 planning
- Product launches and capability upgrades—new high-flow pump models and electric pumping units—require operators to reassess fleet replacement cycles and retrofit economics.
- Strategic partnerships (natural-gas engine development, digital services) are signaling where integration value will accrue—expect premium pricing for combined hardware+software offerings.
- Tariff and material-price trends necessitate proactive sourcing and flexible contracting. Companies that lock supply and innovate on material use will enjoy durable margin advantages.
Risk and scenario planning: recommended constructs
Successful 2026 strategies will be scenario-driven. PW Consulting recommends building three prioritized scenarios for board approval:
- Base Case (most likely): Moderate demand growth aligned with the 4.85% CAGR, steady migration to electric/gas-drive solutions, and manageable supply-chain friction with periodic cost spikes.
- Upside Case: Accelerated electrification and regulatory incentives lead to faster fleet retirements and higher demand for new-build electric frac fleets—opportunities for OEMs with first-mover advantage.
- Downside Case: Renewed tariff escalation, a sharp downturn in upstream drilling, or a commodity-price shock that defers stimulation activity—necessitates demand-flexible manufacturing and fleet redeployment strategies.
Each scenario should be tested across three tactical levers: CAPEX timing, vendor selection (own vs. outsource), and digital enabling investments. Require a two-year near-term liquidity buffer for downside conditions.
What the PW Consulting report delivers (practical outputs)
We engineered the study to be a decision-grade toolkit for 2026. Key deliverables include (excerpted):
- Top-down and bottom-up market sizing and a demand-driver model calibrated to 2020–2025 historicals and 2026–2032 forecasts.
- Unit-economics models for fleet types, with break-even curves, fleet replacement timing matrices and CapEx/Opex sensitivity dashboards.
- Supply-chain maps highlighting single-source risks, tariff exposure analyses and alternative sourcing scenarios.
- Technology readiness and adoption curve evaluations for e-frac, gas-drive and digital closed-loop systems, plus vendor capability matrices and vendor scorecards.
- M&A and partnership playbooks, including target profiles, valuation frameworks and integration checklists tailored to mid-market and incumbent service firms.
- A regulatory-impact matrix and policy watchlist that connects regional rule changes to procurement and operating-cost implications.
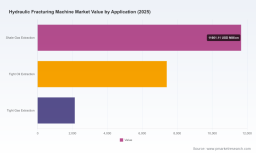
Note: in keeping with our “trailer” approach, core subsegment tables (regional and application splits, and per-product revenue schedules) are summarized in the report and are available through the PW Consulting portal for licensed users. We intentionally surface strategic takeaways here while preserving detailed proprietary tables for report subscribers.
Conclusion — near-term actions for 2026
For executives setting 2026 priorities, the prescription is straightforward: 1) Reassess fleet and CapEx plans through e-frac/gas-drive pilot economics; 2) Harden supply chains against tariff-driven and raw-material volatility; 3) Invest selectively in digital closed-loop capabilities that can be monetized as services; and 4) Rebalance M&A screening to favor capability acquisitions that accelerate low-emission and automation advantages.
PW Consulting’s Hydraulic Fracturing Machine Market report is designed to convert the headline growth into concrete board-level decisions—by providing transparent scenario tools, vendor comparisons and operational playbooks that translate forecasts into executable plans. For access to the full dataset, proprietary segment-level tables, and to book a strategy workshop with our fracturing-machine practice, visit PW Consulting’s report page or contact our industrial energy team.
For detailed analysis of this topic, please visit the official page: Hydraulic Fracturing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com