

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Sound Insulation NVH Market to Grow at 5.85% CAGR, Rising from USD 14.19B in 2025 to USD 21.12B by 2032 — Asia Pacific Leads with USD 8.11B

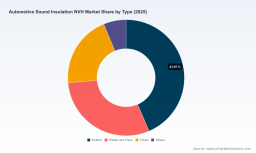
Automotive Sound Insulation NVH Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research — the Automotive Sound Insulation NVH Market Report (base year 2025) — positions 2026 as a pivotal year for automotive original equipment manufacturers (OEMs), suppliers, and tier‑1 integrators. Drawing on a comprehensive historical review (2020–2025) and a forward forecast to 2032, the study quantifies an expanding total addressable market and maps the practical routes organizations must follow to convert regulatory pressure, electrification dynamics, and material innovation into durable competitive advantage.
Automotive Sound Insulation NVH Market
Headline macro view
Key macro takeaways from the study are unambiguous: the global sound insulation NVH market has recovered and accelerated through the early 2020s and reached an inflection at the 2025 base year. Our top‑line forecast shows the market continuing to expand through 2032 at a compound annual growth rate (CAGR) of 5.85%, reflecting a multi‑year structural upswing driven by regulatory tightening, the spread of electric vehicles, and heightened customer expectations for in‑cabin acoustic comfort. In monetary terms this growth translates into a material increase in industry revenue over the forecast horizon (reported in USD Million), underscoring both volume and value opportunities for strategically positioned players.
Automotive Sound Insulation NVH Market
Why 2026 matters: regulatory and technology accelerants
-
Regulatory inflection points. Two regulatory milestones compress timelines and compress the decision window for sound insulation investments: the EU’s phased noise limits (tied to tighter dB(A) thresholds) and the UNECE R51.03 Phase 3 update effective from July 2026, with revised urban weighting and high‑load testing. Together, these require automotive OEMs and suppliers to validate acoustic performance under more stringent and diverse test conditions — not a future consideration but an immediate procurement and design constraint for 2026 VINs.
Automotive Sound Insulation NVH Market -
Electrification alters the NVH problem set. Battery and electric drive architectures reduce engine masking and shift subjective noise drivers toward road, tire, aerodynamic and electrical tonal content. That pivot increases the relative value of passive insulation materials, tuned damping systems, and hybrid solutions (materials + architectural decoupling + targeted active control) — and expands the role of acoustics earlier in vehicle architecture programmes.
-
Sustainability and lightweighting converge with NVH. Suppliers that can deliver high acoustic performance per unit mass and demonstrate recycled‑content credentials will secure preferential design slots. This is not incremental: it materially affects supplier selection, bill‑of‑materials (BOM) economics, and crash/packaging trade‑offs in 2026 platform specifications.
Practical value of the report for 2026 corporate decisions
Clients engaging with PW Consulting will find this report is structured as an operational playbook, not an academic paper. It converts the macro trend (5.85% CAGR and the quantified market trajectory) into prioritized, executable choices across product development, sourcing, pricing, and M&A to be decided in 2026:
-
Product roadmap sequencing — which material technologies and NVH system architectures to fast‑track for 2026 platform launches versus those that can be phased for 2027–2028.
-
Procurement and supplier risk matrices — supplier concentration heatmaps, dual‑sourcing thresholds, and inbound logistics sensitivity to raw material price and recycling policy shifts.
-
Technology investment case templates — NPV and payback analyses for investments in new material lines, adhesive application systems, and active sound control integration, calibrated for 2026 regulatory compliance timing.
-
Go‑to‑market and pricing playbooks — value capture strategies for OEMs and tier‑1s seeking to monetize improved NVH packages while preserving list‑price discipline under cost pressure.
Report contents at a glance (operational modules)
-
Market sizing and growth modelling (2020–2025 historical, 2026–2032 forecast) with scenario stress tests tied to regulatory and EV adoption pathways.
-
Materials performance compendium — comparative matrices (mass, absorption/damping performance, recyclability, cost per effective dB reduction) and targeted application use cases (interiors, powertrain enclosures, underbody, cavity filling).
-
Commercial benchmarking and margin archetypes — supplier margin corridors by technology approach and integration depth.
-
Competitive intelligence dossiers — strategic profiles, recent moves, capability maps and alliance matrices for leading NVH participants.
-
Implementation toolkits — BOM optimization templates, compliance roadmaps for UNECE and EU regimes, supplier selection scorecards, and M&A diligence checklists.
-
Proprietary scenario models — run‑time decision dashboards that let teams quantify trade‑offs between weight, cost, manufacturability and acoustic performance for immediate use in 2026 programme gates.
Competitive landscape and strategic implications
The NVH supply base remains neither fragmented nor oligopolistic — a market structure where leading specialists capture meaningful value but nimble challengers can still win program content through technology or sustainability differentiation. Our report highlights the following strategic archetypes among incumbent and emerging suppliers:
-
Platform specialists (e.g., Autoneum) — firms that combine lightweight fiber‑based systems with high recycled content are consolidating their role in interior acoustic architecture. Their public showcases and conference engagements underscore a two‑pronged strategy: lift acoustic performance while advancing mono‑material and recyclable carpet systems that ease end‑of‑life recovery.
-
Materials innovators (e.g., BASF, Dow) — chemical majors are extending foam, elastomer and engineered polymer portfolios to serve chassis mounts, cavity fillers and tailored dampers. Their advantage lies in material science depth and scale‑up capabilities, enabling faster translation of lab innovations into validated OEM releases.
-
System integrators with specialty know‑how (e.g., Vibracoustic, Sumitomo Riko) — these players focus on engineered mounts, air springs and decoupling systems optimized for EV NVH signatures. Recent program wins for electric pickup trucks and premium segments highlight the premium OEM need for integrated mechanical NVH solutions beyond passive insulation alone.
-
Adjacency players (e.g., 3M, Henkel, ElringKlinger) — firms supplying acoustic adhesives, thin‑film insulations, and sealing solutions are moving up the value chain through higher‑performance laminates and application engineering capabilities, enabling faster in‑vehicle validation cycles.
Observed strategic moves during 2024–2025 demonstrate clear priorities: product showcases at major industry fora; targeted program supply for premium EVs; and the roll‑out of mono‑material and recycled‑content solutions. These moves are consistent with the broader market trajectory and the CR3/CR5 concentration dynamics we map in the report — a competitive field where scale, IP in material science, and early OEM co‑development wins translate into outsized program containment.
Operational recommendations for 2026 planning cycles
-
Accelerate acoustic targets into early architecture phases. Make NVH an explicit 1.0 requirement in 2026 platform definition rather than a later optimization task — test cases in our modelling show this reduces retrofit cost and program risk.
-
Adopt a hybrid sourcing model. Combine long‑term partnerships with material innovators for core acoustic modules and flexible spot contracts for commodity foam and adhesive supply to manage input volatility.
-
Prioritize mono‑material and recycled‑content solutions where mass and end‑of‑life policy overlap; include recyclability KPIs in supplier scorecards to align with regulatory and consumer pressures.
-
Embed regulatory compliance pathways in programme gates. With UNECE R51.03 Phase 3 and tightened EU noise limits becoming binding, acoustic validation and documentation must be completed earlier in the verification chain to avoid costly redesigns.
-
Use M&A selectively to accelerate capability — small bolt‑on acquisitions of acoustic software, measurement houses, or niche materials producers often yield quicker in‑vehicle integration than greenfield investments.
Where the report stops — and why you should read the full study
In keeping with PW Consulting’s “trailer” principle, this press briefing surfaces the strategic implications of the market trajectory and competitive dynamics while intentionally omitting granular segmentation tables and line‑item regional splits that are central to procurement and M&A modelling. The decision‑useful, proprietary segmentation (by region, material type and application), supplier share breakdowns and the downloadable scenario workbooks are available exclusively in the full report and the client portal.
For teams preparing 2026 budgets, platform specifications, or sourcing roadmaps, the full report provides the specific segmented metrics, supplier scorecards, and downloadable modelling templates you will need to move from insight to execution.
Next steps
-
Contact PW Consulting to obtain the full Automotive Sound Insulation NVH Market Report and request an executive briefing tailored to your product line or procurement exposure.
-
Book a workshop to run the report’s scenario models on your vehicle programmes — accelerate compliance planning for UNECE R51.03 Phase 3 and EU noise limits.
-
Request a supplier due diligence deep dive (including on‑site capability assessments) to validate partner claims on recyclability and acoustic performance ahead of 2026 program approvals.
PW Consulting’s team of industry strategists and acoustic engineering specialists stand ready to translate the market’s 5.85% CAGR trajectory and the 2026 regulatory inflection into prioritized actions that protect margin, speed time‑to‑market, and secure acoustic leadership in the electric era.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com