

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automatic Paint Booth Market to grow from USD 855.0 Million in 2025 to USD 1,254.45 Million by 2032 at a 5.65% CAGR

Automatic Paint Booth Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting's latest market research — Automatic Paint Booth Market: 2026–2032 Strategic Outlook — provides an executive-grade, actionable intelligence package designed to shape capital allocation, procurement, and product strategy for industrial manufacturers, body shops, OEM paint shops, and private equity investors entering the space in 2026. Drawing on an evidence base that spans the 2020–2025 historical period and a robust forecast horizon of 2026–2032, the report frames near-term tactical choices within a long‑range view of demand growth, regulatory pressure, and technology adoption.
Automatic Paint Booth Market
Market trajectory at a glance
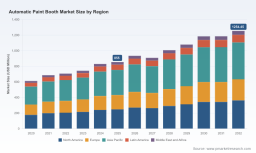
Using 2025 as the base year, PW Consulting’s model shows the global automatic paint booth market expanded from USD 612.45 Million in 2020 to USD 855.0 Million in 2025. Our scenario-driven forecast projects continued expansion through 2032, reaching approximately USD 1,254.45 Million by the end of the forecast period (2026–2032 CAGR: 5.65%). These headline numbers reflect a balancing of cyclical capital expenditure patterns, accelerating automation adoption in higher-volume segments, and the capital intensity of regulatory and sustainability-driven upgrades that are reshaping buying criteria.
Automatic Paint Booth Market
Important nuance: the 2026–2032 path is not linear — the model embeds near-term variability driven by macroeconomic cycles, supply-chain friction (notably steel and specialized filtration media pricing), and a rapid pivot toward waterborne coatings in many end-markets. PW Consulting’s forecast therefore provides both point estimates and alternative scenarios to support contingency planning and capital phasing decisions.
Automatic Paint Booth Market
Why 2026 is a tipping point for procurement and capex
- Regulatory and compliance inflection: Enforcement and guidance under OSHA (29 CFR 1910.107) and EPA NESHAP Subpart HHHHHH are tightening expectations for ventilation, fire-safety construction, and filter capture efficiency. Buyers must now embed compliance validation into procurement specifications rather than treating it as an add-on.
- Coatings technology transition: The industry-wide shift to waterborne coatings increases the importance of precise climate control (typical targets in the sector span 18–25°C and 50–65% relative humidity). Booth selection and HVAC design must be assessed against these operational envelopes to avoid rework costs and warranty exposure.
- Automation and flexibility: Demand is bifurcating: high-throughput OEM and contract finishers prioritize multi-stage automated solutions and robotic integration, while smaller repair and specialty shops favor modular, energy-efficient booths that optimize floor space and TCO.
- Input-price volatility: Raw-material swings — steel and filtration media in particular — are material to manufacturing margins and should inform contract terms, inventory strategies, and supplier selection.
Practical strategic imperatives for 2026
For executives making procurement, manufacturing, or investment decisions in 2026, the PW Consulting report recommends a prioritized, pragmatic playbook:
- Adopt a phased-capex approach: Break large paint-shop projects into validated modules. Prioritize investments that unlock capacity or compliance quickly (e.g., filtration upgrades, climate control retrofits) and defer lower‑ROI automation stages until throughput is proven.
- Require end-to-end TCO metrics in RFPs: Move beyond purchase price — require bidders to provide lifecycle energy consumption, filter replacement schedules and costs, expected production throughput under waterborne coatings, and compliance validation documentation.
- Insist on interoperability and upgrade paths: Specify modular control architectures and open-communication standards (for robotics and IoT) so that initial systems can host future automation or process controls without full replacement.
- Hedge supply‑chain exposure: Secure multi-year or indexed contracts for critical inputs where possible; evaluate regional sourcing and pre-formed kits to reduce lead times and exposure to raw-material spikes.
- Test before scale: Run pilot installations or staged proofs-of-concept to validate waterborne-coating performance and climate-control regimes at production scale before committing to full-array automation.
- Quantify sustainability as an economic lever: Model energy savings and emissions reductions from LED curing, heat-recovery HVAC, and optimized booth airflow — these often produce measurable operating-cost improvements that shorten payback periods.
- Factor in aftermarket and service economics: Prioritize vendors offering fast local service, parts availability, and remote diagnostics; downtime at finishing stages has outsized operational impact.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms hold a meaningful but not dominant share of revenue, and the top five account for roughly half of market receipts. This dynamic creates room for both incumbent expansion and nimble regional or specialist providers to win deals — particularly where local code knowledge, rapid service, and tailored engineering matter.
- Garmat USA (USA) — Strength: code-compliant automotive and heavy-duty repair booths with strong regional support and an emphasis on airflow and safety. Best for repair shops prioritizing regulatory alignment and proven designs.
- Accudraft Paint Booths (SAIMA of North America) (USA) — Strength: high-production automotive and commercial booths plus prep and finishing solutions accumulated over decades; strong option for high-throughput body shops seeking integrated systems.
- Global Finishing Solutions (GFS) (Osseo, WI) — Strength: wide portfolio spanning industrial, automotive, and automated booths including multi-stage options; attractive where turnkey finishing lines and automation are required.
- Blowtherm USA (USA) — Strength: energy-efficient systems with demonstrable case-study outcomes in quality and sustainability; a vendor to watch where energy costs and emissions goals drive procurement.
- RTT Finishing Solutions (Rockwall, TX) (USA) — Strength: engineering focus across diverse applications; recent leadership changes signal an integration phase following acquisition, which may affect vendor strategy and go-to-market execution.
- Spray‑Tech (Rialto, CA) (USA) — Strength: custom-engineered, high-performance booths suited to specialized auto, aerospace, and manufacturing applications where bespoke solutions are required.
- Taikisha USA (Troy, MI) (USA) — Strength: downdraft robotic paint spray booths with a focus on automotive manufacturing environments; best-in-class for large OEM paint shops seeking scale and integration.
- Dürr Systems (Germany, global) — Strength: world-leading automated paint-shop and robotic application technology; strong capability for future-proofed, flexible paint lines — evidenced by public showcases of “paint shop of the future” solutions.
- Marathon Finishing Systems (USA) — Strength: high-performance booths for automotive, industrial, and aerospace customers; useful where performance and reliability are prioritized.
Recent vendor moves in 2025–2026 illustrate the market dynamics: executive appointments following acquisitions, case-study installations demonstrating sustainability and efficiency gains, and vendor showcases of flexible, future-ready paint-shop architectures. These developments highlight two trends: consolidation among service-capable suppliers and a marketing pivot toward sustainability and automation as primary differentiators.
What the PW Consulting report delivers — operational, actionable content
Beyond headline forecasts, the report is explicitly built for practitioners who must convert insight into action in 2026. Key deliverables include:
- Decision frameworks for retrofit vs. greenfield projects, with stepwise capex phasing and break‑even timelines.
- Vendor scorecards and RFP templates calibrated to regulatory compliance, energy consumption, automation readiness, and aftermarket service KPIs.
- Detailed TCO models that quantify energy, maintenance, filter replacement, labor, and downtime exposures under alternative coating regimes (including waterborne scenarios).
- Scenario planning modules for supply‑chain disruption and raw-material price shocks, with mitigation playbooks.
- Regulatory compliance checklists aligned to OSHA and EPA NESHAP requirements and practical verification steps for procurement and acceptance testing.
- Integration roadmaps for staged automation, digital monitoring, and remote diagnostics to protect optionality while reducing upfront risk.
Note: to preserve commercial sensitivity and to guide decision-makers to validated data sources, this public briefing intentionally omits granular splits by region, booth type, and application — those detailed segmentations and vendor-level market share matrices are available in the full report.
Implications for buyers, OEMs, and investors in 2026
- Buyers: Treat 2026 as an inflection year to reframe booth acquisitions as long-lived production assets with embedded software, HVAC, and filtration lifecycles. Require warranty and service clauses that reflect modern operating profiles (waterborne coatings, robotic processes).
- OEMs / Contract Finishers: Prioritize modular automation that can be scaled with demand, and negotiate supplier commitments for upgrades and spare-part availability to reduce time-to-revenue during ramp phases.
- Investors / PE: Look for targets with strong regional service footprints, proprietary installation methodology, and differentiated energy-efficiency offerings — these attributes materially improve exit multiples in this market.
Next steps
PW Consulting’s Automatic Paint Booth Market: 2026–2032 Strategic Outlook is designed to be a working tool for the C-suite, procurement teams, and investors. The full report contains the granular segmentation, vendor share matrices, and downloadable decision tools referenced above. For organizations planning capex or M&A in 2026, early engagement with PW Consulting will enable customized scenario modeling and a tailored vendor selection process that accelerates implementation while controlling compliance and operating risk.
Issued by: PW Consulting — Advanced Industry Practice, Automatic Paint Booth Markets
For detailed analysis of this topic, please visit the official page: Automatic Paint Booth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com