

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rack‑mounted Full Liquid CDU Market Poised for a 9.85% CAGR — A New Era in Data Center Cooling

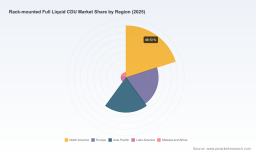
Rack-mounted Full Liquid CDU Market: Strategic Imperatives for 2026 Decision‑Makers
As hyperscale cloud operators, colocation providers and high‑performance compute (HPC) adopters accelerate the shift to direct liquid cooling, rack‑mounted Coolant Distribution Units (CDUs) have moved from niche enablers to foundational infrastructure. PW Consulting’s latest market study — the Rack‑mounted Full Liquid CDU Market Report (base year 2025, forecast 2026–2032) — synthesizes five years of historical data and a forward model that forecasts sustained double‑digit expansion in installed base value. The market reached USD 105.0 Million in 2025 and, under our central scenario, expands to USD 203.45 Million by 2032, representing a compound annual growth rate (CAGR) of 9.85% across the 2026–2032 forecast window.
Rack-mounted Full Liquid CDU Market
Why this report matters for 2026 strategy
-
Timing matters: 2026 is the inflection year for many operators who committed to liquid cooling pilots through 2023–2025. The window for locking in preferred CDU architectures, supplier relationships and thermal‑electrical co‑design practices is now.
Rack-mounted Full Liquid CDU Market -
Investment trade‑offs are complex: the report quantifies the tradeoffs between centralized plant scaling and rack‑level distribution, and translates thermal performance into realistic CAPEX/OPEX scenarios for next‑generation AI and HPC deployments.
Rack-mounted Full Liquid CDU Market -
Risk and compliance vectors are intensifying: updated ASHRAE guidance and testing addenda, together with supply‑chain dynamics from global refrigerant policies, will reframe procurement and service contracts.
Market trajectory and what the numbers mean
PW Consulting’s modeling integrates vendor shipment data, validated field deployments and component cost trends to produce an annualized view of market value and growth. The market climbed from a measured base in 2020 through rapid adoption during 2021–2024, culminating in USD 105.0 Million in 2025. Our forecast indicates a continuation of that trend, more than doubling market value by 2032 under the central growth scenario (CAGR 9.85% for 2026–2032).
For technology buyers this translates into three operational realities: first, a growing aftermarket and service economy for CDU maintenance and spare‑parts; second, accelerating innovation around modular, hot‑swap, and high‑temperature water systems that alter site PUE and water‑side integration; and third, a maturing procurement market where buyers can leverage competitive supplier tiers for risk mitigation and lifecycle cost optimization.
Competitive landscape: established OEMs and fast movers
The rack‑mounted CDU ecosystem is characterized by a mix of specialized thermal OEMs, legacy power & thermal suppliers, and turn‑key systems integrators. Our vendor analysis highlights capabilities and strategic positioning across the supplier set:
-
CoolIT Systems (Calgary, Canada) — deep in‑rack liquid‑to‑liquid expertise with compact CHx series solutions tuned for high‑density HPC and AI racks.
-
Super Micro Computer / Supermicro (San Jose, USA) — integrates redundant, hot‑swappable pump architectures into in‑rack and in‑row CDUs, focusing on high‑availability AI and HPC installations.
-
DCX Liquid Cooling Systems (Warsaw, Poland) — pursues a compact, high‑capacity 4U form factor aimed at dense AI deployments.
-
LiquidStack (Carrollton, USA) — targets ultra‑high capacity and narrow approach temperature use cases with thin‑gap direct‑to‑chip strategies and elevated water temperatures.
-
Flex (via JetCool, Austin, USA) — recently launched a modular rack‑level CDU platform designed to scale across multi‑hundred‑kilowatt to megawatt‑class racks, signaling a systems integrator play into GPU‑dense deployments.
-
Motivair (Schneider Electric, Lancaster, USA) — leveraging Schneider’s channel and service footprint with scalable in‑rack to floor variants for AI factory use cases.
-
Asetek (Denmark, global operations) — provides warm‑water InRack CDU solutions optimized for energy efficiency and simplified plumbing.
-
nVent (Minneapolis, USA) — focuses on reliability and chilled‑coolant delivery systems for high‑uptime environments.
-
Dell Technologies (Round Rock, USA) — brings OEM server/CDU integration with a rack‑mount CDU for dense AI and HPC racks, leveraging installed base relationships with enterprise buyers.
-
Eaton (Dublin/US operations) — positions CDU capability as part of broader thermal and power management portfolios for data center OEM customers.
Competitive dynamics are shifting quickly. Recent product activity — including Flex’s modular JetCool launch (Sept 2025), Motivair’s MCDU‑70 scaled offering (Jan 2026), and Dell’s continued promotion of higher‑capacity rack CDUs — underscores a race for both feature differentiation and scale economics. PW Consulting’s vendor matrices in the full report evaluate these suppliers across technology fit, integration risk, serviceability, and TCO impact to help procurement teams prioritize pilots and rollouts.
Consolidation and concentration: market power matters
The market exhibits moderate concentration by value: the three largest vendors account for a significant share of the market’s commercial value, and the top five participants establish a clear second tier. This structure creates both negotiating leverage for large buyers and a bifurcated channel where specialist integrators and OEMs compete on service depth versus scale. Our competitiveness heatmaps and procurement playbook help buyers navigate preferred‑supplier selection while preserving optionality for future architecture shifts.
Standards, regulation and supply‑chain shocks
-
Standards: ASHRAE Technical Committee updates — notably the inclusion of liquid‑to‑liquid CDU test methods in Standard 127 and guidance from ASHRAE TC 9.9 on isolating facility water from technology cooling loops — are raising the bar for performance certification and installation practice. Compliance will increasingly be table stakes in enterprise RFPs.
-
Regulatory and materials pressure: global refrigerant phase‑down measures (Kigali Amendment) and related certification requirements are increasing production and compliance costs across thermal components. Suppliers with diversified coolant strategies and robust materials sourcing will be advantaged.
-
Operational risk: as liquid cooling moves deeper into mission‑critical stacks, failure modes, service SLAs and spare parts logistics become material to availability. The full report quantifies downtime dollar exposures and models maintenance contract structures suitable for different risk appetites.
Report practicalities: what’s inside and how it helps buyers in 2026
PW Consulting’s study is designed as a practical director‑level toolkit rather than a purely descriptive market brief. Key deliverables inside the report include:
-
Market sizing and scenario models — transparent inputs and sensitivity analysis for CAPEX/OPEX tradeoffs across 2026–2032.
-
Vendor scorecards — comparative evaluation of technical fit, integration risk, service footprint, and supplier financial resilience.
-
Deployment playbooks — step‑by‑step checklists for pilot planning, site plumbing & mechanical integration, commissioning and lifecycle maintenance.
-
TCO and ROI tools — downloadable calculators that convert thermal metrics (approach temp, delta‑T, pumping energy) into financial outcomes under multiple electricity and water price scenarios.
-
Procurement templates — RFP language, SLA constructs, and acceptance test plans that align with ASHRAE test addenda and industry best practices.
-
Risk & compliance matrix — mapping of regulatory drivers, product certification needs, vendor mitigation options, and contractual language to manage transition risks.
Deliberately, the report follows a “trailer” principle in its public outputs: we demonstrate analytical depth and operational rigor, but we withhold the full granular segmentation tables, confidential supplier scoring and unit‑level pricing models from the public summary. These datasets are integral for procurement negotiations and scenario planning; qualified buyers are invited to access the full data package via our report portal.
Actionable recommendations for 2026
-
Convert pilots into modular rollouts where possible. The economics of rack‑level CDUs improve materially at scale when paired with predictable maintenance contracts and integrated monitoring.
-
Embed ASHRAE‑aligned acceptance tests into procurement. Demand vendor certification against the updated test methods to de‑risk integration and operational performance.
-
Negotiate spare‑parts and hot‑swap agreements. Given the criticality of pump assemblies and heat‑exchange modules, defined MTTR targets and logistically enabled spares will reduce exposure to costly downtime.
-
Stress‑test total cost scenarios against water and electricity sensitivity. Our TCO tools show threshold points where liquid cooling achieves decisive cost advantage — these should be used to set internal gating criteria for wider adoption.
-
Prioritize vendors with demonstrable system‑level experience. Firms that can manage both server integration and facility interfacing reduce project friction and accelerate time‑to‑value.
Next steps
Organizations preparing procurement strategies, capital plans or technical roadmaps for 2026 should treat rack‑mounted CDUs not as peripheral accessories but as strategic components that influence server architecture, site planning and long‑term energy strategy. PW Consulting’s Rack‑mounted Full Liquid CDU Market Report supplies the modeling, vendor intelligence and operational playbooks required to convert opportunity into measurable business outcomes.
To request the full report package, detailed vendor scorecards, and access to our interactive TCO models, visit PW Consulting’s research portal or contact our industry team for a briefing tailored to your deployment profile.
For detailed analysis of this topic, please visit the official page: Rack-mounted Full Liquid CDU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com