

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Optical Distribution Frame Market to Reach USD 1,685.09 Million by 2032
By pmarketresearch, 2026-07-22
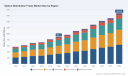
Optical Distribution Frame Market — Strategic Intelligence for 2026 Decision-Making
As communications networks scale to meet the demands of AI, cloud-native services and densified metro and edge access, the Optical Distribution Frame (ODF) market is entering a decisive growth chapter. PW Consulting’s latest industry study — anchored on a 2025 base year and projecting through 2032 — translates historic performance and forward-looking scenarios into a practical strategic playbook for executives, product leaders and investors planning actions in 2026. This preview highlights the report’s strategic value, outlines the market trajectory and competitive dynamics, and describes the operational deliverables that will directly inform capital allocation, product roadmaps and go-to-market choices. To preserve the tactical edge our clients pay for, detailed sub-segment tables and granular regional splits are intentionally withheld here; those datasets are available in the full report.
Optical Distribution Frame Market
Why this research matters in 2026
- Align CAPEX with structural growth: The ODF market has shifted from steady replacement cycles to capacity-driven expansion. Executives need validated forecasts to justify multi-year procurement and manufacturing investments.
- Prioritize product architecture choices: Decisions between ultra-high-density hyperscale designs, modular rack systems and service-oriented wall/floor mounts have material margin and lifecycle implications. Our analysis maps expected demand profiles to technical trade-offs.
- Mitigate supply-chain and sourcing risks: The study identifies bottlenecks, alternative materials and supplier concentration risks that will influence lead times and component cost volatility during 2026 procurement windows.
- Guide M&A and partnership activity: With the market showing measurable concentration among incumbents, targeted acquisitions and JV frameworks can accelerate scale or bring complementary technology into your portfolio.
- Inform go-to-market segmentation: Field sales and channel strategies must balance hyperscale wins against large telco and enterprise accounts. The report provides the evidence base to reweight commercial investments.
Market trajectory — the macro story
ODF demand has shown consistent expansion over the past half-decade and is poised to accelerate as network operators and data center builders densify fiber terminations. PW Consulting’s topline sizing traces this evolution: the global market expanded meaningfully during 2020–2025 as fiber deployments and data-center capacity ramped, and our baseline projection anticipates a near-term uplift in 2026 followed by sustained growth through 2032. Quantitatively, the study uses a 2025 base-year figure to calibrate models and applies scenario-driven adoption curves to generate a forecast path that converges on a multi-hundred-percent cumulative increase by the end of the planning window. The underlying compound annual growth rate (CAGR) we apply for the forecast period is 9.5%, reflecting a mix of replacement cycles, new-build hyperscale installations and accelerated last-mile fiberization initiatives.
Optical Distribution Frame Market
Two implications drive the strategy we recommend: first, investment timing matters — early movers who scale pre-assembled, high-density ODF platforms will capture premium hyperscale and enterprise projects; second, flexibility is essential — modular and front-access platforms will remain attractive to customers seeking lower-risk integration and staged deployment.
Optical Distribution Frame Market
Demand drivers and technology vectors
- Hyperscale data-center densification: AI workloads and converged routing fabrics are increasing fiber terminations per rack. High-splice-count, pre-assembled ODFs that simplify installation and reduce fiber handling are gaining traction.
- Telco fiberization and PON wave: Continued national broadband initiatives and operator upgrades to higher-split PONs drive telecom-grade ODF adoption in both central offices and cabinetized deployments.
- Edge and micro data centers: As computing moves closer to end users and devices, demand for compact, easy-to-service ODFs in non-traditional facilities is rising.
- Serviceability and automation: Features such as tracer fiber circuits, light-guidance for identification and tool-less modularity materially reduce mean time to repair and installation labor costs — differentiators in procurement decisions.
Competitive landscape — positioning and dynamics
The ODF market combines incumbent scale players with specialized manufacturers delivering verticalized solutions for hyperscale, telecom and enterprise customers. Market concentration metrics show that the top three vendors account for a substantive share of global revenue, and the top five further extend that concentration — a structure that favors firms with integrated product portfolios and world-class channel footprints.
- Amphenol Network Solutions (Liberty Lake, WA): Traditionally focused on high-performance connectivity, Amphenol has pushed into the hyperscale ODF niche with pre-assembled, very-high-splice-count frames that emphasize rapid deployment and lower onsite labor. Recent product introductions highlight single-fiber splicing support and tracer-fiber guidance — capabilities that directly address AI-driven data center mesh requirements.
- Huawei Technologies (Shenzhen): Huawei continues to field indoor-focused ODF series tailored for carrier access and cabinet applications. Their product set targets compatibility with standard rack sizes and high port counts in a compact footprint — a profile that appeals to telco operators modernizing access fabrics.
- CommScope (Hickory, NC): CommScope’s modular ODF platforms emphasize front-access serviceability, tool-less installation and ecosystem interoperability. Their platforms are positioned to win in environments that prioritize staged growth and cross-vendor patching simplicity.
Strategically, these vendors illustrate three viable go-to-market archetypes: hyperscale-first (pre-assembled, ultra-dense frames), carrier-optimized (space-constrained, standard cabinet compatibility) and modular-serviceable (field-configurable, integration-friendly). Each archetype carries distinct margin profiles, channel requirements and R&D imperatives.
Recent industry signals
Product innovation is accelerating. For example, a notable 2026 product launch introduced a hyperscale ODF capable of very high splice counts per frame and integrated tracer-fiber identification, packaged for pre-assembled deployment. This kind of product underscores how suppliers are responding to labor scarcity, on-site deployment risk and the need to compress build-out schedules for AI-capable facilities.
What the full PW Consulting report delivers
Our full study is structured to be immediately actionable for commercial, product and corporate development teams. Highlights include:
- Comprehensive market sizing and validated forecasts (historical 2020–2025 base, 2026–2032 forecast) with scenario modelling calibrated to infrastructure spend cycles and data-center capacity plans.
- Demand-driver analysis that links fiber counts, splice requirements, and deployment typologies to product specifications and service-cost outcomes.
- Supplier and product benchmark profiles, including technology capabilities, manufacturing footprint considerations and route-to-market assessments.
- Commercial playbooks for targeting hyperscale, telco and enterprise accounts — including tender positioning, specification negotiation levers and value-based pricing templates.
- Supply-chain risk mapping and mitigation options, highlighting critical components, lead-time hedges and alternative sourcing strategies.
- Scenario-based financial models and an interactive dataset that allows executives to stress-test revenue, margin and investment outcomes under different adoption curves.
- Go-to-market checklists, procurement-ready RFP language, and M&A screening criteria tailored to the ODF space.
Note: granular sub-segment tables and regional breakdowns are part of the full dataset; they are excluded from this preview to preserve the proprietary value delivered to PW Consulting’s clients.
Strategic takeaways and recommended actions for 2026
- For the C-Suite: Treat ODF strategy as a capacity-and-serviceability decision, not just a component purchase. Use the 9.5% forecast growth framework to align three-year CAPEX plans with anticipated order cadence, and prioritize suppliers who can guarantee delivery windows and pre-assembly options.
- For Product Leaders: Accelerate development of modular, tool-less designs and integrated tracer or identification features. A differentiated serviceability story reduces lifecycle operating expense — an increasingly persuasive procurement argument.
- For Supply-Chain Leaders: Secure long-lead items with multi-year purchase agreements and qualify second-source suppliers for critical polymer and metal components. Reducing lead-time variability is a high ROI activity in 2026.
- For Go-to-Market Teams: Create parallel plays: one focused on hyperscale and cloud builders with turnkey, pre-assembled offers; another that addresses telco retrofit and cabinetized installations with flexible rack and wall-mount options.
- For Corporate Development: Use the market concentration landscape to identify bolt-on acquisitions that either increase share in a target archetype or add niche capabilities (e.g., tracer fiber tech, splice automation) that accelerate differentiation.
How to use this briefing and next steps
This article is a strategic preview: it sets the agenda and outlines the action priorities for 2026. Executives ready to translate these insights into executable plans should access the full PW Consulting report for the underlying datasets, segmented forecasts and supplier scorecards. The full deliverable includes editable financial models, RFP language and an interactive dashboard to explore scenarios by geography, installation type and buyer segment — tools necessary to convert insight into competitive advantage.
PW Consulting is available to run bespoke workshops in which our analysts will apply the report’s models to your specific network plans and procurement timelines, producing a prioritized, time-phased investment and sourcing roadmap for 2026–2028.
Closing perspective
ODFs are no longer commoditized junctions in fiber networks — they are strategic enablers that influence deployment speed, operating cost and long-term serviceability. With the market expanding on a trajectory that implies durable demand growth, decisions made in 2026 about product architecture, supplier relationships and inventory strategies will materially affect competitive position through the next cycle. The PW Consulting study equips leaders with the quantitative baseline, competitive context and tactical playbooks necessary to navigate this inflection point. For the detailed segment tables, vendor scorecards and actionable models that power procurement and strategic decisions, consult the full report.
For detailed analysis of this topic, please visit the official page: Optical Distribution Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Logistics Robots Market Set to Soar at 16.8% CAGR Through 2032
By pmarketresearch, 2026-07-22
Logistics Robots Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As supply chains transition from episodic automation pilots to fleet-wide orchestration, 2026 marks a decisive year for enterprise leaders deciding where — and how fast — to invest in logistics robotics. PW Consulting’s Logistics Robots Market research (base year: 2025) synthesizes five years of historical performance and a seven-year forecast to 2032, translating market momentum into executable strategy. Our aim here is to preview the strategic value of the full study: enough technical and commercial depth to inform boardroom debate, while reserving the granular segmentation that drives vendor selection and ROI modelling for the full report.
Logistics Robots Market
Market Trajectory: What the numbers signal for 2026 decisions
The logistics robotics market has moved from niche automation to rapidly scaling operational platforms. According to our base-year calibration, the market expanded materially between 2020 and 2025, rising from roughly the low double‑digit millions to a mid‑hundreds figure in 2025 (USD, Million). Our forecast projects that the market will continue to expand at a robust compound annual growth rate of 16.8% across the 2026–2032 horizon, reaching approximately USD 295.0 million by 2032. Put simply: the industry is not only growing — it is compounding — and that growth is concentrated in use cases that integrate robotics with software-first orchestration and service economics (RaaS and managed automation).
Logistics Robots Market
For decision-makers, three implications are immediate: first, early adopters who standardize on modular, upgradeable architectures will extract disproportionate value; second, procurement windows in 2026 will be shaped by supplier roadmaps and component constraints (steel, control electronics); third, capital allocation should prioritize integration and change management as much as hardware acquisition.
Logistics Robots Market
Why 2026 is an inflection year
- Standards and regulations are converging. The updated ANSI/A3 R15.06-2025 safety standard and related global harmonization efforts raise the bar for functional safety and cybersecurity in logistics robotics. Enterprises that anticipate compliance costs and build them into total cost of ownership calculations will avoid downstream remediation expenses and delays to go‑live.
- Commercial models are maturing. The services economy in robotics (RaaS) has been growing rapidly; industry data documented a sharp increase in RaaS uptake and a near‑term shift to subscription and outcome-based contracting. This changes procurement calculus from CapEx-first to operational agility and lifecycle economics.
- Supply-chain pressures are real. Raw material and tariff dynamics, notably steel-related cost increases in 2025, have altered vendor pricing and lead times. Procurement in 2026 must balance speed-to-automation against negotiated supply guarantees and localization tradeoffs.
What the PW Consulting report delivers (practical, action-oriented)
This research is structured to be an operational playbook for 2026 decision cycles, not a theoretical survey. Key deliverables include:
- Executive dashboards that translate market-scale forecasts into budgetary scenarios and expected payback periods under three adoption profiles (pilot, phased roll-out, and enterprise-wide deployment).
- Vendor shortlists and capability maps that align solution archetypes (mobile fleets, robotic arms, high-density systems, humanoid and embodied platforms) with business objectives and warehouse typologies — without prescribing a one-size-fits-all supplier.
- Implementation roadmaps with milestone checklists for site surveys, safety validation (including updated standards), systems integration, change management, and KPIs for operational acceptance.
- Risk matrices covering regulatory, supply-chain, cybersecurity, and labour transition exposures — each with mitigation playbooks and contract clause templates tailored to 2026 negotiating contexts.
- Financial tools: configurable TCO calculators, CapEx vs OpEx modelling (including RaaS), and sensitivity analysis for input-cost inflation and throughput variability.
- Scenario-based projections linking robotics investments to service-level improvements, workforce re-skilling needs, and carbon/energy outcomes.
Competitive landscape: strategic reads on leading suppliers
The market shows moderate concentration with the top three players accounting for a meaningful share and the top five commanding a clear majority of revenue, signaling that scale and integrated solutions matter. However, specialist innovators continue to redefine use cases and price-performance.
- Geek+ (Hong Kong, https://www.geekplus.com) — A leader in embodied intelligence and AMR fleets. Geek+’s integrated platform strategy positions it well for large fulfillment customers seeking an end-to-end vendor capable of scaling across sites. Their recent trade-show unveilings underscore a continued push on software-first fleet orchestration.
- Locus Robotics (United States, https://locusrobotics.com) — Focused on pick-optimized AMRs and multi-robot coordination. Locus has become a preferred partner for retailers and 3PLs balancing throughput gains with incremental deployment risk.
- SEER Robotics (Europe, https://seer-robotics.ai) — A profile to watch: SEER’s recent product launches in 2026 (AI Delivery P300, embodied wheeled humanoid base) reflect aggressive moves into final-mile and intra-site humanoid-enabled logistics. Their early deliveries of embodied intelligent forklifts show an applied approach to niche, high-value workflows.
- Rapyuta Robotics (Japan, https://www.rapyuta-robotics.com) — Specializes in cloud-robotics and ASRS augmentation. Rapyuta’s platform-centric upgrades showcased at MODEX 2026 highlight the commercialization of cloud-native orchestration for mixed fleets.
- Addverb Technologies (India, https://www.addverb.com) and Exotec (France, https://www.exotec.com) — Both vendors continue to push density and throughput boundaries with carousel and Skypod-like systems. Product refreshes in early 2026 signal incremental densification and software advancements that affect site footprint decisions.
- Major integrators and robotics veterans — Amazon Robotics, Symbotic, ABB, KUKA, Toyota Industries, Fanuc, Yaskawa, KION Group, Daifuku and others remain influential through proprietary deployments, OEM partnerships, and global service networks. Their scale advantages and ecosystem reach are decisive for multi-site, multinational rollouts.
- Emerging form factors — Companies such as Agility Robotics are commercializing humanoid tote-handling capabilities that reframe automation beyond today’s pallet-and-shelf paradigms. These entrants create strategic optionality for logistics executives planning five‑plus year transformation roadmaps.
Recent vendor activity through 2026 — from product launches to live demonstrations — is accelerating the rate at which proof-of-concept results migrate to site-wide adoption. Our competitive profiles in the full report go beyond press releases: we validate claims through deployment telemetry, integration case studies, and independent performance benchmarks.
Market dynamics and risks to model in 2026 plans
- Regulatory headwinds and tailwinds. New safety standards and targeted national strategies (for example, regulatory innovation pathways for delivery robots) will create both compliance burdens and clearer routes-to-market. Early alignment with standards reduces change-order risk.
- Cost volatility. Input-price inflation, tariff regimes, and localized manufacturing incentives will create heterogenous TCOs across geographies. Procurement strategies should lock favorable terms for long-lead components and consider diversified sourcing.
- Software and integration risk. Hardware is increasingly commoditized; value accrues through orchestration, telemetry, and AI-driven optimization. Prioritize vendors with open APIs, active SDKs, and strong third-party integration references.
- Labor and social license. Workforce implications are material. Successful deployments pair automation with reskilling programs and clear communication strategies to maintain productivity and community support.
How to use this research in your 2026 decision cycle
- Use the report’s scenario models to set budget envelopes for Q2–Q4 procurement cycles and to stress-test payback timelines under input-cost and throughput variability.
- Apply the vendor capability maps and shortlists to reduce RFP cycles; combine our recommended technical must-haves with your operational KPIs to create non-negotiable selection criteria.
- Adopt the report’s phased implementation templates to align IT, facilities, compliance, and HR stakeholders around a single integrated launch plan — the velocity of benefit capture depends as much on organizational readiness as on vendor performance.
- Leverage our risk matrices when negotiating contracts to transfer key supply and compliance risks to vendors or insurers, and to structure milestone-based payments tied to verified performance metrics.
Conclusion: the strategic choice in 2026
Enterprise leaders face a binary strategic test in 2026: treat logistics robotics as an incremental efficiency program, or reposition it as the operating model around which fulfillment and distribution competitiveness is built. The market’s trajectory — demonstrated by the five‑year historical expansion and a forecasted climb to roughly USD 295.0 million by 2032 at a 16.8% CAGR over 2026–2032 — favours organizations that act decisively and architect for upgradeability.
PW Consulting’s full Logistics Robots Market report converts market-scale insight into concrete acquisition, integration, and governance actions. It intentionally preserves certain granular segmentation metrics and vendor-level performance matrices within the full document to enable validated procurement. Contact us or visit the report landing page to access the complete analysis, vendor scorecards, and the interactive financial tools that will be essential for your 2026 investment cycle.
For detailed analysis of this topic, please visit the official page: Logistics Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Retrievable Filters Hold 76.8% — IVC Market to Reach USD 212M by 2032 at 9.4% CAGR
By pmarketresearch, 2026-07-22
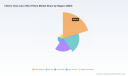
Inferior Vena Cava (IVC) Filters Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented introduction to our full Inferior Vena Cava (IVC) Filters Market study. This briefing distills the strategic imperatives that will shape commercial, clinical, regulatory, and M&A decisions in 2026. It is grounded in an evidence-led view of historical performance (2020–2025), a clear baseline (base year 2025), and a forward-looking forecast spanning 2026–2032. The market demonstrates robust momentum, expanding from a modest multi-year base to an expected market more than one-and-a-half times larger by 2032, with a compound annual growth rate (CAGR) of 9.4% across the forecast window. Use this briefing to orient strategy; consult the full report for the detailed models, regional and application breakdowns, and product-level revenue curves we intentionally reserve for subscribers.
Inferior Vena Cava (IVC) Filters Market
Why This Study Matters for 2026
-
Market inflection: After steady recovery and investment in device innovation through 2020–2025, the IVC filters market is entering a phase of accelerated adoption driven by device design advances, improved retrieval technologies, and renewed regulatory focus on safety and post-market surveillance.
Inferior Vena Cava (IVC) Filters Market -
Capital allocation clarity: The projected 9.4% CAGR and the modeled revenue trajectory for 2026–2032 create a clear basis for prioritizing R&D, capacity investment, and M&A. Whether your objective is share gains, tuck‑ins for complementary retrieval technologies, or bolstering clinical evidence, the market’s profile supports selective, high-conviction investments.
Inferior Vena Cava (IVC) Filters Market -
Risk/reward balance: Litigation legacy, device recalls, and tightening regulatory controls make risk management as valuable as growth capture. The study equips boards and deal teams with quantifiable scenarios that link legal exposure, regulatory timelines, and cash flow sensitivity to strategic choices.
Market Trajectory and Drivers (High-Level)
Our bottom-up modeling shows the market value climbing meaningfully from 2020 to 2025 and continuing to expand through 2032. The combination of demographic trends (ageing populations and rising VTE incidence), procedural adoption, and a shift toward retrievable and retrieval-support technologies underpin the forecast. Key demand drivers include clinical guideline evolution, physician preference for devices that balance protection and retrievability, and the commercial roll‑out of advanced extraction tools that lower the procedural risk and increase the likelihood of successful removals.
On the supply side, manufacturers are responding with innovations in filter geometries, convertible/permanent design options, and adjunct tools (e.g., specialized sheaths and laser-assisted retrieval devices). These technology adjacencies are materially widening the addressable market for acute and complex retrieval procedures.
Regulatory and Legal Dynamics
-
Regulatory tightening and clarity are reshaping the competitive playing field. Past safety communications have emphasized timely retrieval of retrievable filters; regulators continue to focus on post-market performance and retrieval success rates. In early 2026, a final order formalized special controls for a class of laser-powered retrieval catheters, signaling a new regulatory baseline for advanced removal technologies.
-
Not all regulatory news is favorable: voluntary recalls and recalls driven by field reports continue to remind market participants of the operational and financial impacts of quality events. Recent recalls related to introducer system issues have highlighted the importance of human factors engineering and robust device-exchange protocols between manufacturers and clinicians.
-
Legal exposure remains a material consideration for incumbent manufacturers and new entrants alike. Products that have been on the market longer face legacy litigation and evolving case volumes; companies must factor potential remediation costs and reputational impacts into valuation and commercial planning.
Competitive Landscape — Who Matters and Why
The competitive picture is dominated by a set of established interventional device players with entrenched product franchises. Key firms we profile in the full report include (but are not limited to) manufacturers whose portfolios combine filters and retrieval technologies:
-
Cook Medical — known for clinical-focused optional/retrievable filters with long-standing adoption among interventional radiologists and vascular surgeons.
-
Becton, Dickinson and Company (BD) — competing with a contemporary generation of filters and leveraging broad distribution channels.
-
Argon Medical Devices — offers retrievable filter systems and has recently navigated a recall matter that underscores quality control and supply risk considerations.
-
Cordis (Cardinal Health) — provides both retrievable and permanent filter designs; their portfolio decisions influence institutional purchasing patterns.
-
B. Braun Interventional Systems — competes with convertible filter designs and has clinical programs supporting differentiated use cases.
-
ALN Implants Chirurgicaux — a European device player with optional filters and extraction system capabilities, illustrating regional innovation pathways.
Our analysis juxtaposes product-level attributes (e.g., retrievability window, retriever compatibility, introducer profiles) with clinical evidence strength, post-market event histories, and commercial reach. The full report contains proprietary competitive scorecards, product roadmaps, and playbooks for how to displace incumbents or defend share.
Recent Developments to Watch
-
Device recalls and field corrections have immediate procedural and reputational consequences; they also create short-term demand windows for competitors with unaffected inventories and robust customer support.
-
Regulatory recognition of advanced retrieval tools, including laser-assisted sheaths, is shifting the standard of care for difficult removals. This creates a two-tier market opportunity: core filter sales and a growing adjunct market for specialized retrieval devices and consumables.
-
Active multidistrict litigation related to device complications remains a background risk that companies must proactively manage via surveillance, registries, and transparent remediation programs.
Strategic Imperatives and Playbook for 2026
For leaders preparing budgets and roadmaps in 2026, the report translates macro trends into a practical set of priorities. Below are the distilled strategic moves that differentiate winners from followers:
-
Invest in retrieval ecosystems, not just filters. Companies that bundle filters with clinician-friendly retrieval tools and training see higher long-term retrieval rates and improved clinical reputation.
-
Build a clinical evidence engine. Sponsor focused registries and investigator-initiated studies that demonstrate retrieval success, complication avoidance, and real-world device performance to support adoption and counter litigation narratives.
-
Elevate post-market surveillance and complaint handling. Rapid, transparent field actions and clinician support limit downstream legal exposure and preserve hospital relationships.
-
Pursue selective M&A to acquire differentiated retrieval technologies, laser adjuncts, or regional distribution that accelerate time-to-market and fill portfolio gaps without overpaying for commoditized filter designs.
-
Design regulatory-first product development pathways. Early engagement with regulators and robust human factors packages de‑risk approvals and reduce post-market constraints.
-
Operationalize flexible manufacturing and inventory hedges to manage recall-driven demand swings and supply disruptions.
-
Engage payers and hospitals on value: quantify procedure economics, length-of-stay impacts, and downstream cost offsets from successful retrievals to secure favorable hospital contracting and coding support.
What the Full Report Delivers (Practical Components)
PW Consulting’s full study is built for action. Subscribers receive:
-
Dynamic financial model (2020–2032) with scenario toggles for regulatory shocks, litigation exposure bands, and retrieval technology adoption curves;
-
Commercial playbooks by target buyer (hospital systems, ambulatory surgical centers, physician groups) and by route-to-market (direct, distributor, OEM);
-
Product-by-product competitive matrices and patent/clearance timelines;
-
Regulatory and legal timeline with decision triggers and contingency playbooks for recalls or adverse events;
-
Deal pipeline and M&A scorecard that prioritizes targets by strategic fit, integration complexity, and free-cash return potential;
-
Risk heat maps and an actionable roadmap for mitigating litigation, regulatory, and reimbursement headwinds.
Concluding Guidance
2026 is a pivotal year: the IVC filters market is large enough to justify focused investment yet dynamic enough that differentiation—through retrieval solutions, clinical evidence, and disciplined regulatory engagement—will determine who captures disproportionate value. The market’s projected growth and shifting technology landscape create attractive opportunities for well-timed product launches, targeted acquisitions, and differentiated service models. However, success requires integrating risk management into commercial strategy from day one.
PW Consulting’s full report provides the granular segmentation, regional and application-level forecasts, and product revenue curves required to operationalize the priorities outlined here. For executives mapping capital allocation, product roadmaps, or M&A pipelines, the complete intelligence is available on our research portal and includes the models and appendices necessary to move from insight to implementation.
For detailed analysis of this topic, please visit the official page: Inferior Vena Cava (IVC) Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Cabin Air Filter Market Poised for 5.8% CAGR Through 2032
By pmarketresearch, 2026-07-22
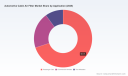
Automotive Cabin Air Filter Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As vehicle interiors evolve into multi-functional, health-sensitive environments, the automotive cabin air filter market has entered a phase of sustained, regulation-driven expansion. Our PW Consulting base-year analysis (2025) anchors a detailed forecast covering 2026–2032. The global market—measured on an annual revenue basis in USD Million—grew from approximately 3.0 billion in 2020 to roughly 3.5 billion in 2025 and is projected to reach just over 5.1 billion by 2032, implying a compound annual growth rate of 5.8% across the forecast window. For 2026 alone, the market steps into a new growth band consistent with these multi-year dynamics.
Automotive Cabin Air Filter Market
Why this study matters for 2026 strategy
- Regulation is remapping product specifications. Stricter ambient air quality standards and vehicle-level requirements (notably recent updates in PM2.5 guidance and Euro 7 particle-size expectations) are elevating minimum filtration performance and redefining OEM acceptance criteria.
- Aftermarket and service execution have become strategic battlegrounds. Field incidents and safety recalls tied to cabin air filter replacement procedures have drawn regulator attention, making service protocols and installer training business imperatives.
- Technology differentiation is expanding beyond efficiency metrics into media chemistry and system integration—activated carbon and nanofiber media, electrostatic treatments, and multi-layer assemblies are now decisive in buyer choice for both OEMs and discerning aftermarket channels.
- Industry structure remains moderately concentrated: the top three firms control a meaningful portion of market value, while the top five push concentration past the majority threshold—an environment that favors targeted partnerships, selective vertical integration, and disciplined M&A.
What PW Consulting’s Automotive Cabin Air Filter Market report delivers
Designed as an operational playbook for executives, procurement leaders, and product strategists, the report synthesizes macro forecasting, competitive benchmarking, and implementation-ready recommendations without sacrificing technical rigor. Key deliverables include:
Automotive Cabin Air Filter Market
- Market sizing and a transparent forecasting model (2026–2032) with scenario analyses that stress-test demand under alternative regulatory timelines, vehicle parc evolution, and electrification scenarios.
- Demand-driver analytics linking air quality standards, vehicle design changes (HVAC architecture, cabin sealing), and end-user health priorities to filter adoption and premiumization potential.
- A competitive landscape and capability map covering OEM suppliers, filtration-media specialists, and aftermarket pure-plays—with capability scoring across media technology, OEM relationships, aftermarket reach, and geographic manufacturing footprint.
- Supply-chain and cost-to-serve profiles highlighting raw media supply concentration, key manufacturing bottlenecks, and levers to reduce lead times and inventory risk.
- Commercial playbooks for OEM engagement, aftermarket channel optimization (retailer, distributor, direct-to-consumer), and service-execution protocols aligned with recent safety guidance.
- M&A and partnership thesis with prioritized target archetypes and an integration checklist designed to protect margins while accelerating technological access.
- Implementation tools: pricing model templates, an OEM qualification tracker, sample technical specifications aligned to contemporary regulatory thresholds, and a prioritized test plan for product validation in fleet and consumer segments.
Dynamics and regulatory tailwinds
Since 2024–2025 the regulatory environment has become a primary demand driver. Updated national ambient air quality standards and vehicle-level emission/regulatory packages require finer filtration and enhanced removal of ultra-fine particles—this materially increases the value proposition for HEPA-grade media and advanced activated carbon formulations. Simultaneously, non-filtration regulations—such as a phased-out class of refrigerants and service-related safety bulletins—are indirectly reshaping cabin-filter requirements by changing HVAC architecture and by making service procedures risk-sensitive.
Automotive Cabin Air Filter Market
Regulatory scrutiny intensified following field incidents that prompted an engineering investigation and subsequent service bulletins focused on safe replacement procedures. These actions have two industry consequences: they raise the bar for replacement-service training and documentation, and they create short-term aftermarket demand for retrofit solutions and installer-safe product designs.
Competitive landscape — capability themes (not exhaustive)
The market comprises several global filtration and automotive-systems specialists with complementary strengths: sensor- and systems-oriented OEM suppliers, classic filtration media developers, and aftermarket brand owners. Representative firms include legacy filtration specialists, diversified automotive suppliers, and media innovators—all pursuing strategies including product premiumization, OEM specification capture, and aftermarket differentiation.
- Global OEM suppliers and tier-1 integrators continue to push specification-led adoption via system-level partnerships and co-development agreements.
- Filtration media specialists are monetizing proprietary media and converting material science advantages into ISO-validated product lines that command premium placement both in OEM fitment and aftermarket segments.
- Aftermarket incumbents and performance brands are cultivating loyal consumer niches via functionality (washable/performance filters), odor control partnerships, and subscription models for periodic replacement.
Market concentration metrics underscore the strategic calculus: the three largest players command a substantial share of value, while the top five together account for a clear majority—conditions that favor consolidation moves for firms seeking scale or rapid access to proprietary media technologies.
2026 strategic implications: actions that matter
- Product roadmap: Prioritize development tracks that meet projected particle-size capture requirements and combine particulate removal with gas/odor adsorption. Investing in validated nanofiber layers or activated-carbon composite media now mitigates rework risk as Euro-level and national standards tighten.
- Service and safety: Redesign replacement instructions and packaging to minimize field risk. Offer installer training packages and certified-fitment warranties—both lower liability exposure and create aftermarket differentiation.
- Commercial models: Test subscription and bundled service offerings with fleet operators and high-value consumer segments (e.g., ride-hailing, motorhome owners), leveraging recurring revenue to offset capital investments in advanced media production.
- Supply chain resilience: Secure multi-sourcing for critical media inputs and evaluate near-shoring options for filter assembly where logistics volatility threatens cost or lead time. Collaboration agreements with media specialists can provide protection against raw-material concentration shocks.
- M&A and partnerships: Pursue bolt-on acquisitions that close capability gaps (media chemistry, coated substrates, or advanced pleating machinery). Alternatively, structured joint ventures with media innovators can speed time-to-market while capping upfront capital exposure.
- Regulatory engagement: Embed compliance specialists early in product development and leverage pre-certification testing to accelerate OEM acceptance. Participation in standards bodies and engagement with regulators will yield early sightlines on incremental performance thresholds.
Operational experiments to prioritize in 2026
- Pilot a retailer-integrated installation program that includes certified training and a consumer-facing QR-code verification of correct installation to reduce recall risk and reinforce trust.
- Run a field validation across targeted fleet segments (e.g., commercial passenger transport, last-mile delivery) to quantify real-world benefits—air quality improvement, HVAC system energy impact, and perceived passenger comfort—feeding a commercial ROI case for premium filters.
- Test co-branded odor/chemical protection products (activated carbon + tailored fragrance or neutralizer) in markets with documented demand for VOC mitigation—position these as higher-margin aftermarket SKUs.
- Trial subscription pricing for high-frequency replacement cycles with telematics-enabled reminders to drive retention and data capture on usage patterns and filter life in diverse operating conditions.
Risk matrix and mitigations
- Regulatory flip-flops: Counter by building flexibility into media design and qualification workflows so products can be tuned to meet accelerated thresholds without full re-engineering.
- Service-related recalls and safety bulletins: Reduce exposure by embedding installer-proof features and by offering certified-installation channels; insure product directions with digital verification and training logs.
- Raw material concentration: Mitigate via strategic supplier partnerships, qualifying secondary suppliers, and maintaining safety stocks for critical media inputs.
- Competitive premiumization: Defend margins through IP protection, shortened product-development cycles, and targeted value propositions that connect filtration performance to quantifiable health and comfort outcomes.
What we intentionally withhold here — and why
In keeping with our "trailer" approach, this briefing presents the strategic shape of the opportunity while withholding the full set of segment-level splits, node-by-node regional allocations, and proprietary scoring matrices. These elements are core deliverables in the full PW Consulting report and are essential for executable business planning—if your 2026 decisions require granular market-by-region, by-application, and by-product-type allocation models, the complete dataset and our interactive forecasting tool will deliver them.
Next steps for leadership teams
For 2026, leaders must convert macro tailwinds into defensible, revenue-bearing actions. Prioritize regulatory-aligned product development, shore up service protocols to eliminate safety exposure, and pursue targeted commercial pilots that validate subscription and premium-filter economics. PW Consulting’s full market study provides the granular segmentation, valuation models, and playbooks required to operationalize these choices with confidence.
To access the complete forecast model, regional and application breakdowns, and our proprietary supplier/competitor matrices, contact PW Consulting to obtain the full Automotive Cabin Air Filter Market report and the accompanying implementation toolkit.
For detailed analysis of this topic, please visit the official page: Automotive Cabin Air Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Heating Element Market to Hit USD 2.49B by 2032 at 8.37% CAGR
By pmarketresearch, 2026-07-22
Flexible Heating Element Market: Strategic Intelligence for 2026 Decision-Makers
Executive preview
As companies align product roadmaps, supply chains, and M&A strategies for 2026, the flexible heating element market presents a rich mix of opportunity and complexity. Our new PW Consulting market study — anchored on a 2025 base year and tracking 2020–2025 history with forecasts through 2032 — synthesizes commercial, technical, and regulatory signals into decision-grade insight. The market has transitioned from niche engineering work to a mainstream thermal-management technology, expanding from under USD 1 billion in 2020 to roughly USD 1.42 billion in 2025, and is projected to continue growing to an estimated USD 2.49 billion by 2032 at a compound annual growth rate of 8.37%. This trajectory is driven by electrification, miniaturization in electronics, medical device proliferation, and rising reliability requirements for aerospace and automotive systems.
Flexible Heating Element Market
Why this study matters for 2026 planning
- Timing: 2026 is a critical inflection for procurement windows, supplier qualification cycles, and certification lead times. Decisions made in early 2026 determine product launches and qualification pipelines across 2027–2029.
- Risk mitigation: Material cost volatility and evolving certification standards (medical and space) mean that procurement and engineering trade-offs made now will materially affect unit economics and time-to-market.
- Competitive positioning: New entrants and contract manufacturers are compressing prototyping timelines and price points, while incumbent specialists double down on high-reliability and high-wattage niches. Understanding where to place bets between scale, customization, and certification is essential.
Market trajectory — a concise, data-driven snapshot
The flexible heating element market demonstrates steady, above-market growth across the 2020–2032 window. From approximately USD 0.95 billion in 2020 it expanded to about USD 1.42 billion by 2025. Our forecast shows continued momentum through 2032, culminating near USD 2.49 billion — representing an 8.37% CAGR over the forecast period. Growth is broad-based across end uses that require efficient, compact thermal control: battery thermal management, electronics and semiconductor manufacturing, medical devices, aerospace, and mobility systems. Importantly, the market’s growth profile masks important heterogeneity in margin structures, certification costs, and manufacturing complexity that materially affect strategic choices.
Flexible Heating Element Market
What the PW Consulting report delivers (practical content)
- Actionable market sizing and 12+ forecast scenarios — baseline, upside, downside, and technology-adoption curves — to stress-test revenue and capacity planning for 2026–2028.
- TAM/SAM/SOM frameworks tailored to buyer profiles (OEMs, EMS providers, and systems integrators), including rulebooks for segment prioritization without reliance on generic multipliers.
- Supplier scorecards and sourcing playbooks — engineering, quality, cost-to-serve, lead time, and certification readiness — with templates to run 30/60/90-day supplier audits.
- Design-to-cost and materials sensitivity models that quantify how shifts in polyimide, silicone, and carbon-based conductive trace costs translate to unit economics and margin erosion under different production mixes.
- M&A and partnership targets: a screened short-list of candidates by capability, certification status, IP, and geographic footprint, plus an integration checklist for thermal-technology bolt-ons.
- Regulatory and qualification roadmaps — from UL recognition and ESCC pathways to space and medical-class validation — with expected timelines and resource estimates for 2026 certification programs.
- Manufacturing architecture options — in-house versus contract manufacturing, nearshoring tradeoffs, and automation levers for medium-volume, high-mix production profiles.
Note: This preview omits granular segment and regional splits by design. The full report contains the detailed breakouts and unit economics that underlie the strategic recommendations summarized here.
Flexible Heating Element Market
Competitive landscape — who to watch and why
The market is populated by a mix of specialty players, broad thermal-systems firms, and fast-moving contract manufacturers. Tactical differentiation runs along three vectors: material and process expertise (polyimide/Kapton etching, silicone molding, etched-foil), certification and reliability pedigree (medical, aerospace/ESCC, UL), and speed/cost-to-prototype.
- Thermo Heating Elements, LLC (Piedmont, SC): A strong engineering partner for bespoke PTF, silicone, and polyimide solutions; excels in battery thermal-management projects and scalable production for low-to-high volumes. Strategic fit for OEMs requiring collaborative development and flexible ramp profiles.
- Epec Engineered Technologies (New Hampshire): Precision-focused, rapid-turn custom heaters with integrated sensing. Their low-MOQ and fast turnaround attract electronics and instrument customers that prioritize time-to-prototype.
- JLCPCB (China): A disruptive prototyping and low-cost production pathway. Their 2025 flexible-heater product line launch — no MOQ, free circuit design support, and rapid delivery — is reshaping expectations for early-stage product development, especially for EV, electronics, and medical prototypes.
- All Flex Solutions (Northfield, MN): Positioned in mission-critical and medical segments with high-reliability polyimide and silicone offerings. Their recent high-wattage polyimide heater announcement underscores a focus on high-performance medical applications.
- Zoppas Industries / IRCA (Italy) : Distinguished by space- and high-reliability qualifications. IRCA’s Pure-Polyimide Heater (PPH) work — including UL 94 V0 certification and ongoing ESA qualification — signals a premium positioning for aerospace and defense-grade systems.
- Minco, Watlow, Chromalox, Omega, Durex : Established thermal-systems vendors that combine heating elements with sensors, control electronics, and systems integration. Their strengths lie in end-to-end solutions for industrial, medical, and process-control customers.
Strategic implication: incumbents with certification and deep process control defend margin-rich niches. Newer entrants and contract manufacturers compress early-stage costs and force established suppliers to show faster prototypes and clearer value propositions.
Regulatory, material-cost, and certification dynamics shaping 2026 choices
- Certification is a gating factor. UL-recognized constructions and ESCC qualification are effectively mandatory for medical and space applications. Expect multimonth to multi-year lead times and non-trivial investment in testing and documentation for any player seeking to enter these segments.
- Material and process premiums are real and quantifiable. Polyimide-based heaters require precision etching and lamination that drive unit manufacturing costs meaningfully above rigid alternatives, while specialty carbon-based conductive traces add further raw material cost pressure. These differentials force engineering trade-offs between performance and price, particularly in high-volume mobility applications.
- Sustainability and energy-efficiency standards are rising. Regulatory emphasis on energy efficiency and safety is accelerating design changes — lower standby losses, improved thermal coupling, and redundancy architectures — that have implications for BOM cost and control-system complexity.
Strategic playbook for 2026 (prioritized actions)
- Short term (next 6–12 months) : Run supplier proof-of-concept projects with at least two different manufacturing models (specialist vs. high-volume CM). Start parallel qualification streams for any product requiring UL or ESCC recognition. Use prototyping partners to compress design cycles and validate manufacturability.
- Medium term (12–24 months) : Lock in supply agreements with indexed material-price clauses and multi-sourcing provisions for critical trace materials. Invest in targeted automation for cut–form–laminate processes to lower unit cost at scale. Prioritize certification funding for strategic product lines where premium pricing is available.
- Long term (24+ months) : Consider capability M&A to secure high-reliability process IP (e.g., pure-polyimide etching, high-wattage assemblies) or to onshore critical production for regulated markets. Build integrated thermal-management offerings (heater + sensor + control firmware) to capture higher system value and recurring revenues.
How to use this preview and where to go next
This article outlines the strategic contours and highlights the levers that will matter most for 2026 decision-making. It intentionally omits the granular regional and application splits, unit-cost tables, and company-level market shares that are essential when operationalizing a sourcing, product, or M&A plan. PW Consulting’s full Flexible Heating Element Market report contains those detailed breakdowns, downloadable models, supplier scorecards, and executable templates designed to shorten your path from insight to action.
For teams preparing 2026 budgets, product roadmaps, or sourcing strategies, the right next step is a focused workshop using the report’s scenario tools and supplier scorecards. Contact PW Consulting to schedule a briefing and obtain access to the full dataset and executable playbooks.
For detailed analysis of this topic, please visit the official page: Flexible Heating Element Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tyre Curing Press Market to Reach USD 344.8M by 2032 at 4.15% CAGR
By pmarketresearch, 2026-07-22
Tyre Curing Press Market: Strategic Intelligence for 2026 Decision-Making
As OEMs, tier‑1 suppliers, private equity investors and plant operations teams enter 2026, decisions made now about capital allocation, supplier selection and manufacturing modernization will determine competitiveness for the remainder of the decade. PW Consulting’s Tyre Curing Press Market study synthesizes historical movement (2020–2025) with forward-looking scenarios (2026–2032), offering a practical, action‑oriented view of where value will accrue — and where risk will concentrate — in the global curing press ecosystem.
Tyre Curing Press Market
Why this study matters in 2026
-
A maturing, yet growing market: After steady expansion from USD 163.15 Million in 2020 to USD 215.0 Million in 2025, the market is forecast to continue its upward trajectory, approaching USD 344.8 Million by 2032. Our modeled central case shows a compound annual growth rate of roughly 4.15% for the forecast window 2026–2032, illustrating both predictable base demand and pockets of higher‑velocity investment.
Tyre Curing Press Market -
Fragmentation creates opportunity: The curing press market remains relatively fragmented (CR3 approximately 24.6%; CR5 approximately 26.2%), which means procurement teams can still extract value through disciplined sourcing, specification harmonization and selective consolidation — but only if they act with data and a clear supplier playbook.
Tyre Curing Press Market -
Operational leverage drives ROI: With energy cost pressure, environmental permitting and stricter compliance requirements emerging in multiple jurisdictions, choices about press technology (hydraulic vs. mechanical vs. electric/hybrid), automation and lifecycle maintenance now have outsized impact on unit economics and time‑to‑market.
Strategic implications for capital planners and operations leaders
-
Prioritize retrofit readiness and modularity. Plants that adopt modular curing platforms and retrofit paths can decouple capacity expansion from full line replacement, reducing capital intensity and shortening deployment lead times. The right modular strategy reduces execution risk in regions where regulatory review or permitting timelines are uncertain.
-
Embed energy and emissions KPIs into capex decisions. New machine architectures with lower energy draw or improved process control are rapidly changing lifecycle cost dynamics. Even modest efficiency gains compound over multi‑decade equipment lifespans, affecting TCO and payback calculations.
-
Design for traceability and regulatory resilience. Recent certification and compliance friction in some markets underscores the need for audit‑grade machine identification and process traceability. Buyers should require digital logging of curing press IDs and process parameters as a mandatory element of any procurement contract.
-
Use supplier concentration insights as a negotiating lever. With the market remaining fragmented, buyers can engineer multi‑vendor strategies that combine best‑of‑breed technology (e.g., electric eCuring modules) with low‑cost frames or local service partnerships to optimize both price and regional aftermarket coverage.
What the report delivers — operational, boardroom and investment intelligence
-
Integrated market sizing and scenario models. We provide audited historicals (2020–2025) and three scenario trajectories (base/accelerated/slow) for 2026–2032, enabling boardrooms to stress test capital budgets against demand, energy and regulatory shocks.
-
Actionable procurement playbooks. Sample RFP specifications, evaluation matrices and a supplier scorecard tailored for tyre curing press purchases help procurement teams reduce selection time and align OPEX/TCO expectations with technical performance.
-
Engineering and retrofit checklists. Plant engineers receive a validated checklist for civil, electrical and process integration, plus a phased retrofit roadmap that minimizes downtime and aligns with production ramp schedules.
-
Financial tools and TCO calculators. Embedded models let users estimate lifecycle costs under varying utilization, energy price and maintenance regimes — with sensitivity knobs for different machine architectures and automation levels.
-
Regulatory and compliance compendium. A practitioner’s guide to key permitting, safety and labeling considerations — highlighting recent developments that materially affect procurement and certification timelines.
-
Supplier profiles and competitive heatmaps. Confidential benchmarking of incumbent and emerging suppliers covering technology attributes, service footprint, innovation posture and go‑to‑market strategy.
Competitive landscape — what the leading vendors signal for buyers
The curing press vendor ecosystem is diverse: established European engineering houses, specialist regional manufacturers, and agile suppliers from cost‑competitive geographies. Each archetype implies different risk/return tradeoffs for buyers.
-
HF GROUP (Hamburg, Germany) — sophistication in modular solutions. HF GROUP’s modular hydraulic and electric eCuring platforms (including dedicated product lines for PCR/TBR and MCP variants) signal an emphasis on flexible, upgradeable systems. Their global footprint — evidenced by thousands of delivered units and active trade show participation through 2026 — makes them a go‑to partner for multinational OEMs seeking standardized platforms and centralized support.
-
Uzer Makina (Kartepe, Turkey) — specialized hydraulic competence. With a focus on floating column hydraulic presses and a portfolio that spans frame and mechanical presses, Uzer targets customers requiring robust hydraulic performance across a spectrum of tyre formats. Their 2023 acquisition moves indicate a deliberate scale and capability expansion in hydraulics — relevant for buyers prioritizing proven mechanical durability.
-
Larsen & Toubro Limited (Mumbai, India) — breadth for emerging markets. L&T’s mechanical cure press range addresses a broad set of vehicle classes typical in high‑volume emerging markets; buyers in these geographies value localized engineering, rapid service response and economical lifecycle costs.
-
HERBERT Maschinenbau (Germany) — energy optimization. HERBERT’s EcoCure series and other energy‑efficient offerings represent the innovation vector toward lower‑consumption presses and tighter process control. For operations where energy and emissions are a gating consideration, HERBERT’s platform archetype is increasingly attractive.
-
SCPT Machinery (China) — cost competitiveness and volume supply. Chinese suppliers remain influential for price‑sensitive expansions and for customers willing to trade premium service for lower upfront cost. Robust selection and contract terms are essential to mitigate aftermarket and warranty risks.
-
Cima Impianti (Italy) — automation and retreading orientation. The Ecoline automatic press range and retreading‑focused solutions reflect a niche where automated throughput and mold compatibility enable new service‑led revenue streams, particularly in retreading and specialty tyre lines.
-
ŽĎAS (Czech Republic) — heavy‑duty and OTR specialization. With a focus on truck, tractor and building machinery tyre production, ŽĎAS’s offerings matter to manufacturers where size, robustness and custom molds drive procurement logic.
Recent industry signals and regulatory noise — how they change the playbook
-
Compliance friction is real: A recent denial of a tire certification petition due to labeling that included curing press identification issues underscores the downstream impact of press selection and process documentation on product homologation. Companies must ensure curing press traceability and integrate press IDs into tire information systems to avoid certification delays.
-
Permitting and environmental review are active. Local permitting decisions now routinely include new presses under air and emissions frameworks; case permits filed in 2025–26 demonstrate that environmental timelines and permit conditions can shape deployment calendars and operating envelopes.
-
Product launches and trade engagement indicate innovation cadence. Suppliers are actively showcasing energy‑efficient, automated and digitally instrumented press solutions at global events in 2025–26 — a clear signal that buyers who delay risk being offered retrofit‑only options at higher cost and longer lead times.
How to use the report to inform near‑term (2026) decisions
-
Short list suppliers using our scoring matrix and then run live TCO scenarios with three utilization cases. This yields a defensible recommendation for capex approval cycles.
-
Define an 18–36 month retrofit pipeline prioritizing modular, energy‑efficient presses in plants with the highest energy intensity or closest regulatory scrutiny.
-
Negotiate support contracts with clear SLAs for instrument calibration, spare parts availability and press ID traceability — clauses that directly mitigate certification and warranty risks.
-
Embed monitoring and digital logging at procurement to create a single source of truth for product certification and process validation across plants.
Closing — the strategic choice ahead
The tyre curing press market is not a legacy, static market — it is being reshaped by energy constraints, regulatory vigilance and rapid product innovation. The next 12–18 months are pivotal: choices made in 2026 about technology architecture, supplier partnerships and data integration will materially influence manufacturing cost curves and time to market through 2032.
PW Consulting’s full Tyre Curing Press Market study provides the granular segment models, supplier scorecards, contract playbooks and TCO tools necessary to convert these insights into executable boardroom actions. For decision makers who need the numbers, the models and the step‑by‑step procurement playbook to move confidently in 2026, our full dataset and downloadable tools are available on the report page.
For detailed analysis of this topic, please visit the official page: Tyre Curing Press Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vacuum Evaporation Boat Market to Reach USD 344.8 Million by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-22
Vacuum Evaporation Boat Market — Strategic Outlook for 2026 Decision-Makers
As companies prepare strategic roadmaps for 2026 and beyond, the Vacuum Evaporation Boat market has moved from a niche industrial input to a predictable, investment-grade market segment. PW Consulting’s latest study — built on a 2025 base year with a historical window from 2020–2025 and a forecast horizon through 2032 — quantifies that maturation and translates it into actionable guidance. Between 2020 and 2025 the market expanded noticeably, and our modeling projects continued growth across the forecast period at a compound annual growth rate of 6.98% (2026–2032), with the market trajectory taking it from the mid‑hundreds of millions in 2025 to a substantially larger scale by 2032. For executives weighing capital deployment, supplier selection, or M&A strategies in 2026, the implications are immediate: predictable expansion combined with evolving technology and regulatory pressure creates windows for premium positioning, supply-chain consolidation, and selective differentiation.
Vacuum Evaporation Boat Market
Why this study matters for 2026 strategic choices
- Evidence-based confidence for budgeting. The report provides a structured demand outlook and scenario-based sensitivity analyses that convert top-line growth assumptions into capacity planning and OPEX/CAPEX schedules appropriate for 2026 budget cycles.
- Technology-led differentiation. Advances in evaporation source design, refractory materials and ceramic composites are creating tiered supplier economics. Our benchmarking highlights where higher initial costs translate to lower lifecycle replacement and contamination risk — critical inputs for procurement and engineering trade-offs.
- Regulatory and sustainability as a commercial variable. Recent certifications and funded R&D initiatives across key suppliers are shifting procurement criteria from purely technical to environmental-performance‑inclusive. Procurement playbooks in the report show how to incorporate CO₂e footprint and supplier R&D roadmaps into vendor scorecards.
- Speed to market matters. With demand growth solid, first-mover advantage in validated, higher‑yield boats or co-developed OEM solutions can yield outsized returns. Our go‑to‑market templates translate market timing and production lead times into prioritized actions for 2026.
Market dynamics distilled for decision-makers
The recent market evolution is being driven by precision thin-film processes in electronic components, expanding metalizing and coating applications, and evolving material needs related to energy and battery technologies. Supply-side dynamics are shaped by specialized manufacturers of refractory metals and engineered ceramics, the availability of high‑quality graphite and tungsten inputs, and a modest degree of fragmentation among suppliers — creating opportunities for both strategic partnerships and bolt-on acquisitions.
Vacuum Evaporation Boat Market
Regulation and sustainability initiatives are no longer peripheral. Notably, leading material suppliers have begun publicly aligning product and manufacturing footprints with carbon accounting standards and national R&D priorities. These developments have practical procurement implications: certification and government-backed R&D programs influence long‑list → short‑list conversion rates for OEMs sensitive to lifecycle emissions and supply security.
Vacuum Evaporation Boat Market
What the PW Consulting report delivers (practical, operational content)
- Executive summary with 2025 base-year validation and downside/central/upside scenarios for 2026–2032.
- Granular demand-side drivers and use-case mapping (technology maturity, unit-replacement cycles, throughput impact on boat choice).
- Supply-chain maps for key raw materials, single‑source risk indicators, and lead‑time stress testing under multiple demand shocks.
- Product benchmarking and failure-mode analysis comparing metal‑based, ceramic‑based and hybrid designs (qualitative and technical trade-offs are provided; sensitive segmentation tables are reserved for the full report).
- Commercial models: vendor scorecards, pricing elasticity models, and go‑to‑market templates for OEMs and component suppliers.
- M&A and partnership playbook with screening criteria, valuation heuristics and integration pitfalls specific to evaporation-source businesses.
- Regulatory and ESG overlay that translates certifications, government R&D funding and lifecycle accounting into procurement policy adjustments.
- Downloadable datasets and dashboards (time-series market sizing, demand drivers, supplier database) designed for immediate integration into corporate planning tools.
Competitive landscape — positioning and strategy implications
The vendor map in this segment is characterized by specialized engineering suppliers, diversified materials conglomerates, and boutique fabricators that service specific thin‑film and coating needs. Our competitive chapter profiles leading players and surfaces their strategic postures, operational strengths and potential vulnerabilities.
- Plansee SE (Reutte, Austria — https://www.plansee.com) : A specialist in refractory-metal solutions, Plansee occupies a premium quality niche when thermal stability and material purity are decisive. For buyers, Plansee represents a supplier that can be tiered for high‑specification, low‑volume applications. Strategic takeaway: use Plansee for high‑margin, technically differentiated product lines and consider co‑development for advanced alloys.
- H.C. Starck Solutions (Goslar, Germany — https://www.hcstarcksolutions.com) : With core capabilities in tungsten and powder metallurgy, H.C. Starck is advancing sustainability and extraction‑process innovation. Publicly reported certifications and a government‑backed R&D program emphasize their intent to lead on environmentally friendly sourcing for battery and energy applications. Strategic takeaway: monitor their sustainability roadmap — qualification of their materials can become a procurement gating factor in Europe.
- 3M (St. Paul, Minnesota, United States — https://www.3m.com) : A diversified materials company with global scale and applied‑materials expertise. 3M’s strength is in systems integration and multi‑industry channel reach, making it attractive for OEMs seeking consolidated supply and warranty terms. Strategic takeaway: leverage 3M for volume and integrated warranties, but expect premium pricing where systems engineering is included.
- Kurt J. Lesker Company (Clairton, Pennsylvania, United States — https://www.lesker.com) : Recognized in industry‑level supplier lists for evaporation sources, Kurt J. Lesker combines equipment breadth with aftermarket support. Strategic takeaway: useful partner for customers needing validated equipment ecosystems, spare parts and technical service agreements.
- R.D. Mathis Company (Long Beach, California, United States — https://rdmathis.com) : A focused U.S. supplier with a refreshed commercial catalog (released February 2025) that expanded its lineup of evaporation sources for thin-film coating and metalizing. Strategic takeaway: attractive for U.S.-based manufacturers seeking faster lead times and customizable solutions; the expanded catalog signals readiness to compete beyond legacy accounts.
Recent developments and industry signals to watch in 2026
- Supplier-level sustainability credentials are becoming a procurement filter: public CO₂e footprint certifications and government-funded R&D (notably programs targeting cleaner raw material extraction) are accelerating supplier requalification timelines.
- Catalogue and product-line refreshes by specialist suppliers indicate both incremental product innovation and an intent to broaden served markets — firms with refreshed portfolios are often signaling readiness to compete for higher-volume contracts.
- Technical publications and sector analyses are consolidating lists of qualified evaporation-source suppliers; inclusion in these lists materially shortens sales cycles for vendors and alters RFP dynamics for buyers.
Strategic recommendations for 2026
- Integrate lifecycle environmental metrics into vendor selection matrices now. Certification and funded R&D trajectories will rapidly become differentiators in many procurement processes.
- Pursue a layered supplier strategy: retain premium specialists for critical, high‑value lines while qualifying agile local suppliers to de‑risk lead times and single‑source exposure.
- Prioritize modular contracts that allow capacity scaling. With predictable CAGR growth, flexible supply agreements that include volume tiers and co‑development clauses preserve upside while limiting fixed capital overhang.
- Use the forthcoming 2026 budget cycle to fund pilot co‑development projects with suppliers who demonstrate complementary IP and environmental roadmaps — these pilots are the shortest path to product differentiation.
- For PE and corporate development teams: screen bolt‑on targets where process knowledge and established customer relationships can be integrated into a larger materials or equipment play.
Next steps — what you get in the full report
PW Consulting’s full report delivers the quantitative tables, regional and application breakouts, supplier-level financial and operational indicators, and downloadable models that corporate strategy, procurement and M&A teams need to execute in 2026. The executive synopsis above is designed as a strategic trailer: it highlights the paths to value without disclosing proprietary segmentation tables and line-item forecasts that are included with the full dataset.
If your 2026 planning requires validated market sizing, supplier intelligence, or a tailored scenario run using our base-case and stress assumptions, the full report and the accompanying data pack provide the operational detail and model transparency to convert market conviction into commercial action.
For detailed analysis of this topic, please visit the official page: Vacuum Evaporation Boat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fuel Cell Electric Vehicles Market: Strategic Outlook for 2026 Decision-Makers
As organizations prepare budgets, strategic roadmaps, and investment theses for 2026, the Fuel Cell Electric Vehicles (FCEV) market presents both a high-growth opportunity and a complex execution environment. PW Consulting’s latest market research—anchored on a 2025 base year and projecting through 2032—captures the commercial inflection that industry participants must understand before making consequential commitments. At the macro level the market is expanding at a compound annual growth rate (CAGR) of 26.6% between the historical window and our forecast horizon, rising from early commercial volumes in the 2020s to a materially larger opportunity by the early 2030s. This briefing distills the strategic value of the full report for 2026 decisions while deliberately reserving granular segmentation tables to encourage direct consultation of the source research.
Fuel Cell Electric Vehicles Market
Why this report matters for 2026
- Timing: 2026 is a pivotal year for converting pilots into scaled deployments. The market’s growth trajectory signals accelerated demand that favors organizations with ready-to-scale supply chains and station access.
- Capital allocation: With a sustained high-growth projection through 2032, capital should be allocated with a view to multi-year product cycles, infrastructure co-investment, and staged exposure to hydrogen production and distribution economics.
- Partnership and ecosystem design: The opportunity is ecosystem-driven. OEMs, system integrators, station operators, and industrial gas suppliers must align commercial incentives to overcome deployment bottlenecks.
- Policy sensitivity: Regulatory and incentive shifts can materially re-rate project economics in short order. Active policy engagement and scenario-driven contingency plans are essential.
What the full report provides (practical, transaction-ready content)
- Executive synthesis and rapid-read decision guidance tailored for board-level and investment committees.
- Transparent market-sizing methodology with historical reconstructions (2020–2025) and detailed forecasts (2026–2032), including unit and revenue projections at the market level.
- Demand-driver diagnostics—technology desirability, total cost of ownership (TCO) modeling, and route-to-market economics for passenger, commercial, and fleet use cases.
- Segment and channel overviews, with actionable go-to-market playbooks for OEMs, suppliers, and infrastructure developers.
- Supply-chain maps and component-level exposure analysis (membranes, catalysts, balance-of-plant), including supplier risk heatmaps and lead-time scenarios.
- Competitive benchmarking with strategic profiles for incumbent and emerging players, and decision trees for partnering, licensing, and M&A.
- Policy, regulation, and incentives matrix cross-referenced by jurisdictional risk and opportunity.
- Investment case templates, sensitivity tables, and scenario models that support valuation and capex planning.
- Appendices with data tables and source references—note: detailed regional and application-level splits are included in the full dataset accessible via the report landing page.
Data-driven market context
Our market reconstruction shows that FCEV commercialization has moved beyond isolated pilots into nascent scaling. On a revenue basis the market exhibits a steep growth curve into the forecast window—driven by commercial use cases that require long range and rapid refueling, and by policy-driven decarbonization of hard-to-electrify segments. The industry’s projected CAGR of 26.6% reflects both increasing vehicle introductions and accelerated hydrogen infrastructure investments that will reduce logistical barriers to adoption.
Fuel Cell Electric Vehicles Market
Despite this momentum, deployment dynamics are uneven. Public agency reporting from major early-adopter regions highlights both progress and friction. For example, a recent regulatory evaluation noted a measured decline in registered FCEVs in a leading submarket during 2025 and underscored the need for an expanded hydrogen station network to sustain growth trajectories into the latter half of the decade. These mixed signals create windows for opportunistic investments but also mandate conservative staging in capex plans.
Fuel Cell Electric Vehicles Market
Strategic implications for 2026 planning
- Investors: Prioritize staged exposure via hybrid instruments (convertibles, staged equity) and early-offtake agreements. The market concentration metrics suggest top-tier incumbents hold meaningful share but leave room for specialized entrants and vertical integrators.
- OEMs: Consider platform strategies that allow multiple powertrain variants to share the same architecture—this preserves optionality while enabling faster production ramp once hydrogen stations proliferate.
- Suppliers: Secure long-lead raw materials and diversify component sourcing. Suppliers that can demonstrate reliability and scale-up pathways for key stack components will command superior margins.
- Infrastructure developers and hydrogen producers: Adopt hub-and-spoke deployment that prioritizes corridor economics and fleet anchor customers. Leverage public–private funding models to de-risk early station rollouts.
- Fleets and operators: Use leasing and fuel-as-a-service contracts to hedge technology and fuel-price risk. Early deployment case studies show leasing reduces adoption friction and accelerates utilization.
- Policymakers and regulators: Design incentives that address both vehicle cost and infrastructure density; insufficient station coverage remains a primary constraint on rapid scale-up.
Competitive landscape — what the data tells executives
The market is characterized by a mix of established OEM leaders and technology specialists. At the headline level, the top three companies account for a material share of market activity while the top five capture a modestly larger portion—indicating a market that is neither fully consolidated nor atomized, and one where strategic alliances can meaningfully shift positioning.
- Toyota Motor Corporation (Toyota City, Japan) — The Mirai program has delivered early commercial learning on passenger FCEVs and continues to be a strategic reference point for hydrogen passenger mobility. Toyota’s approach emphasizes systems integration and long-cycle product development, making it a benchmark for durability and OEM-level hydrogen commitment. (See the Mirai program)
- Hyundai Motor Company (Seoul, South Korea) — With product families that span passenger cars and heavy-duty trucks, Hyundai’s investments in both vehicle lines and commercial partnerships reflect a bet on heavy and medium-duty deployments as early scale drivers. Recent product debuts underscore Hyundai’s intent to maintain technological leadership in stack integration and vehicle packaging. (See Hyundai Xcient and NEXO)
- Honda Motor Co., Ltd. (Tokyo, Japan) — Honda’s market entry strategies include leasing in select markets and supplying modular fuel cell systems for commercial applications. Leasing pilots in North America demonstrate how flexible ownership models can accelerate initial uptake in regulated, incentive-led markets. (See Honda CR-V e:FCEV)
- BMW Group (Munich, Germany) — BMW’s roadmap targets series production models toward the latter half of the decade, positioning the company as a premium-segment contender that prioritizes integration with existing vehicle lines and brand propositions. (See BMW’s fuel-cell initiatives)
Each of these players brings distinct advantages—scale, product breadth, or niche technical expertise—and the full report analyzes their product roadmaps, supply-chain control, and partnership strategies in actionable detail. Recent events—ranging from product launches and leasing programs to policy seminars—are synthesized to show how competitive intent translates into deployment outcomes.
Risks, scenarios, and contingency planning
Our scenario framework models three high-level paths over the 2026–2032 horizon: a base case aligned with the 26.6% CAGR, an accelerated case driven by stronger-than-expected policy support and station rollouts, and a constrained case where infrastructure lag and higher hydrogen prices slow adoption. Key sensitivities in all scenarios include hydrogen feedstock pricing, station throughput (utilization), and relative TCO versus battery-electric alternatives. The report supplies sensitivity matrices and break-even heatmaps to support negotiation of supply contracts, incentive bids, and fleet procurement.
How to use this research in 2026 decision cycles
- Incorporate our scenario outputs into capital allocation models—use the provided sensitivity tables to stress-test investment returns under different hydrogen price curves and station density assumptions.
- Prioritize pilots that co-locate fleets with planned station infrastructure to minimize refueling risk and accelerate utilization thresholds that unlock station economics.
- Adopt partnership-first strategies where manufacturing, fuel supply, and station operations are shared—this reduces single-party capex burden and improves go-to-market speed.
- Leverage the report’s transaction-ready templates for offtake agreements, JV term sheets, and public funding proposals to accelerate approvals and de-risk execution.
Next steps
For executives preparing 2026 strategies, the full PW Consulting report is designed as a working tool: it includes the complete dataset, regional and application-level segmentations, and downloadable financial models that translate forecasts into project-level cash-flow scenarios. The high-level market trajectory, concentration metrics, and competitive positioning summarized here will be most effective when combined with the report’s granular segmentation and scenario tables, which are accessible from the report landing page.
PW Consulting’s FCEV market study is built to inform boardroom decisions, investment committees, and operational planning teams confronting the near-term challenges and long-term upside of hydrogen mobility. For those preparing to act in 2026, the report offers the empirical foundation and executable frameworks necessary to convert strategic intent into measurable results.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dental Market 2026: A Strategic Preview — Why this PW Consulting Report Will Shape Your Next Move
Introduction
As the dental market accelerates into the second half of the decade, boards, corporate strategy teams, and PE sponsors face a compressed decision window. PW Consulting’s new Dental Market study — grounded in a seven-year historical baseline and a multi‑scenario forecast through 2032 — converts raw market momentum into executable choices for 2026. The market’s compound annual growth rate (CAGR) through the forecast horizon is 9.25%, reflecting a sustained structural expansion driven by demographic demand, technology adoption and shifting provider economics. Between the pre‑pandemic era and the report’s base year (2025) the industry moved from a mid‑twenty billion-dollar market to a mid‑thirty billion‑dollar baseline, with projections that more than double that footprint by the early 2030s under the central scenario. This preview explains why that growth matters for strategy, what we cover in the full study, and how to prioritize choices when timing and capital are constrained.
Dental Market
Why the 2026 Horizon Matters
- Capital allocation decisions must be timely. With market expansion accelerating into the late 2020s, 2026 is a hinge year for allocating capex to digital platforms, consumables automation and implant/digital workflows. Delaying investments risks losing share to incumbents who can scale faster across growing channels.
- Commercial models are in flux. The interplay between distributors, DSOs, and independent practices is reshaping go‑to‑market economics. Strategic choices made in 2026 — around distributor partnerships, e‑commerce, and bundled service offerings — will determine mid‑cycle margins.
- Regulatory and reimbursement headwinds are asymmetric. Recent guidance and reimbursement trends are stable but not inflation‑linked; manufacturers that redesign pricing and service packages now will protect unit economics into 2027 and beyond.
What We Mean by “Actionable” — Report Contents (high level)
The full report is structured to move leaders from insight to action. It does not merely present a forecast; it provides operational tools you can apply in the next 90–270 days. Key modules include:
Dental Market
- Market sizing and validated forecasting methodology (historical 2020–2025 baseline; forecast scenarios to 2032) — transparent assumptions and sensitivity bounds tied to adoption, pricing, and reimbursement inputs.
- Demand‑driver deep dives — aging demographics, elective esthetic demand, preventive care expansion, and digital orthodontics adoption curves, mapped to revenue levers and unit economics.
- Commercial playbooks — distributor negotiations, DSO/Group practice engagement models, direct‑to‑practice e‑commerce strategies, and subscription/service overlays that improve stickiness.
- Competition and M&A playbook — target screening criteria, buy/build vs partner matrices, integration risk checklists and valuation multipliers by business model.
- Operational stress tests — supply‑chain shock scenarios, raw‑material inflation passthrough models, manufacturing lead‑time optimization and alternative sourcing strategies.
- Regulatory & reimbursement tracker — a pragmatic checklist to prioritize market entries and product launches by jurisdictional risk and reimbursement sensitivity.
- Financial toolkits — pricing elasticity matrices, margin improvement templates, and three investor‑grade valuation case studies to support capital requests.
Note: the report intentionally withholds granular regional and application splits in this public preview. That level of granularity — which materially affects GTM and M&A decisions — is available in the full study and accompanying data pack.
Dental Market
Market Structure and Competitive Dynamics
The dental market is large and consolidating, but remains open to disruptive entrants. Top firms collectively account for a meaningful share of global revenue, leaving room for well‑positioned challengers and specialized niche players. Our concentration analysis shows a market where the top three firms capture a plurality but not a dominating majority, and the top five widen that lead modestly — a structure that rewards scale while still permitting targeted entrants to win on specialization and channel control.
Company Positioning — Strategic Takeaways
- Dentsply Sirona: A broad portfolio owner with strength in equipment and implant systems. Their scale and channel reach make them a natural consolidator of workflow solutions; competitors must either partner or compete on highly differentiated digital services.
- Straumann Group: A premium implant and prosthetics leader with strong margin dynamics. Straumann’s strategy centers on vertical integration of implant systems, regenerative products and lab partnerships — a model that works best where clinicians can justify higher upfront spend.
- Align Technology: The clearest beneficiary of digital orthodontics trends. Its platform plays (clear aligners, scan‑to‑manufacture workflows) create recurring revenue and data assets; rivals should evaluate ecosystem strategies rather than one‑off product battles.
- Ivoclar Vivadent & GC Corporation: Specialists in materials and restorative solutions. Their wins depend on product innovation that lowers chair time or improves clinical outcomes; price‑value calculus is central when practices face reimbursement pressure.
- Coltene, Kerr, Parkell and other consumables innovators: Fast product cycles and point‑of‑care improvements allow nimble firms to capture share from incumbents that are slower to iterate.
- 3M Oral Care: A diversified industrial player that leverages R&D intensity in preventive and restorative categories; strategic play includes bundling materials with diagnostic tools.
- Distributors (Henry Schein, Patterson, Benco): Distribution remains a strategic choke point. Firms that secure preferred distributor economics, or which can disintermediate through superior e‑commerce experiences, will capture outsized gains.
Recent Product and Market Signals (What to Watch)
- Multiple firms launched next‑generation consumables and dental devices during 2025, signaling continued clinical innovation at the product level and compressed time‑to‑market for point‑of‑care tools.
- Manufacturers are increasingly using digital channels — including e‑commerce implant selection guides and online ordering — to shorten procurement cycles and gather practice usage data.
- Distributor and supplier ethics codes and revised trade guidance in 2025 are tightening commercial behaviors; compliance‑aware firms are adjusting contract terms and sales incentives accordingly.
Market Dynamics and Near‑Term Risks
Four dynamics will shape near‑term execution and valuations:
- Reimbursement pressure: Provider rates are broadly stable but have not kept pace with inflation and rising practice overhead. This compresses margins at the practice level and increases price sensitivity for devices and services that require higher upfront capital or consumable spend.
- Raw material and supply volatility: Input prices rose in 2025, and many manufacturers are experiencing higher component costs and longer lead times. Firms with flexible sourcing and localized manufacturing will be advantaged.
- Regulatory clarity: Updated codes of ethics and regional compliance guidance are changing commercial interaction models between manufacturers, distributors and clinicians. This creates short‑term friction but longer‑term transparency benefits for companies that move early.
- Labor and practice economics: Employment dynamics in dental offices are recovering but remain volatile. Headcount and wage pressures influence adoption rates for labor‑saving technologies and subscription service models.
Strategic Imperatives — How Executives Should Respond in 2026
- Prioritize products that reduce chair time and drive recurring consumable revenue. The intercept between time‑savings and recurring consumables creates the most defensible revenue streams.
- Build distributor resilience and digital channels in parallel. Strengthen distributor partnerships while piloting direct digital offerings in select markets to capture learning without destabilizing channel relations.
- Use scenario planning tied to reimbursement and supply shocks. Stress test pricing and adoption assumptions for 2026 launches under conservative reimbursement scenarios and a range of input‑cost shocks.
- Target M&A for workflow consolidation, not just product lines. The most valuable targets are those that fill gaps in practice workflows — digital scanning, lab integration, or DSO enablement — rather than narrow component plays.
- Operationalize compliance and ethics early. Firms that align commercial incentives to updated codes of conduct will reduce transaction costs and insurance risks when scaling internationally.
How PW Consulting’s Report Helps You Execute
This study is built for practitioners: scenario‑driven forecasts, a competitive playbook with vendor performance indicators, M&A scoring templates, and operational checklists that you can deploy with minimal customization. The report’s data pack contains the granular regional and application splits, price elasticities and channel economics that underpin 2026 go‑to‑market and M&A decisions — information we deliberately exclude from this public preview to protect commercial sensitivity and to drive a single source of truth for strategic projects.
Conclusion — A Call to Action for 2026
The dental market’s trajectory presents both scale and complexity. Growth is robust, but it favors organizations that align capital, commercial design and operational resilience now. PW Consulting’s Dental Market study is designed to translate the headline CAGR and market momentum into pragmatic moves: what to build, who to buy, when to partner, and how to price for a world where reimbursement and input costs are increasingly dynamic. For leaders preparing 2026 budgets and M&A pipelines, the earliest actionable advantage will come from integrating forecast scenarios with execution playbooks — precisely what this report delivers.
To access the full dataset, regional and application splits, and the implementation templates referenced in this preview, please consult the complete PW Consulting report and data pack.
For detailed analysis of this topic, please visit the official page: Dental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting forecasts 5.85% CAGR for the Commercial Vehicle Power Steering Pump market through 2032
By pmarketresearch, 2026-07-17
Commercial Vehicle Power Steering Pump Market: Strategic Imperatives for 2026
Executive summary
PW Consulting’s newly released Commercial Vehicle Power Steering Pump Market report (base year 2025; historical window 2020–2025; forecast 2026–2032) provides a practitioner-focused roadmap for executives making capital allocation, product-development, and supply-chain decisions in 2026. The market shows a steady compound annual growth rate (CAGR) of 5.85%, and our topline modelling places the global market firmly on an upward trajectory from the mid‑2020s into the early 2030s (all revenue figures reported in USD Million). This briefing highlights the report’s strategic value, key competitive dynamics, risk vectors, and the concrete decision levers executives should prioritize this year.
Commercial Vehicle Power Steering Pump Market
Why this report matters for 2026 decision cycles
- Timing: 2026 is the inflection point for fleets and OEMs managing simultaneous mandates—tightening CO2 targets, advancing electrified powertrain adoption, and scaling ADAS features. Our analysis converts these macro drivers into program-level impacts for steering pump architectures.
- Clarity: We quantify an observed recovery from pandemic and supply-chain disruptions across 2020–2025 and translate that trajectory into a seven-year forecast horizon (2026–2032). The report isolates where incremental revenue will originate, which technologies will capture share, and which procurement levers matter most to margins.
- Actionability: Unlike high-level market summaries, this deliverable provides templates and playbooks—e.g., total-cost-of-ownership (TCO) models for hydraulic vs electro‑hydraulic platforms, supplier qualification checklists, and retrofit vs OEM integration decision matrices—designed for deployment in 2026 budgeting cycles.
Market trajectory: what the headline numbers tell you
Between 2020 and 2025 the industry experienced cyclical variation as OEM production normalized and technology adoption accelerated. Our aggregate market sizing shows recovery and momentum into 2026, followed by compound expansion through 2032 at a modeled CAGR of 5.85%. These topline dynamics reflect three simultaneous forces: (1) continued demand for traditional hydraulic solutions in legacy fleets; (2) incremental conversion toward electro‑hydraulic and electrically-driven pumps driven by fuel-efficiency and emission rules; and (3) ADAS-driven feature creep that raises the performance floor for steering systems.
Commercial Vehicle Power Steering Pump Market
Report contents — practical, implementation-oriented modules
The report is structured to support decision-making at three levels: corporate strategy, product & engineering, and procurement & operations. Key deliverables include:
Commercial Vehicle Power Steering Pump Market
- Market sizing & scenario modelling: Baseline and sensitivity scenarios through 2032, with demand curves stress-tested against commodity volatility and regulatory shocks.
- Technology roadmap & adoption curves: Comparative analysis of hydraulic, electro‑hydraulic, and electric pump architectures, including maturity timelines for power‑on‑demand and ADAS-capable modules.
- Unit economics & TCO models: Manufacturer and fleet-level TCO worksheets that capture fuel, maintenance, warranty exposure, and residual-value effects for steering-pump choices.
- Competitive benchmarking toolkit: Scorecards for supplier selection covering performance, reliability, integration risk, and roadmap alignment for medium- and heavy-duty platforms.
- Supply‑chain risk heat map: Supplier concentration, nearshoring vs offshoring options, lead‑time buffers, and strategies to hedge aluminum/steel price fluctuation impacts.
- Regulatory impact playbooks: Compliance pathways for evolving emissions mandates and inspection regimes (e.g., leak-free certification requirements), with recommended engineering and procurement responses.
- M&A & partnership trigger matrix: Investment thresholds and partner profiles for bolt-on acquisitions, joint development agreements, and strategic sourcing collaborations.
Competitive landscape — who matters and why
The market remains moderately concentrated: our concentration metrics indicate that the top three suppliers control a meaningful share of industry revenue, with the top five extending that dominance. That structure creates clear advantages for established Tier‑1s while opening targeted windows for specialist entrants.
- Bosch (Germany) — A leading systems player offering a broad portfolio of hydraulic and electrohydraulic solutions. Recent product showcases underscore its focus on Gen‑4 electrohydraulic systems that combine ADAS readiness with power-on-demand capabilities, positioning Bosch to retain share in higher-margin, integrated systems.
- ZF Friedrichshafen AG (Germany) — Continues to push Servocom and energy‑efficient hydraulic pump designs, while layering advanced electrohydraulic solutions for long‑haul trucks and buses. ZF’s dual focus on energy reduction and system integration keeps it competitive where OEMs require turnkey steering subsystems.
- Nexteer Automotive (United States) — Specialist in hydraulic pumps optimized for fuel efficiency and driver‑assist compatibility. Recent launches, including rear‑wheel steering modules and higher-capacity assist solutions, signal a strategy to move up‑market into larger commercial applications.
- Evamo (Germany) — A niche innovator in variable displacement vane pumps and electrohydraulic units targeting CO2 reductions; a strategic partner for OEMs chasing lightweight, low‑loss pump architectures.
- JTEKT Corporation (Japan) and Astemo (Japan) — Offer reliability‑focused hydraulic solutions and cast‑aluminum housings respectively, competing on durability and manufacturability for high‑duty cycles.
- Concentric AB (Sweden) — Distinct position in electric and electrohydraulic pumps for hybrid and fuel‑cell platforms, an option for OEMs transitioning away from belt‑driven pumps.
- Maval Industries (United States) — A specialist supplier for heavy‑duty pumps and gears; attractive for fleet retrofits and aftermarket programs.
Recent corporate moves reinforce two structural trends: incumbents scaling electrohydraulic product lines to capture ADAS and efficiency premiums, and specialised suppliers carving technical niches where integration complexity or fleet retrofit demand is highest.
Industry dynamics and risk vectors
- Regulatory acceleration: Proposed and enacted emissions targets for heavy‑duty vehicles are accelerating demand for low‑consumption steering architectures. Compliance timelines should be treated as project deadlines—delay can create stranded platforms.
- Maintenance & inspection rules: Leak‑free inspection regimes require materials and sealing strategies be re‑validated across product families; procurement specifications must be updated in 2026 contracts to avoid warranty exposure.
- Commodity volatility: Aluminum and steel price swings materially affect manufacturing economics for pump housings. The report quantifies pass‑through sensitivity and recommends contract structures and material substitutions to protect unit margins.
- Concentration risk: With near‑50% share held by the top three suppliers, OEMs face potential supplier power on price and availability. Our mitigation playbook outlines dual‑sourcing, design modularity and phased qualification to reduce program risk.
- Electrification disruption: Migration to electrified and fuel‑cell drivetrains reframes the role of engine‑driven pumps. Concentric and other electric‑pump specialists will be pivotal for OEMs seeking to decouple steering assist from engine speed.
Strategic recommendations for 2026
For executives finalizing 2026 CAPEX and product roadmaps, our prioritized recommendations are:
- Embed regulatory scenarios into product gating: Hardwire the most stringent emissions and inspection scenarios into alpha/beta engineering gates to avoid late-stage rework.
- De‑risk supply chains: Negotiate commodity‑indexed contracts with trigger clauses, qualify at least two suppliers per pump family, and adopt buffer strategies for critical components.
- Prioritize modular architectures: Design pumps and steering modules with common electrical and mechanical interfaces to enable platform reuse across hydraulic and electrohydraulic variants.
- Invest in systems integration capability: OEMs that control the integration software and power management for steering modules will capture disproportionate value as ADAS and electrification proliferate.
- Align aftermarket strategies with fleet retrofit economics: Create retrofit kits and certification pathways to monetize the installed base while accelerating transition to higher‑efficiency systems.
- Use M&A selectively: Target niche suppliers with proven variable‑displacement or electric pump IP to accelerate time‑to‑market without the risks of greenfield development.
How PW Consulting’s report supports boardroom decisions
This study was designed for commercial vehicle OEMs, Tier‑1 suppliers, private equity investors, and fleet operators who need immediate, defensible inputs for 2026 planning. It transforms headline growth assumptions and competitive intelligence into executable initiatives—budgetary templates, supplier scorecards, and scenario-proven TCO calculators—so that boards and strategy teams can make timely, lower‑risk choices.
Next steps & access to the full intelligence
This release is intentionally high‑level: it demonstrates our analytical approach and delivers strategic recommendations while deliberately omitting granular regional and application split figures that are central to program-level decisions. The full report contains the detailed regional and application segmentation, price‑and‑volume forecasts, supplier-level unit economics, and downloadable modeling files that procurement and engineering teams need to act immediately.
To obtain the comprehensive dataset, scenario models, and supplier scorecards referenced here, please visit PW Consulting’s Commercial Vehicle Power Steering Pump Market report page or contact our research desk for an executive briefing and a customized data package tailored to your 2026 planning horizon.
For detailed analysis of this topic, please visit the official page: Commercial Vehicle Power Steering Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com