

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dental Market to Hit USD 68.49B by 2032 at 9.25% CAGR

Dental Market 2026: A Strategic Preview — Why this PW Consulting Report Will Shape Your Next Move
Introduction
As the dental market accelerates into the second half of the decade, boards, corporate strategy teams, and PE sponsors face a compressed decision window. PW Consulting’s new Dental Market study — grounded in a seven-year historical baseline and a multi‑scenario forecast through 2032 — converts raw market momentum into executable choices for 2026. The market’s compound annual growth rate (CAGR) through the forecast horizon is 9.25%, reflecting a sustained structural expansion driven by demographic demand, technology adoption and shifting provider economics. Between the pre‑pandemic era and the report’s base year (2025) the industry moved from a mid‑twenty billion-dollar market to a mid‑thirty billion‑dollar baseline, with projections that more than double that footprint by the early 2030s under the central scenario. This preview explains why that growth matters for strategy, what we cover in the full study, and how to prioritize choices when timing and capital are constrained.
Dental Market
Why the 2026 Horizon Matters
- Capital allocation decisions must be timely. With market expansion accelerating into the late 2020s, 2026 is a hinge year for allocating capex to digital platforms, consumables automation and implant/digital workflows. Delaying investments risks losing share to incumbents who can scale faster across growing channels.
- Commercial models are in flux. The interplay between distributors, DSOs, and independent practices is reshaping go‑to‑market economics. Strategic choices made in 2026 — around distributor partnerships, e‑commerce, and bundled service offerings — will determine mid‑cycle margins.
- Regulatory and reimbursement headwinds are asymmetric. Recent guidance and reimbursement trends are stable but not inflation‑linked; manufacturers that redesign pricing and service packages now will protect unit economics into 2027 and beyond.
What We Mean by “Actionable” — Report Contents (high level)
The full report is structured to move leaders from insight to action. It does not merely present a forecast; it provides operational tools you can apply in the next 90–270 days. Key modules include:
Dental Market
- Market sizing and validated forecasting methodology (historical 2020–2025 baseline; forecast scenarios to 2032) — transparent assumptions and sensitivity bounds tied to adoption, pricing, and reimbursement inputs.
- Demand‑driver deep dives — aging demographics, elective esthetic demand, preventive care expansion, and digital orthodontics adoption curves, mapped to revenue levers and unit economics.
- Commercial playbooks — distributor negotiations, DSO/Group practice engagement models, direct‑to‑practice e‑commerce strategies, and subscription/service overlays that improve stickiness.
- Competition and M&A playbook — target screening criteria, buy/build vs partner matrices, integration risk checklists and valuation multipliers by business model.
- Operational stress tests — supply‑chain shock scenarios, raw‑material inflation passthrough models, manufacturing lead‑time optimization and alternative sourcing strategies.
- Regulatory & reimbursement tracker — a pragmatic checklist to prioritize market entries and product launches by jurisdictional risk and reimbursement sensitivity.
- Financial toolkits — pricing elasticity matrices, margin improvement templates, and three investor‑grade valuation case studies to support capital requests.
Note: the report intentionally withholds granular regional and application splits in this public preview. That level of granularity — which materially affects GTM and M&A decisions — is available in the full study and accompanying data pack.
Dental Market
Market Structure and Competitive Dynamics
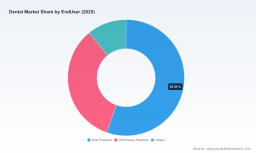
The dental market is large and consolidating, but remains open to disruptive entrants. Top firms collectively account for a meaningful share of global revenue, leaving room for well‑positioned challengers and specialized niche players. Our concentration analysis shows a market where the top three firms capture a plurality but not a dominating majority, and the top five widen that lead modestly — a structure that rewards scale while still permitting targeted entrants to win on specialization and channel control.
Company Positioning — Strategic Takeaways
- Dentsply Sirona: A broad portfolio owner with strength in equipment and implant systems. Their scale and channel reach make them a natural consolidator of workflow solutions; competitors must either partner or compete on highly differentiated digital services.
- Straumann Group: A premium implant and prosthetics leader with strong margin dynamics. Straumann’s strategy centers on vertical integration of implant systems, regenerative products and lab partnerships — a model that works best where clinicians can justify higher upfront spend.
- Align Technology: The clearest beneficiary of digital orthodontics trends. Its platform plays (clear aligners, scan‑to‑manufacture workflows) create recurring revenue and data assets; rivals should evaluate ecosystem strategies rather than one‑off product battles.
- Ivoclar Vivadent & GC Corporation: Specialists in materials and restorative solutions. Their wins depend on product innovation that lowers chair time or improves clinical outcomes; price‑value calculus is central when practices face reimbursement pressure.
- Coltene, Kerr, Parkell and other consumables innovators: Fast product cycles and point‑of‑care improvements allow nimble firms to capture share from incumbents that are slower to iterate.
- 3M Oral Care: A diversified industrial player that leverages R&D intensity in preventive and restorative categories; strategic play includes bundling materials with diagnostic tools.
- Distributors (Henry Schein, Patterson, Benco): Distribution remains a strategic choke point. Firms that secure preferred distributor economics, or which can disintermediate through superior e‑commerce experiences, will capture outsized gains.
Recent Product and Market Signals (What to Watch)
- Multiple firms launched next‑generation consumables and dental devices during 2025, signaling continued clinical innovation at the product level and compressed time‑to‑market for point‑of‑care tools.
- Manufacturers are increasingly using digital channels — including e‑commerce implant selection guides and online ordering — to shorten procurement cycles and gather practice usage data.
- Distributor and supplier ethics codes and revised trade guidance in 2025 are tightening commercial behaviors; compliance‑aware firms are adjusting contract terms and sales incentives accordingly.
Market Dynamics and Near‑Term Risks
Four dynamics will shape near‑term execution and valuations:
- Reimbursement pressure: Provider rates are broadly stable but have not kept pace with inflation and rising practice overhead. This compresses margins at the practice level and increases price sensitivity for devices and services that require higher upfront capital or consumable spend.
- Raw material and supply volatility: Input prices rose in 2025, and many manufacturers are experiencing higher component costs and longer lead times. Firms with flexible sourcing and localized manufacturing will be advantaged.
- Regulatory clarity: Updated codes of ethics and regional compliance guidance are changing commercial interaction models between manufacturers, distributors and clinicians. This creates short‑term friction but longer‑term transparency benefits for companies that move early.
- Labor and practice economics: Employment dynamics in dental offices are recovering but remain volatile. Headcount and wage pressures influence adoption rates for labor‑saving technologies and subscription service models.
Strategic Imperatives — How Executives Should Respond in 2026
- Prioritize products that reduce chair time and drive recurring consumable revenue. The intercept between time‑savings and recurring consumables creates the most defensible revenue streams.
- Build distributor resilience and digital channels in parallel. Strengthen distributor partnerships while piloting direct digital offerings in select markets to capture learning without destabilizing channel relations.
- Use scenario planning tied to reimbursement and supply shocks. Stress test pricing and adoption assumptions for 2026 launches under conservative reimbursement scenarios and a range of input‑cost shocks.
- Target M&A for workflow consolidation, not just product lines. The most valuable targets are those that fill gaps in practice workflows — digital scanning, lab integration, or DSO enablement — rather than narrow component plays.
- Operationalize compliance and ethics early. Firms that align commercial incentives to updated codes of conduct will reduce transaction costs and insurance risks when scaling internationally.
How PW Consulting’s Report Helps You Execute
This study is built for practitioners: scenario‑driven forecasts, a competitive playbook with vendor performance indicators, M&A scoring templates, and operational checklists that you can deploy with minimal customization. The report’s data pack contains the granular regional and application splits, price elasticities and channel economics that underpin 2026 go‑to‑market and M&A decisions — information we deliberately exclude from this public preview to protect commercial sensitivity and to drive a single source of truth for strategic projects.
Conclusion — A Call to Action for 2026
The dental market’s trajectory presents both scale and complexity. Growth is robust, but it favors organizations that align capital, commercial design and operational resilience now. PW Consulting’s Dental Market study is designed to translate the headline CAGR and market momentum into pragmatic moves: what to build, who to buy, when to partner, and how to price for a world where reimbursement and input costs are increasingly dynamic. For leaders preparing 2026 budgets and M&A pipelines, the earliest actionable advantage will come from integrating forecast scenarios with execution playbooks — precisely what this report delivers.
To access the full dataset, regional and application splits, and the implementation templates referenced in this preview, please consult the complete PW Consulting report and data pack.
For detailed analysis of this topic, please visit the official page: Dental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com