

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
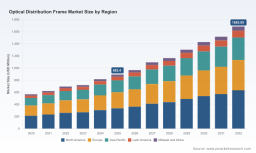
PW Consulting: Optical Distribution Frame Market to Reach USD 1,685.09 Million by 2032

Optical Distribution Frame Market — Strategic Intelligence for 2026 Decision-Making
As communications networks scale to meet the demands of AI, cloud-native services and densified metro and edge access, the Optical Distribution Frame (ODF) market is entering a decisive growth chapter. PW Consulting’s latest industry study — anchored on a 2025 base year and projecting through 2032 — translates historic performance and forward-looking scenarios into a practical strategic playbook for executives, product leaders and investors planning actions in 2026. This preview highlights the report’s strategic value, outlines the market trajectory and competitive dynamics, and describes the operational deliverables that will directly inform capital allocation, product roadmaps and go-to-market choices. To preserve the tactical edge our clients pay for, detailed sub-segment tables and granular regional splits are intentionally withheld here; those datasets are available in the full report.
Optical Distribution Frame Market
Why this research matters in 2026
- Align CAPEX with structural growth: The ODF market has shifted from steady replacement cycles to capacity-driven expansion. Executives need validated forecasts to justify multi-year procurement and manufacturing investments.
- Prioritize product architecture choices: Decisions between ultra-high-density hyperscale designs, modular rack systems and service-oriented wall/floor mounts have material margin and lifecycle implications. Our analysis maps expected demand profiles to technical trade-offs.
- Mitigate supply-chain and sourcing risks: The study identifies bottlenecks, alternative materials and supplier concentration risks that will influence lead times and component cost volatility during 2026 procurement windows.
- Guide M&A and partnership activity: With the market showing measurable concentration among incumbents, targeted acquisitions and JV frameworks can accelerate scale or bring complementary technology into your portfolio.
- Inform go-to-market segmentation: Field sales and channel strategies must balance hyperscale wins against large telco and enterprise accounts. The report provides the evidence base to reweight commercial investments.
Market trajectory — the macro story
ODF demand has shown consistent expansion over the past half-decade and is poised to accelerate as network operators and data center builders densify fiber terminations. PW Consulting’s topline sizing traces this evolution: the global market expanded meaningfully during 2020–2025 as fiber deployments and data-center capacity ramped, and our baseline projection anticipates a near-term uplift in 2026 followed by sustained growth through 2032. Quantitatively, the study uses a 2025 base-year figure to calibrate models and applies scenario-driven adoption curves to generate a forecast path that converges on a multi-hundred-percent cumulative increase by the end of the planning window. The underlying compound annual growth rate (CAGR) we apply for the forecast period is 9.5%, reflecting a mix of replacement cycles, new-build hyperscale installations and accelerated last-mile fiberization initiatives.
Optical Distribution Frame Market
Two implications drive the strategy we recommend: first, investment timing matters — early movers who scale pre-assembled, high-density ODF platforms will capture premium hyperscale and enterprise projects; second, flexibility is essential — modular and front-access platforms will remain attractive to customers seeking lower-risk integration and staged deployment.
Optical Distribution Frame Market
Demand drivers and technology vectors
- Hyperscale data-center densification: AI workloads and converged routing fabrics are increasing fiber terminations per rack. High-splice-count, pre-assembled ODFs that simplify installation and reduce fiber handling are gaining traction.
- Telco fiberization and PON wave: Continued national broadband initiatives and operator upgrades to higher-split PONs drive telecom-grade ODF adoption in both central offices and cabinetized deployments.
- Edge and micro data centers: As computing moves closer to end users and devices, demand for compact, easy-to-service ODFs in non-traditional facilities is rising.
- Serviceability and automation: Features such as tracer fiber circuits, light-guidance for identification and tool-less modularity materially reduce mean time to repair and installation labor costs — differentiators in procurement decisions.
Competitive landscape — positioning and dynamics
The ODF market combines incumbent scale players with specialized manufacturers delivering verticalized solutions for hyperscale, telecom and enterprise customers. Market concentration metrics show that the top three vendors account for a substantive share of global revenue, and the top five further extend that concentration — a structure that favors firms with integrated product portfolios and world-class channel footprints.
- Amphenol Network Solutions (Liberty Lake, WA): Traditionally focused on high-performance connectivity, Amphenol has pushed into the hyperscale ODF niche with pre-assembled, very-high-splice-count frames that emphasize rapid deployment and lower onsite labor. Recent product introductions highlight single-fiber splicing support and tracer-fiber guidance — capabilities that directly address AI-driven data center mesh requirements.
- Huawei Technologies (Shenzhen): Huawei continues to field indoor-focused ODF series tailored for carrier access and cabinet applications. Their product set targets compatibility with standard rack sizes and high port counts in a compact footprint — a profile that appeals to telco operators modernizing access fabrics.
- CommScope (Hickory, NC): CommScope’s modular ODF platforms emphasize front-access serviceability, tool-less installation and ecosystem interoperability. Their platforms are positioned to win in environments that prioritize staged growth and cross-vendor patching simplicity.
Strategically, these vendors illustrate three viable go-to-market archetypes: hyperscale-first (pre-assembled, ultra-dense frames), carrier-optimized (space-constrained, standard cabinet compatibility) and modular-serviceable (field-configurable, integration-friendly). Each archetype carries distinct margin profiles, channel requirements and R&D imperatives.
Recent industry signals
Product innovation is accelerating. For example, a notable 2026 product launch introduced a hyperscale ODF capable of very high splice counts per frame and integrated tracer-fiber identification, packaged for pre-assembled deployment. This kind of product underscores how suppliers are responding to labor scarcity, on-site deployment risk and the need to compress build-out schedules for AI-capable facilities.
What the full PW Consulting report delivers
Our full study is structured to be immediately actionable for commercial, product and corporate development teams. Highlights include:
- Comprehensive market sizing and validated forecasts (historical 2020–2025 base, 2026–2032 forecast) with scenario modelling calibrated to infrastructure spend cycles and data-center capacity plans.
- Demand-driver analysis that links fiber counts, splice requirements, and deployment typologies to product specifications and service-cost outcomes.
- Supplier and product benchmark profiles, including technology capabilities, manufacturing footprint considerations and route-to-market assessments.
- Commercial playbooks for targeting hyperscale, telco and enterprise accounts — including tender positioning, specification negotiation levers and value-based pricing templates.
- Supply-chain risk mapping and mitigation options, highlighting critical components, lead-time hedges and alternative sourcing strategies.
- Scenario-based financial models and an interactive dataset that allows executives to stress-test revenue, margin and investment outcomes under different adoption curves.
- Go-to-market checklists, procurement-ready RFP language, and M&A screening criteria tailored to the ODF space.
Note: granular sub-segment tables and regional breakdowns are part of the full dataset; they are excluded from this preview to preserve the proprietary value delivered to PW Consulting’s clients.
Strategic takeaways and recommended actions for 2026
- For the C-Suite: Treat ODF strategy as a capacity-and-serviceability decision, not just a component purchase. Use the 9.5% forecast growth framework to align three-year CAPEX plans with anticipated order cadence, and prioritize suppliers who can guarantee delivery windows and pre-assembly options.
- For Product Leaders: Accelerate development of modular, tool-less designs and integrated tracer or identification features. A differentiated serviceability story reduces lifecycle operating expense — an increasingly persuasive procurement argument.
- For Supply-Chain Leaders: Secure long-lead items with multi-year purchase agreements and qualify second-source suppliers for critical polymer and metal components. Reducing lead-time variability is a high ROI activity in 2026.
- For Go-to-Market Teams: Create parallel plays: one focused on hyperscale and cloud builders with turnkey, pre-assembled offers; another that addresses telco retrofit and cabinetized installations with flexible rack and wall-mount options.
- For Corporate Development: Use the market concentration landscape to identify bolt-on acquisitions that either increase share in a target archetype or add niche capabilities (e.g., tracer fiber tech, splice automation) that accelerate differentiation.
How to use this briefing and next steps
This article is a strategic preview: it sets the agenda and outlines the action priorities for 2026. Executives ready to translate these insights into executable plans should access the full PW Consulting report for the underlying datasets, segmented forecasts and supplier scorecards. The full deliverable includes editable financial models, RFP language and an interactive dashboard to explore scenarios by geography, installation type and buyer segment — tools necessary to convert insight into competitive advantage.
PW Consulting is available to run bespoke workshops in which our analysts will apply the report’s models to your specific network plans and procurement timelines, producing a prioritized, time-phased investment and sourcing roadmap for 2026–2028.
Closing perspective
ODFs are no longer commoditized junctions in fiber networks — they are strategic enablers that influence deployment speed, operating cost and long-term serviceability. With the market expanding on a trajectory that implies durable demand growth, decisions made in 2026 about product architecture, supplier relationships and inventory strategies will materially affect competitive position through the next cycle. The PW Consulting study equips leaders with the quantitative baseline, competitive context and tactical playbooks necessary to navigate this inflection point. For the detailed segment tables, vendor scorecards and actionable models that power procurement and strategic decisions, consult the full report.
For detailed analysis of this topic, please visit the official page: Optical Distribution Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com