

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Marine Engineering Hydraulic Piling Hammer Market to Expand at 5.3% CAGR, Forecast to Reach USD 257M by 2032 as Asia‑Pacific Leads with USD 82.6M
By pmarketresearch, 2026-07-13
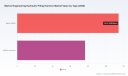
Marine Engineering Hydraulic Piling Hammer Market — Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present an executive briefing drawn from our latest Marine Engineering Hydraulic Piling Hammer Market study. The research consolidates five years of historical performance (2020–2025) and delivers an actionable forecast through 2032. This briefing highlights the strategic implications that matter for 2026 capital planning, procurement, and technology road‑mapping — while reserving the full, granular segmentation and vendor scorecards for the report itself.
Marine Engineering Hydraulic Piling Hammer Market
Executive snapshot
- Market scale: The global market for hydraulic piling hammers reached approximately USD 191.0 Million in the base year (2025).
- Growth trajectory: Our forecast anticipates a compound annual growth rate (CAGR) of about 5.3% over the 2026–2032 horizon, with the market trending toward the upper‑end of the USD 200–260 Million range by the end of the period under standard scenarios.
- Demand drivers: Rapid offshore wind capacity additions, sizeable port and coastal infrastructure programs, and renewed bridge/harbour investment cycles are the dominant structural drivers shaping purchase patterns and fleet composition.
Why this report matters for 2026 decisions
2026 will be a pivotal year for firms managing heavy marine foundation works. Developers, EPC contractors, port authorities, and equipment lessors face a converging set of pressures: larger monopile sizes, stricter underwater‑noise regulation, constrained supply chains for specialized steel and hydraulic systems, and the economics of owning versus renting high‑value units. Our study translates market-level dynamics into concrete decision levers for procurement, operations, and R&D investment so organizations can avoid cost overruns and secure project timelines.
Marine Engineering Hydraulic Piling Hammer Market
Market outlook — what to expect in 2026 and beyond
The mid‑decade profile is one of steady expansion rather than explosive growth. With a 5.3% CAGR baked into our forecast, the market is large enough to support multiple global OEMs and rental providers, while still encouraging differentiation through technology, service and niche specialization.
Marine Engineering Hydraulic Piling Hammer Market
- Scale and timing: Projected yearly market flows support a predictable cadence of new unit deliveries and aftermarket support contracts. That predictability helps procurement teams align CAPEX and rental strategies to avoid both under‑capacity and over‑investment.
- Price and input pressures: High‑capacity hammer systems are capital‑intensive. Specialized materials and hydraulics mean individual units carry multi‑million dollar capital price tags; this remains a primary source of cost volatility and a lever for negotiating long‑lead supplier agreements.
- Regulatory drag: Stringent underwater noise mitigation regimes in sensitive habitats are not marginal — they typically add measurable schedule and cost increments to piling campaigns. Our field synthesis indicates mitigation measures can extend timelines and reshape operational windows, necessitating earlier engagement between engineering, environmental and procurement teams.
Strategic implications for 2026 planning
Below are focused actions that should be considered immediately by organizations that commission or deliver marine foundation works:
- Adopt a hybrid ownership model. Given capital intensity and sporadic project pipelines, a mix of owned and rented hammers reduces balance‑sheet exposure while preserving rapid deployment capability for peak periods.
- Integrate noise mitigation into early tendering. Plan for mitigation systems (e.g., bubble curtains, attenuation arrays) and schedule buffers at RFP stage: otherwise bids will be non‑competitive or project timelines will slip.
- Lock long‑lead supplier agreements. Early framework agreements with steel fabricators, hydraulic component vendors and OEMs yield price stability and delivery predictability in 2026–2027 windows.
- Prioritize modularity and retrofitability. Choose systems with upgrade paths for control electronics, hammer energy envelopes and noise‑reduction add‑ons to extend service life as monopile dimensions and regulatory standards evolve.
- Build scenario financial models. Use scenario analyses (base, upside, policy/constraint) to stress test fleet sizing and rental needs over 3–5 year horizons — our report includes templated cashflow and TCO models to accelerate that work.
Competitive landscape — who matters and why
The hammer market is concentrated around a set of globally capable OEMs and a growing tier of regional suppliers. This creates a competitive dynamic where technological leadership, service networks and track record of large‑monopile performance determine tender outcomes more than price alone.
- MENCK GmbH (Acteon) (Kaltenkirchen, Germany) — A benchmark name in high‑capacity, double‑acting hydraulic impact hammers. Their product portfolio targets monopiles and deepwater foundations and benefits from significant reference exposure in large offshore wind programs. MENCK’s recent control‑system upgrades reflect a maturation toward integrated automation and drive efficiency gains in monopile installation campaigns. (See: https://www.acteon.com)
- IQIP (Sliedrecht, Netherlands) — Known for the Hydrohammer S‑series and IQ‑series, IQIP continues to push capacity boundaries, including water‑driven variants engineered for ultra‑deep applications. A notable 2025 product introduction signals IQIP’s intent to capture next‑generation monopile works by offering high‑capacity, digitally controlled systems. (See: https://iqip.com)
- BRUCE Piling Equipment (Siheung, South Korea) — Focused on energy‑efficient designs compatible with crane‑suspended and leader‑mounted operations, Bruce’s equipment appeals to port and bridge contractors where versatility and on‑site adaptability are decisive.
- Junttan Oy (Kuopio, Finland) — A specialist in leader‑mounted hammers with a strong footprint in marine terminal and coastal projects. Junttan’s emphasis on noise and vibration reduction aligns with regulatory trends and community acceptance considerations. (See: https://junttan.com)
- Chinese OEMs and research institutes — A cohort of manufacturers and research bodies has rapidly matured domestic capabilities, deploying very large single‑acting systems in regional offshore wind programs and advancing noise reduction features. These players are shaping competitive pricing and local supply dynamics.
Collectively, top OEMs control a substantial portion of high‑capacity project awards, though opportunities remain for niche innovators and service‑oriented competitors who can demonstrate compliance, uptime and integrated noise solutions.
Technology and operational priorities
The next wave of differentiation will be technical and operational rather than purely mechanical. Our fieldwork and supplier interviews identify three priority vectors:
- Control systems and automation — higher precision energy delivery and digital monitoring reduce re‑drives and improve pile integrity outcomes.
- Acoustic mitigation integration — OEMs that can supply hammer‑level noise attenuation packages or seamless third‑party integration will win tenders in noise‑sensitive jurisdictions.
- Service and logistics networks — proven global service footprints and rapid parts delivery are decisive for contractors operating on tight installation windows.
Report contents — what you will find inside
The PW Consulting report is structured as a tactical playbook for 2026. Highlights include:
- Market sizing and forward scenarios with discrete CAPEX/OPEX modeling templates for purchase vs rental decisions.
- Vendor benchmarking and procurement scorecards focusing on technical fit, lifecycle cost, delivery lead time and noise‑mitigation capability.
- Project playbooks for offshore wind and port/bridge works covering logistics, scheduling buffers driven by noise mitigation, and contractor/OEM coordination checklists.
- Supply‑chain risk maps with mitigation strategies for critical inputs (steel, high‑pressure hydraulics) and recommended contracting approaches for price and delivery protection.
- Regulatory impact assessments showing how operational windows and mitigation measures affect schedule and cost across representative project archetypes.
Practical next steps for 2026
- Commission a rapid portfolio review: align current fleet capabilities to 2026 pipeline and identify capability gaps where rental or partnership is prudent.
- Engage OEMs early on noise‑mitigation and delivery milestones to lock windows and accelerate permitting.
- Run a pilot retrofit for noise reduction on at least one unit to validate CAPEX payback and operational impacts before wider roll‑out.
- Adopt the report’s procurement scorecard for upcoming RFPs to standardise evaluation across technical, commercial and environmental dimensions.
Conclusion — the strategic payoff
For organizations that move decisively in 2026, the payoff is twofold: fewer schedule and compliance surprises, and materially better unit‑economics across your pile‑driving fleet. The market’s steady growth and technological evolution reward those who combine disciplined procurement, early noise‑mitigation planning, and vendor alliances that guarantee upgrades and service. PW Consulting’s full report packages the analytics, templates and vendor intelligence required to convert the market’s growth into project success — while protecting margins and reputations in noise‑sensitive environments.
To access the complete dataset, vendor scorecards, and bespoke modelling tools referenced here, please consult the PW Consulting Marine Engineering Hydraulic Piling Hammer Market report webpage — where the full, actionable intelligence is available to support your 2026 strategy and tender teams.
For detailed analysis of this topic, please visit the official page: Marine Engineering Hydraulic Piling Hammer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: External Tooth Slewing Bearing Market Poised to Reach USD 3,873.1 Million by 2032 on a 6.85% CAGR
By pmarketresearch, 2026-07-13
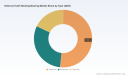
External Tooth Slewing Bearing Market: Strategic Intelligence for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a distilled, actionable orientation for executives shaping their 2026 plans in the external tooth slewing bearing ecosystem. Our new market research—anchored on a 2025 base year and a 2026–2032 forecast horizon—combines rigorous market-sizing, competitive diagnostics, and operable playbooks. This briefing highlights the strategic value of the report for corporate leaders while preserving the “trailer” principle: we demonstrate analytical depth and direction without disclosing the proprietary segment-level figures that differentiate the full report.
External Tooth Slewing Bearing Market
Executive snapshot: market scale, trajectory, and concentration
Key macro facts every boardroom should internalize. The external tooth slewing bearing market reached roughly USD 2,435.8 Million in 2025 (base year). Our modeling forecasts a compound annual growth rate (CAGR) of 6.85% over the 2026–2032 period, taking the market toward an estimated USD 3,873.1 Million by 2032. These headline dynamics reflect structural demand across heavy construction, renewables, and industrial modernization.
External Tooth Slewing Bearing Market
Market concentration is meaningful but not prohibitive: the top three players command close to 42.5% of the market, while the top five together approach 58.3%. That mix creates a landscape of dominant, global incumbents alongside a broad field of regional and specialist suppliers—an environment that rewards scale, engineering differentiation, and supply chain agility.
External Tooth Slewing Bearing Market
Why this market matters in 2026
-
Capital projects restarting after multi‑year uncertainty are lifting demand for heavy‑duty slewing rings. The combined effects of infrastructure stimulus in some geographies and ongoing wind‑power installations underpin multi‑year order pipelines.
-
Wind energy OEMs and tower suppliers continue to prioritize large‑diameter, externally geared slewing bearings with tight tolerances and proven fatigue life—creating a premium segment that favors manufacturers with extensive metallurgical and heat‑treatment expertise.
-
Raw material dynamics matter: high‑chromium alloy steels (e.g., 42CrMo4) remain the dominant metallurgy for these components, and steel accounts for an outsized share of production materials. Price volatility and environmental regulation are direct cost and compliance levers that will shape supplier margins and capital needs through 2026.
-
Aftermarket and replacement demand (including third‑party replacements) is a persistent revenue pool that smart OEMs and independent manufacturers monetize via service agreements, certifiable replacements, and logistics optimization.
What our report delivers — practical, transaction‑ready intelligence
Decision‑makers require more than directional insight. The full PW Consulting report provides operationally actionable content designed to support investment, procurement, and go‑to‑market decisions:
-
Validated market sizing and a probabilistic forecast model (2026–2032) with scenario toggles for commodity shocks, demand acceleration, and regulatory tightening.
-
Competitive benchmarking of global manufacturers by capability (e.g., large‑diameter manufacturing, external gear machining, heat treatment, aftermarket services) and go‑to‑market tactics.
-
Supply chain risk maps and mitigation playbooks—covering raw material exposures, supplier single‑sourcing, and logistics flex options.
-
M&A and JV heatmaps identifying targets whose assets (tooling, proprietary heat treatment, distribution networks) deliver immediate scale or technical synergies.
-
Commercial levers and pricing frameworks—including value‑based pricing templates for ruggedized, high‑precision slewing bearings and service bundles.
-
Capex and footprint optimization models to inform localization, nearshoring, or consolidation decisions.
Competitive landscape: players, positioning, and tactical implications
The industry blends long‑established engineering leaders with nimble, specialized manufacturers. Our report profiles—and models the competitive behavior of—companies that define the sector:
-
SKF (Gothenburg, Sweden): A global engineering system supplier with both standard and bespoke external‑tooth slewing bearings, SKF differentiates through scale, broad aftermarket channels, and the ability to supply very large diameters for heavy applications. For competitors, SKF’s strength lies in integrated supply and service propositions; for OEMs, it offers a de‑risked single‑vendor option for large programs.
-
thyssenkrupp rothe erde (Lippstadt, Germany): A segment leader in very large‑diameter slewing rings, thyssenkrupp leverages deep materials and manufacturing know‑how. Its strategic play is in engineering customization and long‑cycle, high‑value projects (e.g., turbine foundations, large cranes), creating a high barrier for entrants in these niches.
-
Kaydon Bearings (SKF Group) (Muskegon, USA): Focused on precision slewing rings with proven external gear series, Kaydon’s strengths are precision engineering and niche OEM relationships—especially where rotational accuracy and tight clearances are imperative.
-
Chinese manufacturers and specialists (e.g., Fenghe, XZWD, Tedin, SlewMaster): These suppliers combine cost competitiveness, rapid customization, and aftermarket agility. Many compete successfully on replacement parts and heavy machinery retrofit markets. Their volume play creates pricing pressure but also expands addressable demand by lowering total installed‑cost thresholds for some OEMs.
-
RIMA S.p.A. and similar European specialists : They focus on four‑point contact designs and geared solutions for lifting and earthmoving equipment, prioritizing engineering sophistication and compliance with European standards.
Strategic implication: incumbents with scale and advanced metallurgy will continue to win large, complex programs; small and mid‑sized players will capture aftermarket, retrofit, and cost‑sensitive OEM segments. For participants, the pathway to premium margins runs through engineering IP, integrated service offers, and validated quality systems.
Supply chain realities and material policy
Material inputs are the single most important cost and technical determinant in 2026. Two facts are essential for procurement and operations leaders:
-
High‑chromium alloy steels (notably grades such as 42CrMo4) remain the production mainstay, and steel comprises roughly 88.6% of the material mix for slewing ring bearings as of 2025. Any procurement strategy must therefore treat steel price volatility and availability as strategic risks.
-
Tightening environmental regulations are already pushing manufacturers to optimize heat‑treatment processes and to integrate higher recycled‑steel content into production—changes that affect both CAPEX (new furnaces, process controls) and OPEX (energy, cycle time). Early movers can convert compliance into a competitive advantage through validated, lower‑CO2 product lines.
Recommended operational moves include multi‑tiered supplier contracts with price collars, strategic inventory buffers keyed to lead‑time variability, supplier development programs for secondary material qualification, and investments in process automation to tighten quality and reduce scrap rates.
Top strategic actions for 2026 (prioritized)
-
Reposition product portfolio: Segment offerings into premium engineered solutions (large diameter, tight‑tolerance external gear) and cost‑optimized lines for replacement and mid‑market OEMs. Align go‑to‑market teams accordingly.
-
Hedge raw material exposure: Implement financial and physical hedges for key steel inputs, and qualify recycled‑content supply streams to anticipate regulatory shifts.
-
Invest in metallurgy and heat treatment: Capex directed to process control and metallurgy pays back through improved fatigue life and lower warranty costs—factors that materially improve tender success on high‑value projects.
-
Monetize aftermarket: Build certified replacement programs and service agreements; use digital condition monitoring to move from reactive replacement to predictive maintenance offerings.
-
Pursue targeted M&A: Acquire capabilities that shorten time to market (bearing machining, gear hobbing, heat treatment) or open new distribution corridors; prioritize bolt‑on targets that improve CR3/CR5 position in desired geographies.
-
Compliance and sustainability: Publish product lifecycle emissions and align with customer decarbonization timelines—this reduces procurement friction with large infrastructure and renewables customers.
Why PW Consulting’s report is the decisive tool for 2026 decisions
Boards and executive teams need more than intuition in 2026; they need reproducible, auditable decision tools. Our report combines proprietary demand‑mapping, supplier scoring, and sensitivity models with industry‑validated assumptions—built from trade show intelligence (e.g., The Bearing Show North America, Zhengzhou Exhibition, 2026) and primary interviews with OEMs and bearings manufacturers.
Included in the full deliverable are deployment‑ready artifacts: a dynamic forecasting workbook, supplier risk dashboards, a 36‑month commercialization timeline template, and an M&A valuation sleeve that converts technical synergies into cash‑flow impacts. These are the assets that enable procurement teams, CFOs, and business unit leaders to convert market insight into execution plans without ambiguity.
Closing: the strategic inflection in 2026
The external tooth slewing bearing market is at an inflection where technical differentiation, supply chain resilience, and sustainability credentials determine which players capture the fastest growth and the highest margins. With a 6.85% CAGR projected through 2032 and a market value approaching USD 3.87 billion by the end of the forecast horizon, this domain is sufficiently large to sustain competing business models—provided those models are tightly aligned to material realities and customer total cost of ownership.
PW Consulting’s full report translates these macro realities into executable plans. For teams preparing budgets, negotiating supplier contracts, or evaluating M&A in 2026, the granular scenario analyses and step‑by‑step playbooks in the full study are purpose‑built to reduce downside and accelerate capture. To access the comprehensive dataset, proprietary segmentation, and transaction‑ready templates, please visit the PW Consulting report page for External Tooth Slewing Bearing Market (full report access required).
For detailed analysis of this topic, please visit the official page: External Tooth Slewing Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Portable Color Fish Finder Market to Climb from USD 235.4 Million in 2025 to USD 382.8 Million by 2032 at 7.15% CAGR — Wireless Portable and North America Dominate (CR3 48.5%)
By pmarketresearch, 2026-07-13
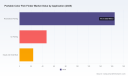
Portable Color Fish Finder Market — 2026 Strategic Outlook (PW Consulting)
PW Consulting today releases an executive preview of our latest Portable Color Fish Finder Market study — a practical guide for executives making decisive investments in 2026. The study synthesizes five years of historical performance (2020–2025) with a seven-year forecast (2026–2032). Our base-year analysis shows the market expanding from USD 142.35 Million in 2020 to USD 235.40 Million in 2025, with a projected trajectory to USD 382.75 Million by 2032. The forecast period (2026–2032) assumes a compound annual growth rate of 7.15%. Competitive concentration is meaningful — the top three vendors account for a near-majority share, while the top five extend that concentration further — a structure that shapes M&A and channel strategy decisions for 2026.
Portable Color Fish Finder Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 will be the inflection year where product-level differentiation and software ecosystems begin to outweigh pure hardware advances. Investment choices made this year will determine whether organizations capture fast‑growing segments or cede them to more nimble players.
Portable Color Fish Finder Market -
Capital allocation: With steady double‑digit absolute growth in recent years and a mid‑single‑digit CAGR ahead, firms must balance R&D spend, channel expansion, and selective M&A to secure durable returns.
Portable Color Fish Finder Market -
Competitive posture: Market concentration signals both barrier opportunities (scale economics) and niche openings for specialists — especially in adjacency products and services (apps, mapping, subscription data).
Report scope and hands‑on deliverables
This study is designed as a tactical instrument for strategy teams, product managers, and corporate development groups. Rather than a high‑level narrative, the report delivers:
-
A validated top‑down and bottom‑up market model with downloadable scenario outputs for conservative, base, and aggressive demand paths.
-
Feature prioritization matrix: ranked tradeoffs across sonar type, display technology, battery life, waterproofing, wireless connectivity, and mounting options tailored to buyer personas.
-
Go‑to‑market playbooks for direct, dealer, and e‑commerce channels — including pricing levers, promotional cadence, and content strategies to raise attach‑rates for services and maps.
-
Supply‑chain risk heatmap and component cost analysis covering displays, sonar transducers, power modules, and PCBAs, with mitigations for single‑source exposures.
-
M&A and partnership scorecards to identify targets that deliver rapid scale, tech augmentation (imaging/AI), or strategic channel access.
-
Operational KPIs and a weekly dashboard template to monitor early indicators and trigger mid‑course corrections.
Strategic imperatives for 2026
Our analysis crystallizes six imperatives that should drive boardroom and product planning conversations in 2026.
-
Prioritize software and UX as product differentiators. As basic imaging capabilities commoditize, integrated mapping, mobile app synchronization, firmware‑driven features, and over‑the‑air updates will be the primary competitive battleground.
-
Adopt a modular hardware roadmap. Design platforms that can host multiple sonar stacks and display options to shorten time‑to‑market and enable segmented pricing without full redesigns.
-
Expand recurring revenue levers. Subscription models for bathymetric maps, crowdsourced fish‑structure databases, and premium navigation layers materially increase lifetime value and create defensive moats.
-
Shape channel economics for scale. Rebalance incentives across dealers, OEM boat partnerships, and online channels to optimize margin while expanding reach into rapidly growing micro‑segments (kayak, ice, and small craft).
-
Mitigate component concentration risks. Secure multi‑source supply for displays and power modules, nearshore assembly options, and inventory pooling agreements to reduce lead time volatility.
-
Activate adjacent ecosystem plays. Consider partnerships with battery makers, mapping companies, and outdoor‑lifestyle platforms to drive bundled purchases and cross‑sell opportunities.
Competitive landscape — what the market structure means
The portable color fish finder segment today is anchored by a handful of established electronics and marine brands. Our company briefs highlight the strategic axes each firm operates on:
-
Garmin Ltd. (Olathe, Kansas) — Strength: GPS and mapping integration plus a broad consumer electronics ecosystem. Strategic play: deepen software monetization and cross‑sell within wearables and marine portfolios.
-
Johnson Outdoors Inc. (Humminbird) (Racine, Wisconsin) — Strength: advanced side and down imaging; trusted brand among serious anglers. Strategic play: premium product segmentation and pro‑level feature sets for tournament and specialist users.
-
Navico (Lowrance) (Tulsa, Oklahoma) — Strength: active imaging sonar and a wide product cascade from entry to high end. Strategic play: drive volume through channel relationships and OEM integrations with small boat manufacturers.
-
Vexilar Inc. (Minneapolis, Minnesota) — Strength: niche focus on ice fishing and compact displays. Strategic play: protect niche leadership while exploring adjacent portable solutions for open‑water anglers.
Collectively, the market shows meaningful concentration at the top tiers but still offers entry points for focused challengers — particularly those that combine hardware competence with compelling software and service offerings.
Early signals to watch in 2026 (metrics that matter)
-
Software attach rate: percentage of devices linked to paid services or apps within 90 days.
-
Average selling price (ASP) movement across product bands — watch for compression in the entry tier and premiumization upstream.
-
Channel mix shift: dealer versus direct e‑commerce and OEM bundling rates.
-
Unit shipment growth vs. ASP-driven revenue growth to understand whether growth is value or volume driven.
-
Component lead times and input‑cost trends (displays, transducers, battery cells) as predictors of margin pressure.
-
Customer retention on mapping/subscription services and the rate of feature adoption in deployed installed bases.
How to use this report to accelerate initiatives in 2026
Boards and leadership teams should use this study as an action framework. Practical next steps we recommend for Q1–Q2 2026:
-
Run a three‑day strategy sprint using our scenario models to reallocate R&D budgets toward high‑ROI software and UX projects.
-
Deploy an M&A screening exercise against our scorecards to surface tuck‑ins that accelerate software capabilities or distribution scale.
-
Implement a supply‑chain quick win plan: diversify two critical components, secure contractual options for capacity, and adopt a weekly risk dashboard.
-
Launch a pilot subscription offering in one prioritized geography and product band, instrumented to capture conversion and churn metrics.
Conclusion — positioning for durable advantage
The portable color fish finder market is maturing from a hardware‑led category into a platform where software, data, and partnerships determine winner outcomes. With a solid historical track record and a forecasted mid‑single‑digit CAGR through 2032, firms that move in 2026 to integrate superior UX, diversify supply, and monetize services will capture disproportionate share and margin. Our full report provides the detailed segmentation, financial models, company scorecards, and playbooks necessary to execute those moves — while preserving the competitive detail that leaders need to act decisively.
For access to the complete study, interactive models, and tailored advisory support to convert these insights into a 100‑day plan, visit PW Consulting’s report page or contact your PW Consulting account team.
For detailed analysis of this topic, please visit the official page: Portable Color Fish Finder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Facial Recognition Payment Devices Market to Grow at 19.85% CAGR During 2026–2032
By pmarketresearch, 2026-07-13
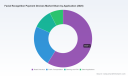
Facial Recognition Payment Devices Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market research on Facial Recognition Payment Devices synthesizes seven years of historical performance with a seven‑year forward outlook to arm boards, payment architects, and deployment teams with the intelligence required to make confident decisions in 2026. The market for facial recognition payment devices has transitioned from niche pilots to measurable commercial traction: total industry revenue rose from USD 7.85 Million in 2020 to USD 20.1 Million in our 2025 base year, and our financial model projects expansion to USD 73.25 Million by 2032 at a compound annual growth rate (CAGR) of 19.85% across the 2026–2032 forecast window. This brief unpacks the report’s strategic value while deliberately withholding deep sub‑segment breakouts to guide practitioners toward the full study for procurement‑grade detail.
Facial Recognition Payment Devices Market
Why this market matters to enterprise decision‑makers in 2026
-
From pilot to program: In many industries — from retail to transport, hospitality to quick‑serve restaurants — facial recognition moved from proof‑of‑concepts to operational pilots between 2020 and 2025. Our dataset captures that transition and quantifies the pace at which vendors, integrators, and operators are converting pilots into revenue‑generating deployments.
Facial Recognition Payment Devices Market -
Structural growth with practical inflection points: The double‑digit CAGR projected into the early 2030s reflects not just vendor hype but concrete drivers — improved 3D sensing hardware, software maturity in biometrics, POS platform integrations, and institutional acceptance. For 2026 planning cycles this translates to timing decisions: when to pilot, when to scale pilots, and when to move from vendor selection to long‑term partnership agreements.
Facial Recognition Payment Devices Market -
Consolidation and concentration: The market exhibits a mid‑level concentration: the top three vendors account for a significant share but are far from monopolistic, and the top five consolidate over half of industry revenue. That profile creates competitive supplier dynamics favourable to large buyers seeking strategic leverage while demanding rigorous vendor risk management.
What our report delivers — practical, decision‑ready content
PW Consulting’s report is designed as a playbook, not simply an academic exercise. The deliverables are structured to support procurement cycles, technology roadmaps, and compliance workstreams across 2026 implementations:
-
Market sizing and validated demand scenarios — multiple, auditable demand curves that map to enterprise adoption triggers and macroeconomic sensitivity. These scenarios enable CFOs and strategy leads to stress‑test investment cases under conservative, baseline, and accelerated adoption paths.
-
Vendor evaluation frameworks — comparative scorecards covering technology maturity, hardware‑software integration, certification and auditability, privacy‑by‑design, commercial terms, and service delivery capabilities. The framework converts qualitative vendor claims into quantifiable procurement metrics.
-
Deployment and operations playbooks — step‑by‑step templates for pilot design, biometric accuracy validation, enrollment UX, edge vs cloud processing tradeoffs, on‑premises vs managed service TCO, and long‑term maintenance scheduling. These are field‑tested by PW Consulting across multiple retail and transport pilots.
-
Regulatory and privacy checklists — jurisdictional decision trees that map legal obligations to design choices, including consent flows, data retention policies, and breach response plans. The checklists are pragmatically aligned with the latest regulatory developments to reduce legal friction during rollouts.
-
Risk and ethics scorecard — an operationally focused tool to quantify and track reputational, regulatory, and algorithmic fairness risks tied to deployments. The scorecard is built to be embedded in vendor SLAs and enterprise governance frameworks.
-
Integration and ecosystem guidance — reference architectures, API patterns, and partner profiles that reduce time‑to‑integration with POS platforms, payment processors, and loyalty systems.
Competitive landscape — who matters and why
The vendor landscape spans hardware specialists, POS OEMs, pure‑play algorithm developers, and system integrators. PW Consulting’s competitive review synthesizes product roadmaps, distribution channels, and strategic partnerships to identify where to source core capabilities and where to expect third‑party consolidation activity.
-
Newland NPT (Fuzhou, China) — a POS OEM that pairs payments engineering with facial capabilities, positioned to serve retail and unattended environments. Its strength lies in scale of terminal distribution and field service reach for multi‑site rollouts.
-
Telpo (Guangdong, China) — notable for depth‑camera and 3D sensing integration in its C‑series payment terminals. Telpo’s value proposition is focused on financial‑grade authentication and self‑checkout use cases that require liveness detection.
-
PAX Technology (Shenzhen, China) — a global Android POS platform player expanding into multimodal biometrics through partnerships. PAX’s momentum underscores an important route to market: platform‑enabled integrations that accelerate merchant adoption.
-
NEC Corporation (Tokyo, Japan) — a systems integrator and algorithm leader, demonstrating high‑profile hands‑free experiences at financial events and large exhibitions. NEC illustrates the value of combining enterprise‑grade algorithms with payments ecosystems (e.g., demonstrated integrations with Stripe Terminal).
-
VisionLabs (Amsterdam), PopID (Pasadena), PayByFace B.V., Intema, Orbbec — a mix of algorithm suppliers, payments‑centric startups, and sensor module vendors. These companies collectively supply critical software IP, UX design, and sensing components that enable differentiated merchant experiences.
Recent industry moves give practical signals for procurement timing: NEC’s demonstrations of integrated, hands‑free checkout and its in‑field deployments at major venues indicate enterprise readiness for contactless retailing; PAX’s partnership activity shows POS vendors are accelerating multimodal biometric roadmaps. Buyers evaluating pilots in 2026 should expect increasing interoperability between POS platforms and biometric providers — and should insist on measurable metrics for accuracy, false acceptance/rejection rates, and liveness performance as contractual gates.
Regulatory landscape and operational risk — realities for 2026
Regulation is the single most important external variable influencing adoption timelines. Two regulatory developments are particularly consequential for 2026 planning:
-
China’s Security Management Measures for Facial Recognition Technology (effective June 1, 2025) — these measures require justification of necessity, restrict mandatory use where alternatives exist, and introduce registration thresholds for large‑scale processing. Enterprises operating in or sourcing from China must factor new compliance controls into vendor assessments and procurement contracts.
-
The EU AI Act (high‑risk obligations effective from August 2025) — biometric systems used in identification and payments are subject to risk assessments, documentation, and prohibitions on certain uses (for example emotion‑scoring). The Act increases the compliance burden for deployments in the EU and for vendors who sell into EU markets.
Our report converts these legal texts into operational requirements: consent and data mapping templates, registry triggers, developer documentation obligations, and audit plans that buyers can insert into RFPs to ensure regulatory traceability from procurement through decommissioning.
Practical recommendations for enterprise leaders in 2026
-
Adopt an evidence‑based pilot approach: start with operational environments that minimize privacy surface‑area and allow for measurable impact on throughput and conversion metrics. Use A/B testing to isolate biometric impact on transaction speed, lift in average ticket, and customer satisfaction.
-
Embed regulatory compliance into vendor contracts: require vendors to supply documentation that aligns with jurisdictional obligations (risk assessments, technical documentation, and data processing agreements) and include termination rights tied to regulatory changes.
-
Insist on independent performance validation: third‑party verification of accuracy, demographic performance variance, and liveness detection should be contractually mandated before scaling beyond pilot phase.
-
Negotiate commercial flexibility: given the market concentration profile, buyers can secure multi‑vendor strategies or platform‑level integrations to avoid single‑source lock‑in while optimizing TCO across hardware refresh cycles.
-
Plan for privacy‑first UX: design enrollment and opt‑in flows that are transparent, reversible, and frictionless. The success of biometric payments will depend as much on customer trust as on raw biometric accuracy.
Conclusion — how PW Consulting’s study helps you make the right call in 2026
For executives preparing 2026 budgets and operational roadmaps, our research offers a clear, actionable view of where facial recognition payments stand today and where they are headed. We provide validated market sizing, strategic vendor analysis, regulatory playbooks, and deployment templates that convert abstract opportunity into executable programs. The market’s projected growth trajectory — rising sharply from the 2025 base year and anticipated to expand robustly through 2032 — creates a window for early scale advantages, but regulatory constraints and measurable performance gates mean that cautious, evidence‑driven scaling will reward disciplined early movers.
This release is a high‑level preview intended to outline strategic direction and operational priorities. For procurement teams, technology leaders, and policy managers who require segment‑level metrics, vendor scorecards, contract language, and the full suite of deployment templates, access to the full report is required. Visit our report page to obtain the complete study and the downloadable toolset to accelerate your 2026 program planning.
For detailed analysis of this topic, please visit the official page: Facial Recognition Payment Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Pressure Washers Market Set to Expand at a 5.12% CAGR During 2026–2032, New Report Finds
By pmarketresearch, 2026-07-13
PW Consulting Strategic Brief: High Pressure Washers Market — 2026 Decision-Maker Playbook
Executive snapshot
The global high pressure washers market has evolved from a niche equipment category into a strategic industrial and consumer platform. Our updated market model (base year 2025, historical 2020–2025, forecast 2026–2032) shows the industry scaling from approximately USD 3.78 billion in 2020 to USD 5.18 billion in 2025, with a projected rise to roughly USD 7.35 billion by 2032. That trajectory implies a compound annual growth rate (CAGR) of 5.12% across the 2026–2032 forecast window — a steady expansion driven by product innovation, channel shifts, regulatory pressures and replacement cycles.
High Pressure Washers Market
Why this matters for 2026 strategy
For executives setting priorities in 2026, this market profile is not academic: it defines capital allocation, M&A timing, R&D roadmaps and go-to-market choices. A mid-single-digit CAGR in an equipment market with tangible serviceable-repair economics creates recurring revenue opportunities — not just one‑off sales. At the same time, industry concentration metrics indicate a moderately fragmented competitive field (CR3 ~28.5%, CR5 ~42.8%), creating persistent pockets of local leadership, scale advantages for global platform players, and acquisition targets for mid-market consolidation.
High Pressure Washers Market
What PW Consulting’s report delivers (operationally focused)
- Proprietary seven-year financial forecasts and scenario matrices calibrated to macroeconomic and materials inputs, with sensitivity to tariffs and raw material inflation.
- Actionable go-to-market playbooks for OEMs and channel partners: product segmentation, pricing tiering, and after-sales monetization strategies tailored to residential, commercial and industrial buyers.
- Supply‑chain and cost-to-build models down to component-level drivers — including an industry-validated insight that engines and pumps account for approximately 77% of a typical unit’s bill of materials and manufacturing cost.
- M&A prioritization framework and 12-month shortlist methodology for bolt-on targets, divestment candidates and cross-border strategic partnerships (includes playbooks for post-merger integration).
- Safety and compliance matrix covering key standards (UL, GFCI, relief valves, hose guards) and a risk response workbook to contain recall exposure and regulatory enforcement.
- Technology and channel roadmaps: battery electrification, app-enabled service ecosystems, modular product architectures, and trade/distributor optimization including recommendations for inventory and warranty strategies.
- Customizable decision dashboards and scorecards so leadership teams can quantify trade-offs across price, performance, service and capital intensity.
Near-term market dynamics shaping 2026 decisions
Several converging forces will define winners and laggards in the coming 18–36 months:
High Pressure Washers Market
- Regulatory and liability pressure. Recent recall activity (notably an expanded recall covering specific electric-start models announced in 2026) has sharpened focus on combustion safety and product labeling. Compliance with UL safety standards — including relief valves, hose guards and GFCI protection on electrical models — is table stakes. Companies must treat safety engineering and traceability as strategic assets to protect brand equity and margins.
- Component concentration and cost exposure. With engines and pumps comprising the dominant share of unit cost, procurement strategies that reduce single-supplier risk or secure long-term price agreements will materially affect gross margins. Tariffs on steel and certain imported components further amplify this dynamic, favoring vertically integrated or regionally hedged manufacturers.
- Technology and channel bifurcation. Battery-powered and app-connected models are changing buyer expectations in residential and light-commercial segments, while traditional gas-powered equipment and heavy-duty triplex/diaphragm pump systems retain relevance in industrial applications. Companies that can span these technology poles with shared platforms and service offerings will be advantaged.
- Service-first economics. Extended warranty, preventive maintenance subscriptions and rapid parts fulfillment are becoming differentiators, especially in commercial and industrial accounts where uptime value exceeds the initial purchase price.
Competitive landscape — positioning and strategic implications
The market blends global brand leaders, specialized pump OEMs and diversified power-equipment firms. Several dynamics emerging from recent corporate actions warrant attention:
- Alfred Kärcher SE & Co. KG (Germany): Reinforces leadership through broad product breadth across residential, commercial and industrial lines and a continued push on professional cleaning initiatives and new model introductions. Strategy implication: competitors should anticipate Kärcher’s combined product-service offers in premium segments and plan differentiated service economics.
- Nilfisk Group (Denmark): Completed a strategic divestment of its US high pressure washer business in late 2025, concentrating its professional presence in core markets. Strategy implication: divestments create whitespace for regional entrants and a moment to evaluate market-share capture via targeted investments or partnership arrangements.
- Generac Power Systems (USA): Remains a prominent source of residential and light-commercial units, though recent recall/ regulatory events underscore operational and reputational risk. Strategy implication: firms should prioritize design for safety and invest in risk management capabilities to avoid costly remediation.
- Annovi Reverberi (AR North America) and Alkota Cleaning Systems: Represent critical component and systems suppliers for higher pressure and industrial configurations. Strategy implication: OEMs reliant on triplex/diaphragm pump expertise should secure supplier relationships or evaluate insourcing scenarios to ensure performance continuity.
- Briggs & Stratton, Stanley Black & Decker (DeWalt), TTI (Ryobi/Milwaukee), Bosch and Simpson Cleaning: These players highlight a mix of powertrain, brand, and channel strengths — from small-engine integration to battery-electrified offerings and construction‑grade durability. Strategy implication: cross-category competition from power-tool and engine incumbents accelerates the need for brand differentiation and channel partnerships.
How PW Consulting recommends you act in 2026
- Prioritize product safety and traceability programs. Immediate investment in design validation, supplier audits and a centralized recall-response playbook will reduce exposure and preserve trust.
- Lock down pump and engine supply through multi-year contracts or strategic equity partnerships. Given their outsized cost contribution to units, these components should be the focal point of procurement and risk mitigation.
- De-risk through modular platform strategies. Design common chassis and electronics stacks that can span gas, electric and battery-powered variants to shorten time-to-market and reduce SKU proliferation in distribution channels.
- Build recurring revenue engines. Deploy service subscriptions, consumables and certified refurbishment programs for commercial and industrial customers to improve lifetime value and margins.
- Use M&A opportunistically. Moderate fragmentation plus recent divestments creates attractive bolt-on opportunities for scale buyers and private equity; focus on regional leaders with strong after-sales footprints or unique pump/engine capabilities.
- Adapt channel economics to marketplace shifts. Strengthen distributor partnerships for professional channels and invest in direct-to-consumer e-commerce and last-mile logistics where residential demand is shifting online.
Report methodology and confidence posture
Our forecasting methodology combines bottom-up bill-of-materials models, supplier price indexes, field sales data and primary interviews across OEMs, large distributors and professional cleaning contractors. We run parallel scenario sets for tariff shocks, accelerated electrification and accelerated urbanization to stress-test capital and working-capital needs. The resulting forecasts — anchored on a 2025 base and covering 2026–2032 — are therefore intended to support capital planning, business-case development and M&A diligence with high-confidence guidance.
What we are intentionally withholding here (and why)
In keeping with the “trailer” principle that guides this briefing, we are intentionally not publishing the granular regional and application-level splits, nor the detailed unit-price ladders and proprietary M&A target rankings in this release. Those items are core to competitive positioning and commercial negotiation — and they are included in the full PW Consulting report and interactive data dashboards. If your team requires the precise segmentation matrices, channel elasticity coefficients, or the full list of prioritized acquisition targets and their financial overlays, these are available through our report access portal.
Next steps for executives
- Request a tailored briefing: PW Consulting can provide a 90-minute executive session that overlays the forecast with your product and channel portfolio to identify 90-day critical actions.
- Commission a focused cost-to-build audit: 8–12 week engagement to validate BOM exposure and identify supplier consolidation or dual-sourcing pathways.
- Engage our M&A screening service: rapid diligence on divestment targets and accretive tuck-ins aligned to your growth and service model objectives.
Decision-makers who treat the high pressure washers market as a systems business — where components, safety, service and channels interlock — will convert steady top-line growth into sustainable margin expansion. For complete regional breakdowns, application-level forecasts, proprietary valuation models and the full suite of operational playbooks, visit the PW Consulting report page or contact our research team for an exclusive executive briefing.
For detailed analysis of this topic, please visit the official page: High Pressure Washers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Leak Detection Equipment Market Valued at USD 4,158.5 Million in 2025, Poised to Grow at a 5.85% CAGR During 2026–2032
By pmarketresearch, 2026-07-13
Automatic Leak Detection Equipment Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As companies plan budgets, procurement and product strategies for 2026, automatic leak detection (ALD) has moved from a niche technical capability to an operational and regulatory imperative. PW Consulting’s new market study — based on a 2025 base year and projecting through 2032 — shows a market that expanded steadily through the early 2020s and is forecast to continue growing at a mid-single-digit CAGR. The market grew from roughly USD 3.1 billion in 2020 to about USD 4.16 billion in 2025, with our model projecting a rise to approximately USD 6.19 billion by 2032 at a compound annual growth rate of 5.85% (2026–2032). These headline figures understate a more nuanced reality: demand drivers are increasingly regulatory and service-led, and competitive dynamics point to selective consolidation rather than a winner-takes-all outcome (CR3 ~38.5%; CR5 ~52.7%).
Automatic Leak Detection Equipment Market
Why this report matters for 2026 decision-making
-
Compliance-driven procurement: New and tightening regulations mean that ALD is now a line-item in capital and operational project plans for refrigeration OEMs, utilities, pipeline operators and commercial real estate managers. Companies making 2026 purchasing or retrofit decisions need validated cost and deployment scenarios that reflect the new regulatory timelines.
Automatic Leak Detection Equipment Market -
Technology selection under uncertainty: Multiple sensing approaches — from acoustic and fiber-optic monitoring to pressure- and gas-based detectors — are commercially mature, but their value depends on deployment scale, asset topology and service model. Our study offers decision frameworks for selecting a technology mix that balances sensitivity, false-alarm profiles and lifecycle cost without disclosing the proprietary split-level allocations in the full dataset.
Automatic Leak Detection Equipment Market -
Channel and service strategy: For vendors and systems integrators, the opportunity is as much in recurring monitoring and managed services as it is in hardware sales. The report identifies how vendors can convert one-time equipment sales into subscription-like revenue through analytics, permanent monitoring networks and SLA-backed inspection services.
What the report contains — practical content for immediate action
-
Market sizing and methodology: A transparent reconciliation of historical volumes and value (2020–2025) with scenario-based forecasts for 2026–2032, accompanied by sensitivity ranges and model access for licensed clients.
-
Regulatory impact models: Quantified implications of recent rules (including refrigerant-focused ALD mandates and pipeline detection performance standards) on near-term demand and retrofit cycles, with timelines and cost buckets for planning CAPEX and O&M.
-
Technology due diligence playbook: Side-by-side evaluation templates that score vendor technology across detection performance, integration complexity, installation time and lifecycle cost—designed to be reused directly during RFP and pilot phases.
-
Vendor benchmarking and sourcing matrix: Comparative profiles of established and emerging suppliers, go-to-market posture and service footprint — with executable vendor shortlists for utility, industrial and refrigeration procurements (note: detailed segment allocations and vendor market shares are included in the full report only).
-
Commercial templates and case studies: Negotiation checklists, sample service agreements and retrofit phasing templates built from live project data across water utilities, pipelines, industrial sites and commercial buildings.
-
M&A and investment thesis: Deal-screening criteria and valuation approaches for investors seeking exposure to ALD hardware, software analytics platforms and managed-monitoring service businesses.
Market dynamics shaping the 2026 agenda
Three forces are creating an urgent 12–24 month agenda for buyers and suppliers alike:
-
Regulatory acceleration. Recent rulemaking has moved ALD from guidance to enforceable requirement in several end markets. Notably, refrigerant-focused mandates require automatic leak detection systems to be operational within 30 days for new commercial and industrial refrigeration appliances with large refrigerant charges (effective Jan 1, 2026), and require retrofits on a defined cadence for pre-existing equipment by January 1, 2027. Separately, pipeline safety regulators have established advanced leak detection performance standards for gas transmission systems.
-
Shift from episodic inspection to continuous monitoring. Permanent networked monitoring (including acoustic and hydrophone-based permanent loggers and fiber-optic distributed sensors) is gaining traction in high-consequence infrastructure because it reduces detection time and enables analytics-driven prioritization of field crews.
-
Service economics and lifecycle thinking. The revenue opportunity is being rebalanced toward recurring services (monitoring, verification, false-alarm management) as owners seek to convert capital outlays into predictable operational performance. Vendors that combine hardware with software subscriptions and field-service SLAs are positioned to capture disproportionately high lifetime value.
Competitive landscape — what to watch among core players
The ALD sector is characterized by a mix of specialist instrumentation firms, industrial OEMs with system-level offerings, and service-centric players. The competitive set we profile in this study — including InterTech Development Company, Veeder-Root, GUTERMANN AG, INFICON and Hermann Sewerin GmbH — illustrates the range of strategic approaches currently winning business:
-
InterTech Development Company (Skokie, IL) : A specialist in automated leak and flow test systems, InterTech’s patented mass-flow and hydraulic technologies address high-precision industrial and medical applications. Recent trade-show visibility (MD&M West, Feb 2026) highlights demand in high-speed manufacturing and medical-device leak testing where throughput and resolution are critical. Strategic implication: InterTech’s strengths fit customers prioritizing production-line speed and traceability, and the company is a logical partner for OEMs that require embedded testing in manufacturing lines.
-
Veeder-Root (Simsbury, CT) : Established in tank gauging and digital pressurized line leak detection, Veeder-Root’s solutions are recognized for regulatory compliance in fuel storage and pipeline contexts. For buyers confronting fuel and fuel-handling regulations, Veeder-Root’s systems offer a credible compliance path with mature operational support networks. Strategic implication: companies operating distributed fueling assets should prioritize vendors with demonstrated regulatory testability and field-service coverage.
-
GUTERMANN AG (Zug, Switzerland) : A leader in acoustic detection for water networks, GUTERMANN has recently expanded its permanent monitoring line with a high-sensitivity hydrophone logger launched in late 2025. This product release underlines a market shift toward permanent detection in plastic-pipe networks. Strategic implication: utilities planning long-term leakage reduction programs should evaluate permanent acoustic networks as part of asset-management roadmaps, not only as one-off detection tools.
-
INFICON (Bad Ragaz, Switzerland) : INFICON’s gas-leak detection portfolio (helium, hydrogen, refrigerant, vacuum) plays to manufacturing and service markets where trace-gas detection underpins product quality and safety. Their breadth across tracer gases positions them well where regulators or customers demand traceable leak-rate verification. Strategic implication: manufacturers with strict quality controls or service providers conducting instrumented maintenance will find INFICON’s portfolio compelling.
-
Hermann Sewerin GmbH (Gütersloh, Germany) : With acoustic correlators, ground microphones and pipe locators, Sewerin is a strong contender in utility and municipal markets. Their field-hardened tools and channel relationships with contracting crews make them a logical choice for capital projects and reactive leakage programs. Strategic implication: procurement strategies should account for the ease of integration with existing field teams and training pathways — an area where Sewerin shows strength.
Strategic recommendations for 2026
-
Start retrofit procurement cycles now. Organizations subject to the 2027 retrofit deadlines should initiate pilot and procurement processes in 2026 to avoid compressed installation windows and higher spot-market prices for field services.
-
Prioritize vendors offering integrated compliance evidence. Select solutions that not only detect leaks but also provide audit-ready records and verification workflows to reduce compliance effort and downstream inspection costs.
-
Run a technology pilot that measures both detection performance and false-alarm handling costs. Sensitivity alone is not a business-case winner; end-to-end signal-to-action time and the effort required to validate events determine the operational ROI.
-
Evaluate service-partner networks as a differentiator. For large or geographically dispersed portfolios, the availability of certified local service, calibration and emergency response should be weighted heavily in vendor selection.
-
Consider layered procurement: combine permanent monitoring in high-risk corridors with portable and periodic systems elsewhere to optimize capital and O&M spend.
-
For investors and acquirers: look for businesses combining hardware, software analytics and recurring service revenue. These hybrid models command premium multiples as markets move from capex-driven to service-centric economics.
Why PW Consulting’s analysis is different
Our research blends a rigorous bottom-up market model with practical, executable outputs that executives can use immediately. Key differentiators include scenario-calibrated forecasts anchored to recent regulatory milestones, executable procurement templates, vendor scorecards designed for RFP use, and deployment playbooks that account for field labor, permitting and verification workflows. We intentionally present headline market and concentration metrics in this brief to orient readers; the complete report contains the full regional, type and application splits, vendor market shares, and transactional datasets that underpin our conclusions.
Next steps
For procurement leads, asset owners, systems integrators and investors preparing 2026 plans, the window to influence vendor selection, pilot outcomes and compliance pathways is short. Access the full PW Consulting Automatic Leak Detection Equipment Market report to obtain the complete segmentation, vendor benchmarking tables and downloadable decision tools necessary to convert these insights into executable plans. Contact PW Consulting via our website to request the full report and a tailored briefing that maps findings to your asset portfolio and regulatory obligations.
For detailed analysis of this topic, please visit the official page: Automatic Leak Detection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Tester Market Poised to Reach USD 774.25 Million by 2032
By pmarketresearch, 2026-07-13
Handheld Tester Market 2026: A Strategic Playbook for Executive Decision‑Making
Executive summary
As companies prepare budgets, R&D roadmaps, and channel strategies for 2026, understanding the trajectory of the handheld tester market is essential. PW Consulting’s latest market study shows a market that has expanded meaningfully from its 2020 base and is on track to deliver mid‑single‑digit to high‑single‑digit returns for manufacturers, distributors, and system integrators over the coming seven years. Specifically, the global market grew from the low hundreds of millions of USD in 2020 to approximately USD 456.5 Million in the 2025 base year and is forecast to continue expanding at a compound annual growth rate (CAGR) of 7.85% through 2032, reaching roughly three‑quarters of a billion USD by the end of the forecast window.
Handheld Tester Market
This press release outlines the strategic implications of those macro dynamics for enterprise decision‑makers in 2026: where to allocate R&D and product investment, how to optimize go‑to‑market motions, which competitive moves to anticipate, and what regulatory and end‑market forces will most influence returns. The goal is to present the analytical framing and actionable playbooks found in the full PW Consulting report—while preserving the proprietary, granular detail available exclusively in the full dataset and interactive dashboards.
Handheld Tester Market
Why 2026 is a strategic inflection point
- Scale meets sophistication: The market’s sustained growth to 2025 and the projected CAGR through 2032 indicate both expanding demand and rising product complexity. Buyers are no longer purchasing simple, single‑function tools alone; they seek integrated solutions that reduce carry burden and increase diagnostic throughput in the field.
- Cost of downtime and safety pressure: Multiplying uptime costs across telecom, utilities, manufacturing, and emerging electrified mobility segments raises willingness to pay for higher‑accuracy, certified handhelds and bundled service offerings.
- Regulatory and compliance thresholds: IEC safety standards (including CAT ratings) and jurisdictional certification requirements (such as NRTL approvals under OSHA frameworks) are shaping product specs, procurement cycles, and aftermarket service obligations.
Market dynamics that shape commercial strategy
The market’s growth is driven by a mix of structural and tactical factors. Structural forces include broader electrification trends, accelerated fiber and 5G deployments, and diffusion of distributed generation. Tactical dynamics include suppliers’ product roadmaps, channel economics, and a rising appetite for instruments that converge electrical, network, RF and environmental measurement capabilities.
Handheld Tester Market
- Convergence of capabilities: Expect an expanding share of new offerings to combine traditional electrical measurements with network and RF diagnostics, environmental sensing and enhanced user interfaces (touch, AR‑assisted readouts, cloud connectivity).
- Field instrumentation becomes software‑defined: Firmware flexibility, modular test libraries, and remote calibration/management platforms are shifting value from pure hardware to recurring software and services revenue.
- Safety and certifications as purchase drivers: Compliance to IEC requirements and local certification schemes is a gating factor for enterprise procurement—driving longer lead times but also enabling differentiation for compliant vendors.
- Niche pockets of premiumization: Certain end‑use segments—particularly those with critical uptime or regulatory obligations—are migrating to higher‑end handhelds with built‑in logging, traceable calibration, and secure cloud connectivity.
What the PW Consulting report delivers (practical contents)
The full report is intentionally focused on operational utility for strategic teams. Highlights include:
- Time‑series market sizing and demand modelling calibrated to 2020–2025 tracked data and scenario projections through 2032.
- Channel and buyer segmentation frameworks that map procurement triggers, lead times, and total cost of ownership considerations for enterprise and contractor buyers.
- Product taxonomy and roadmap implications, with prioritized feature sets mapped to buyer willingness‑to‑pay and adoption timelines.
- Competitive positioning matrices and supplier scorecards (product breadth, innovation cadence, channel strength, certification coverage, after‑sales services).
- Go‑to‑market playbooks for suppliers targeting three strategic moves: premiumization and service monetization, low‑cost footprint expansion, and platformization via software ecosystems.
- Regulatory impact analysis that translates standards (IEC, OSHA/NRTL and local rules) into product requirements and compliance cost buckets.
- Deal‑level negotiation guidance and price‑benchmark ranges for enterprise procurement teams (presented as ranges and indexed comparables rather than raw contract figures).
- An interactive data workbook (available to clients) enabling custom slicing by feature set, buyer persona and time horizon—useful for capex planning and M&A screening.
Competitive landscape: strategic takeaways
The handheld tester market blends heritage test instrument vendors with specialized newcomers that are pushing connectivity and RF capability into handheld form factors. The PW Consulting analysis profiles incumbent global manufacturers and targeted challengers, assessing their strengths and strategic postures.
- Established industrial players (e.g., Fluke Corporation): Durable product portfolios, extensive service networks, and deep safety‑certification footprints are their primary defensibility. These firms should prioritize software monetization and retrofit service models to capture aftermarket revenue while protecting margins against low‑cost entrants.
- Specialists in insulation and power test equipment (e.g., Megger Group): Focused expertise in high‑voltage and commissioning tools supports premium positioning for utilities and heavy industry. Strategic play: deepen partnerships with utility OEMs and offer integrated commissioning packages that include handhelds, data logging, and cloud analytics.
- Contractor‑oriented brands (e.g., Klein Tools): Strong channel intimacy with electrician communities and trade distributors is an advantage for penetration at scale. Their path forward lies in expanding modular accessory ecosystems and financing/insurance bundles to make higher‑tier tools accessible.
- RF and 5G‑capable entrants (e.g., Siglent Technologies): Recent product launches integrating spectrum analysis, VNA capabilities, and cable/antenna testing into compact handhelds signal a clear move to capture field technicians supporting 5G rollouts. For incumbents, this is a cue to accelerate cross‑domain feature integration or partner with RF specialists.
- Precision metrology brands (e.g., Hioki): Focus on measurement accuracy and ergonomic design suits safety‑sensitive applications. Strategic emphasis should be on certification breadth, calibration services, and long‑term reliability guarantees.
- Niche and regional specialists (e.g., Seaward, Sonel, Chauvin Arnoux): These players often win on localized product fit, competitive pricing, or specialized use cases (solar PV installation, PAT testing, environmental sensors). Scale advantage can be achieved through selective distribution alliances and shared service infrastructures.
Notably, product innovations such as the compact SHA860A series (announced in April 2025) that integrate spectrum analysis and vector network functions exemplify the convergence trend and underscore the importance of monitoring adjacent technology domains when crafting 2026 plans.
Practical recommendations for corporate leaders (2026 action agenda)
- For product leaders: Prioritize modular architectures that allow software‑led feature activation. Invest in embedded connectivity and secure telemetry to enable SaaS tie‑ins and remote calibration services.
- For commercial leaders: Rebalance channel incentives toward value plays (warranty, calibration subscriptions, training) rather than pure unit discounts. Build OEM and system integrator bundles for priority verticals (telecom rollout, utilities, automotive diagnostics).
- For compliance and quality teams: Bake IEC CAT rating and local certification requirements into product development gates to avoid go‑to‑market delays. Consider third‑party lab partnerships to accelerate approvals in key jurisdictions.
- For M&A and corporate development: Screen targets that add RF/5G capabilities, cloud‑native service platforms, or regional distribution strengths. Use the report’s scenario modelling to quantify revenue synergies under conservative and aggressive adoption cases.
- For procurement: Shift procurement KPIs to lifecycle cost metrics that include calibration, downtime costs, and data management—this will reveal hidden value in higher‑spec instruments and service bundles.
Risk factors and watchlist
- Regulatory shifts: Changes in safety certifications or new national testing requirements could lengthen product certification timelines and increase compliance costs.
- Technology displacement: Rapid adoption of software or cloud substitutes for certain handheld functions (edge diagnostic apps, smartphone sensor modules) could compress margins on commodity products.
- Supply chain volatility: Component scarcity and tariff dynamics can disproportionately affect higher‑spec handhelds that rely on specialized RF or sensor modules.
Concluding perspective and next steps
For executives planning 2026 investments, the handheld tester market presents a clear opportunity: demand is growing and converging toward multifunction, connectivity‑enabled tools, while regulatory and safety imperatives create barriers that reward established, certifying vendors and disciplined challengers. The strategic choices made in 2026—about modular product design, software and services monetization, certification roadmaps, and targeted M&A—will determine which players capture the most attractive portion of market growth.
PW Consulting’s full Handheld Tester Market report provides the granular segmentation, supplier scorecards, pricing models, and interactive scenario tools necessary to translate these high‑level insights into executable plans. To access the complete dataset, benchmark dashboards, and our recommended 12‑ to 36‑month playbooks, please visit the PW Consulting report page or contact our industry practice to arrange a briefing and bespoke modelling session.
For detailed analysis of this topic, please visit the official page: Handheld Tester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Belt Tensioner Market to Rise from USD 1,609.85 Million in 2025 to USD 2,434.10 Million by 2032 at a 6.08% CAGR
By pmarketresearch, 2026-07-13
PW Consulting Releases Strategic Brief: Industrial Belt Tensioner Market Outlook 2026 — Actionable Roadmap for Executive Decision-Making
Executive summary
PW Consulting today publishes a strategic briefing drawn from our upcoming Industrial Belt Tensioner Market report (base year 2025; historical window 2020–2025; forecast horizon 2026–2032). The market finished 2025 at approximately USD 1,610 Million and enters the 2026 planning window with momentum consistent with a mid-single-digit compound annual growth trajectory (CAGR 2026–2032: 6.08%). Our forecast model projects the market to re-accelerate over the medium term, reaching a multi-billion dollar scale by the end of the planning horizon. For 2026 specifically, the market path implies near-term demand expansion that will require executives to make targeted product, supply chain, and commercial decisions in Q1–Q2 to capture outsized share.
Industrial Belt Tensioner Market
Why this briefing matters for 2026 strategic choices
- Market timing: With baseline market scale set in 2025 and a 6.08% CAGR baked into our central scenario, 2026 acts as an inflection year where commercial investments and operational shifts begin to compound returns through 2032.
- Cost and supply volatility: Raw-material volatility—particularly in natural rubber and steel—has moved within a wide band in recent years (annual swings of 20–35% have been observed), creating margin pressure and forcing re-engineering of sourcing strategies.
- Regulatory pressure and product differentiation: Updated EU emissions and industrial efficiency standards introduced in 2025 accelerate buyer preference toward energy-efficient and low-emissions drive systems, changing specification criteria for belt tensioners and increasing the importance of lifecycle energy metrics.
- Competitive structure: The market displays moderate concentration among the largest incumbents, producing both risk and opportunity: nimble players can pursue niche specialization, while larger firms can leverage scale to integrate upstream or expand aftermarket service offerings.
What the full report delivers — practical, implementation-ready content
Our report is designed as an executive-to-execution toolkit for 2026 planning. Rather than generic market commentary, clients receive decision-ready assets that translate forecast signals into capital, commercial, and product actions:
Industrial Belt Tensioner Market
- Proprietary forecast model (2026–2032) with scenario toggles for demand elasticity, raw-material price shocks, and regulatory stringency — enabling rapid re-run of ROI on proposed investments.
- Supplier risk matrix and hedging playbook that maps component-level exposures to procurement levers (long-term contracts, multi-source qualification, nearshoring thresholds).
- Pricing-sensitivity and margin-impact simulator to evaluate value-based pricing, indexation clauses, and cost-pass-through strategies under realistic procurement cycles.
- Go-to-market playbooks for OEM, aftermarket, and industrial-distribution channels — including partner economics, inventory policies, and warranty/cost-of-ownership arguments tailored to industrial buyers.
- Product and R&D prioritization framework aligning design choices (e.g., automatic vs. fixed tensioners, sensor-enabled tension monitoring) with targeted customer segments and regulatory requirements.
- M&A and partnership screening filters that identify high-fit targets (sensor suites, aftermarket distributors, regional manufacturing footprints) and produce an integration-value estimate.
- Implementation roadmaps and KPI dashboards to convert strategic choices into board-level deliverables within a 6–18 month window.
To preserve the strategic advantage for clients, the public briefing is intentionally selective: detailed segment-level demand tables, regional and application splits, and deal-by-deal valuation worksheets are reserved for the full report and consulting engagements.
Industrial Belt Tensioner Market
Competitive landscape — positioning and near-term dynamics
The market is served by a mix of global industrials, niche specialists, and regional fabricators. Our competitive analysis highlights how product breadth, engineering depth, aftermarket reach, and service propositions shape strategic options for 2026.
- Gates Corporation (Denver, CO): A broad product portfolio and heavy-duty engineering footprint make Gates a natural scale player in power-transmission systems. Their range enables value capture across OEM and heavy-industrial aftermarket channels; the strategic implication for rivals is to either differentiate on precision/innovation or pursue adjacency through partnerships.
- Fenner Drives (Manheim, PA): Specialization in rotary and linear self-adjusting tensioners positions Fenner to command technical leadership in applications where automated compensation reduces maintenance downtime — a growing procurement criterion for capital-equipment buyers seeking TCO reductions.
- BRECOflex (Eatontown, NJ): Precision-focused manufacturers that serve timing belt and conveyor drive niches can sustain premium positions by emphasizing accuracy, low backlash, and integration for bespoke conveying systems.
- Lovejoy (Timken, Downers Grove, IL): Products that combine elastomeric damping with self-adjustment address vibration-sensitive industrial environments; this composite offering is attractive for buyers prioritizing equipment uptime and reduced bearing failures.
- Dayco (Roseville, MI): Recent product-line expansion and new heavy-duty launches underscore an offensive push into both vehicle-derived industrial markets and severe-duty fleet segments. These moves highlight the ongoing blurring of automotive-grade and industrial-spec components.
- Continental AG (Hanover, Germany) and Bando (Osaka, Japan): Large OEM-oriented suppliers with accessory-drive and auto-tensioning competences. Their investments in precision pulleys and systems-level integration are relevant for manufacturers seeking bundled drive-system solutions.
- SKF (Gothenburg, Sweden): Combines tensioner units with measurement and maintenance tools — an attractive playbook for adding sensor-led aftermarket services and predictive-maintenance offerings.
- B&B Manufacturing (La Porte, IN): ISO-certified customizers and stock producers fill the regional and niche-application gaps, serving buyers that require tailored form-factors or quick-turn replacement parts.
Industry activity through 2025–2026 shows product expansion and trade-show showcases by established players — a signal that incumbents are prioritizing product breadth and aftermarket engagement. For 2026 planning, competitive posture should be evaluated on three axes: product engineering depth, service-led differentiation, and channel reach.
Strategic imperatives for executives in 2026
- Hedge raw-material exposure now. Given large swings in rubber and steel costs, lock in a portion of critical inputs through multi-year agreements with indexation clauses and develop tested alternatives where feasible.
- Prioritize energy-efficient and compliance-ready product variants. EU regulatory updates and buyer procurement preferences make low-energy-loss designs and verified lifecycle-impact claims a commercial differentiator.
- Invest in aftermarket and service monetization. Sensor-enabled tension monitoring, condition-based spare-part programs, and extended-service contracts increase lifetime customer value and buffer cyclical OEM orders.
- Adopt a two-track R&D portfolio: sustain core mechanical reliability while accelerating modular sensor and connectivity options that enable predictive maintenance and remote diagnostics.
- Target bolt-on acquisitions that expand distribution reach or add sensing/software capabilities rather than scale-only acquisitions — the optimal M&A path for 2026 is capability-led.
- Use scenario-based capital allocation. With projected growth but intermittent year-to-year variance, capital should be staged and tied to trigger events in demand or cost trajectories.
How PW Consulting supports execution
PW Consulting’s report is more than a forecast — it is an execution engine. Deliverables include the forecast model, sensitivity workbooks, a supplier-risk playbook, go-to-market templates, and a prioritized implementation roadmap tailored to your business model. For leadership teams preparing 2026 budgets, our model links investment choices to market-share scenarios and NPV outcomes under multiple macro environments.
Because this briefing is intentionally high-level, details that many executive teams consider mission-critical — including full regional and application-level demand tables, split-by-type revenue matrices, and predefined transaction targets — are accessible only through the full report or a consulting engagement.
Next steps and how to engage
For executives and strategy teams preparing budgets, sourcing strategies, or M&A pipelines for 2026, the PW Consulting Industrial Belt Tensioner Market report is designed to convert market intelligence into boardroom-ready decisions. To request the full report, scenario toolkits, or a tailored briefing for your executive committee, contact PW Consulting. Our teams are scheduling interactive workshops to run your 2026 plan through the model and deliver an actionable 6–18 month implementation agenda.
PW Consulting — translating market foresight into strategic advantage for the industrial drive systems value chain.
For detailed analysis of this topic, please visit the official page: Industrial Belt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Electric Tailgate Radar Market to Surge at 8.65% CAGR, New Insights Signal Strong Growth
By pmarketresearch, 2026-07-13
Electric Tailgate Radar Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence—Electric Tailgate Radar Market: Strategic Outlook 2026–2032—equips executives with the practical, decision-grade insights required to convert sensor technology trends into competitive advantage. Anchored on a 2025 base year and a robust compound annual growth rate (CAGR) of 8.65% across the 2026–2032 forecast horizon, our analysis synthesizes market sizing, scenario planning, regulatory impact, and supplier benchmarking to inform product roadmaps, sourcing strategies, and M&A prioritization heading into 2026.
Electric Tailgate Radar Market
Market Trajectory at a Glance
The electric tailgate radar market has evolved from niche convenience electronics into a mainstream component of modern vehicle access systems. Our topline sizing captures this transformation: the market has grown from roughly USD 312.5 million in 2020 to USD 620.5 million in 2025, with a forecast stepping to an estimated USD 683.1 million in 2026 and continuing to expand toward USD 1.11 billion by 2032. These milestones illustrate a transition from early-adoption volumes to a phase where safety integration, regulatory compliance, and multi-sensor fusion are primary growth levers.
Electric Tailgate Radar Market
Why This Matters for 2026 Strategy
- Demand is shifting from optional comfort to embedded safety: Tailgate radar modules are increasingly leveraged for obstacle detection and functional-safety responsibilities—raising the bar on systems engineering, validation, and supplier accountability.
- Frequency and platform choices are strategic: The market’s maturation favors higher-frequency millimeter-wave solutions for superior gesture recognition and interference resilience, requiring upstream alignment with semiconductor roadmaps and standards bodies.
- Time-to-production window is tightening: Semiconductor lead-time improvements and regulatory harmonization are compressing development cycles—creating first-mover advantages for OEMs and Tier-1s that can demonstrate ASIL-compliant integration by mid-2026.
Key Market Dynamics Driving 2026 Decisions
- Regulatory push and harmonization: Updated frequency allocations and certification frameworks (notably UN ECE R10 and national frequency authorities referencing 79 GHz) are shaping technology choices. Compliance is no longer optional—platform-level certification workflows must be designed into 2026 development plans.
- Functional safety expectations: ISO 26262 continues to define the safety envelope for radar-based tailgate obstacle detection. Our analysis indicates radar sub-systems are expected to meet ASIL-B requirements in many OEM applications; this has direct implications for testing, redundancy strategies, and supplier selection.
- Supply-side relief—and new dependencies: Semiconductor supply-chain stabilization has reduced lead times for mmWave radar chips (our industry contacts report a roughly 25% lead-time improvement in Q1 2026 versus prior-year averages). That improvement accelerates program cadence but increases reliance on a smaller pool of qualified mmWave silicon suppliers.
- Technology convergence: Integration of UWB, radar, and camera data—along with embedded ML—changes the value chain. Companies that can offer validated sensor fusion stacks, or that secure priority silicon access, will capture higher-value systems contracts.
What’s Inside the PW Consulting Report (Practical Deliverables)
Our report is designed for operational use. It combines an executive-grade narrative with tools and templates to accelerate 2026 decision-making:
Electric Tailgate Radar Market
- Market sizing and top-down/bottom-up validation with scenario outputs for conservative, base, and aggressive adoption paths through 2032.
- Regulatory impact assessment mapping UN ECE, FCC/ETSI, and ISO 26262 implications to development timelines and cost of validation.
- Comprehensive competitive landscaping and supplier scorecards across sensor, module, and chip tiers—covering technology readiness, production capacity, and quality certifications.
- Commercial playbooks: supplier selection criteria, contract levers, cost-down pathways, and negotiation checklists tuned for 2026 procurement cycles.
- Practical engineering annexes: test protocols for electromagnetic compatibility and interference, ASIL-B verification checklists, and integration templates for RADAR-to-ECU interfaces.
- Executable growth strategies: white-space opportunity identification, partnership frameworks (licensing, JVs), and M&A targets with estimated synergies and payback windows.
- Model deliverables: an interactive financial model (Excel) that lets you stress-test adoption scenarios, component price trajectories, and margin outcomes under alternative supply and regulation assumptions.
Consistent with the “trailer” principle, the report previews strategic conclusions and provides visualization of trends while preserving detailed segmented metrics behind the paywall. This approach ensures you can validate directional strategy quickly while preserving the proprietary analytics that support transactional decision-making.
Competitive Landscape — Core Players & Strategic Positions
The market shows a moderate concentration dynamic, with the top three suppliers accounting for approximately 41.8% of market volumes and the top five approaching 58.6%. This structure creates an environment where Tier-1s and semiconductor suppliers can exert pricing and road-map influence, while smaller specialists continue to compete on integration and bespoke features.
- Huf Group (Velbert, Germany) — Offers compact 79 GHz radar kick sensors designed for hands-free tailgate activation. Huf’s recent series-production wins demonstrate their capability to deliver high-reliability, production-ready modules for OEM programs.
- InnoSenT GmbH (Donnersdorf, Germany) — Specializes in radar-based kick sensors tailored for contactless tailgate opening. Their focus is on automotive-grade robustness and straightforward integration into rear bumper architectures.
- Continental AG (Hanover, Germany) — Provides integrated radar and sensor systems for power tailgates, packaging obstacle detection and activation logic into broader vehicle safety and access modules.
- Brose Fahrzeugteile (Coburg, Germany) — Develops electric tailgate drive systems with integrated sensor interfaces and has showcased UWB-plus-sensor demonstrators at recent trade shows, signaling a systems-first approach.
- Aisin Corporation (Kariya, Japan) — Supplies power tailgate systems for Asian OEMs with integrated radar and proximity sensing, emphasizing platform compatibility for regional vehicle architectures.
- Texas Instruments (Dallas, USA) — A principal mmWave silicon provider; TI’s chipsets underpin many kick-sensor modules and are central to supplier selection and long-lead component commitments.
- Huf Hülsbeck & Fürst GmbH & Co. KG (Velbert, Germany) — Focused on advanced kick sensors and tailgate release systems with emphasis on production-ready designs.
Recent notable industry moves we analyze in the report include Huf’s 2025 series-production order for 79 GHz kick sensors, Brose’s sensor-integration demonstrations at Auto Shanghai, and developments in UWB SoCs from vendors such as Calterah—each signaling differentiated approaches to reliability, integration complexity, and supplier capture strategies.
Strategic Recommendations for 2026
- Prioritize ASIL-aligned architecture early: Design validation and supplier contracts should embed ASIL-B requirements from concept phase to avoid late-stage rework and certification delays.
- Secure silicon access via multi-year commitments: Given the market’s supplier concentration and the strategic role of mmWave chips, OEMs and Tier-1s should consider strategic procurement agreements or equity partnerships to guarantee supply and roadmap alignment.
- Adopt a modular sensor fusion strategy: Invest in a validated sensor-fusion stack that supports radar, UWB, and camera inputs to provide feature differentiation while simplifying integration across platforms.
- Dual-source critical modules: Where safety-critical functions are embedded, dual-sourcing reduces program risk—use our supplier scorecards to identify complementary second sources capable of achieving production ramp timelines.
- Leverage regulatory windows: Use current harmonization efforts on 79 GHz frequencies as an acceleration lever for production programs that can demonstrate compliance ahead of peers.
- Target high-value retrofit and aftersales plays: As the installed-base of vehicles grows, aftermarket modules and authorized retrofit solutions will create incremental revenue pools—consider certified aftermarket paths for validated modules.
How to Use This Intelligence
For 2026 planning cycles, this report acts as both a situational map and an implementation guide. Product teams will find the engineering annexes directly applicable to test-plan development; procurement teams can use the commercial playbooks to renegotiate supplier agreements; corporate development teams can prioritize targets for bolt-on acquisitions that fill capability gaps in sensor fusion or mmWave silicon access.
The Electric Tailgate Radar Market is no longer an accessory play. It has become a strategic intersection of safety, user experience, and platform differentiation. Our research converts that reality into executable choices—while preserving the granular segmentation and supplier-level metrics that are mission-critical when executing transactions or sourcing decisions in 2026.
For the full dataset, interactive forecast model, supplier scorecards, and implementation templates, please visit our report page to access the complete Electric Tailgate Radar Market report and download PW Consulting’s operative toolset.
For detailed analysis of this topic, please visit the official page: Electric Tailgate Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Filter Pump Market to Expand from USD 1,485.2 Million in 2025 to USD 2,182.7 Million by 2032 at a 5.65% CAGR
By pmarketresearch, 2026-07-13
Filter Pump Market — 2026 Strategic Outlook and Action Playbook
Executive summary
As the filter pump sector enters a pivotal phase of consolidation and technology-driven differentiation, PW Consulting’s latest market study frames 2026 as a decision point for executives who must choose between scale, specialization, or platform-led strategies. Our baseline analysis shows the global filter pump market reached roughly USD 1,485 million in 2025 and is projected to pass the USD 1,590 million threshold in 2026, with the forecast period (2026–2032) growing at a compound annual growth rate of 5.65%. Those topline dynamics conceal sharper inflection points beneath the surface — driven by regulatory mandates, rapid adoption of variable-speed and digitally enabled systems, and shifting industrial end‑use requirements — and our report is written to turn these inflections into executable choices for 2026 planning cycles.
Filter Pump Market
Why this report matters for 2026 decisions
-
Timing: 2026 is the first full strategic planning year in which new product portfolios, supply‑chain commitments, and M&A targets must align with post‑regulatory compliance realities and energy‑efficiency expectations.
Filter Pump Market -
Clarity: The market is neither fragmented nor monopolized; concentration metrics indicate leading firms control a meaningful share of value, but there remains room for focused entrants and adjacencies to disrupt with differentiated technology and service models.
Filter Pump Market -
Practicality: Beyond forecasting, our study provides ready‑to‑use playbooks — from commercial pilots to acquisition checklists — so leaders can translate insight into deadlines and budgets rather than leave strategies on a slide.
Market dynamics shaping 2026 strategy
Three convergent vectors are defining near‑term strategy: regulatory pressure on energy consumption, the transition from mechanical to digitally orchestrated systems, and end‑market specialization.
-
Regulatory acceleration: Efficiency standards for dedicated‑purpose pool pumps and related motors have raised the floor for product performance and dealer expectations. Compliance is now table stakes for new product introductions and replacement cycles. Executives must model the operational and margin consequences of these rules in every go‑to‑market scenario.
-
Performance through intelligence: Variable‑speed drives, embedded controls, and system integration are shifting value from pure hydraulic performance to lifecycle energy and service economics. Industry data indicates variable‑speed pool pumps can reduce energy consumption by up to 90% compared with legacy single‑speed models when optimized — a claim that is reshaping buyer evaluation criteria.
-
End‑use divergence: Requirements from industrial wastewater treatment, chemical processing, and aquaculture differ materially from pool and residential channels. Each vertical imposes distinct material, control, and compliance needs, making one‑size‑fits‑all offerings increasingly untenable.
Competitive landscape — what leading players are doing
The market exhibits a moderate degree of concentration. The top three players account for a meaningful portion of total revenues, while the top five collectively constitute a majority — conditions that favor both scalable incumbents and nimble specialists with deep application knowledge.
-
Filter Pump Industries / Finish Thompson (Sun Valley, CA) — Strength lies in corrosion‑resistant chemistries and domestic manufacturing. Their lineage in industrial and corrosive environments positions them well for OEM and aftermarket plays where materials and reliability are decisive purchasing factors.
-
Pentair plc (London, UK) — A clear leader in pool systems with heavy investment in variable‑speed and flow technologies. Recent product recognitions and catalog rollouts underscore a go‑to‑market cadence that blends product innovation with channel marketing momentum.
-
Hayward Industries (Charlotte, NC) — Advances in pump lines and automation integration reflect a strategy to lock in system interoperability and long‑term service revenue through vendor ecosystems.
-
Intex & Bestway — Cost‑tier players that dominate the above‑ground residential segment; important to watch for volume and aftermarket access but less influential in industrial or high‑value commercial channels.
-
Grundfos, Xylem, Parker Hannifin, Donaldson — These engineering‑heavy firms bring scale, controls expertise, and strong distribution relationships into industrial and treatment markets. Their emphasis on energy efficiency, integrated controls, and reliability makes them preferred partners for utilities and industrial end‑users.
Recent corporate moves underline the competitive thrust: product awards and multi‑year catalog updates from major pool pump vendors in early 2026, new variable‑speed product integrations, and earlier strategic acquisitions to shore up corrosion‑resistant capabilities. These signals point to a market where product wins are as much about ecosystem compatibility and energy economics as they are about hydraulic performance.
What PW Consulting’s report delivers (practical, transaction‑ready content)
Our approach is designed for executives who need more than descriptive analysis. The report includes:
-
Proprietary topline market sizing and a 2026–2032 forecasting engine built on scenario modeling and sensitivity analysis to price, energy regulation, and channel shifts.
-
Competitive scorecards with capability matrices (engineering, digital controls, manufacturing footprint, channel strength) and an M&A readiness checklist for acquirers and targets.
-
Go‑to‑market playbooks tailored to three strategic archetypes: Scale & Optimize, Specialized Premium, and Platform & Service. Each playbook contains sample P&L impacts, pilot requirements, and 12–18 month roadmaps.
-
Regulatory impact assessment and compliance timelines calibrated to major jurisdictions, plus a decision tree for product redesign vs. retrofit solutions.
-
Channel and pricing optimization templates, including dealer economics, service margin models, and digital subscription options for performance monitoring.
-
Supply chain and sourcing heuristics that prioritize resilience in critical components (motors, seals, electronics) and quantify near‑term CapEx tradeoffs for regional manufacturing vs. contract manufacturing.
Strategic imperatives for 2026 — an action checklist
-
Prioritize energy and control upgrades: For product roadmaps due in 2026–2027, make variable‑speed capability and smart controls the default specification, not an optional extra. Model payback under conservative usage scenarios.
-
Differentiate through application expertise: Where industrial and chemical markets demand corrosion‑resistant materials, invest in validation protocols and service guarantees that reduce buyer perceived risk.
-
Lock in aftermarket economics: Install base monetization via service contracts, consumables, and performance analytics will be a key margin driver as hardware commoditizes.
-
Use M&A selectively: Look for tuck‑ins that fill capability gaps (controls, corrosion materials, aftermarket distribution) rather than large horizontal deals that dilute focus.
-
Align channel incentives: Rebates and financing solutions for energy‑saving retrofits accelerate replacement cycles. Ensure dealer margins and training programs support premium positioning for smart systems.
-
Stress‑test supply chains: Evaluate dual sourcing for motors and electronics and consider near‑shoring critical assembly to mitigate logistics and tariff risks.
-
Embed compliance into product development: Regulatory timelines should be inputs to R&D prioritization and SKU rationalization to avoid costly redesigns.
Use cases — how executives will apply the study
-
Board and investor briefings that demand credible upside scenarios with quantified sensitivities to energy regulation and adoption curves.
-
New product committees that require validated assumptions for BOM costs, warranty exposure, and route‑to‑market economics.
-
Corporate development teams needing an M&A target shortlist and integration playbooks with financial and operational red flags pre‑scored.
-
Commercial teams optimizing channel segmentation, pricing, and after‑sales program rollouts for 2026 promotional calendars.
Concluding perspective — the choice ahead
The filter pump market in 2026 is a classic strategic bifurcation: companies must choose to consolidate share through scale and distribution or to capture higher‑value niches through engineering and systems integration. Both paths are viable, but each requires different investments in R&D, channels, and compliance infrastructure. Our study is purpose‑built to help leaders choose and operationalize the right path with measurable KPIs, pilot architectures, and deal‑making criteria.
Next steps
PW Consulting’s full report contains the underlying segment tables, granular regional and application forecasts, and vendor scorecards that inform the playbooks summarized here. For teams preparing budgets, M&A pipelines, or product roadmaps for the 2026–2027 window, downloading the complete report will convert this strategic orientation into executable plans with timelines and budgetary frameworks.
For detailed analysis of this topic, please visit the official page: Filter Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com