

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
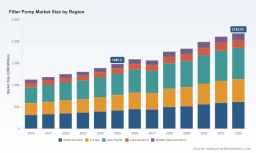
PW Consulting: Filter Pump Market to Expand from USD 1,485.2 Million in 2025 to USD 2,182.7 Million by 2032 at a 5.65% CAGR

Filter Pump Market — 2026 Strategic Outlook and Action Playbook
Executive summary
As the filter pump sector enters a pivotal phase of consolidation and technology-driven differentiation, PW Consulting’s latest market study frames 2026 as a decision point for executives who must choose between scale, specialization, or platform-led strategies. Our baseline analysis shows the global filter pump market reached roughly USD 1,485 million in 2025 and is projected to pass the USD 1,590 million threshold in 2026, with the forecast period (2026–2032) growing at a compound annual growth rate of 5.65%. Those topline dynamics conceal sharper inflection points beneath the surface — driven by regulatory mandates, rapid adoption of variable-speed and digitally enabled systems, and shifting industrial end‑use requirements — and our report is written to turn these inflections into executable choices for 2026 planning cycles.
Filter Pump Market
Why this report matters for 2026 decisions
-
Timing: 2026 is the first full strategic planning year in which new product portfolios, supply‑chain commitments, and M&A targets must align with post‑regulatory compliance realities and energy‑efficiency expectations.
Filter Pump Market -
Clarity: The market is neither fragmented nor monopolized; concentration metrics indicate leading firms control a meaningful share of value, but there remains room for focused entrants and adjacencies to disrupt with differentiated technology and service models.
Filter Pump Market -
Practicality: Beyond forecasting, our study provides ready‑to‑use playbooks — from commercial pilots to acquisition checklists — so leaders can translate insight into deadlines and budgets rather than leave strategies on a slide.
Market dynamics shaping 2026 strategy
Three convergent vectors are defining near‑term strategy: regulatory pressure on energy consumption, the transition from mechanical to digitally orchestrated systems, and end‑market specialization.
-
Regulatory acceleration: Efficiency standards for dedicated‑purpose pool pumps and related motors have raised the floor for product performance and dealer expectations. Compliance is now table stakes for new product introductions and replacement cycles. Executives must model the operational and margin consequences of these rules in every go‑to‑market scenario.
-
Performance through intelligence: Variable‑speed drives, embedded controls, and system integration are shifting value from pure hydraulic performance to lifecycle energy and service economics. Industry data indicates variable‑speed pool pumps can reduce energy consumption by up to 90% compared with legacy single‑speed models when optimized — a claim that is reshaping buyer evaluation criteria.
-
End‑use divergence: Requirements from industrial wastewater treatment, chemical processing, and aquaculture differ materially from pool and residential channels. Each vertical imposes distinct material, control, and compliance needs, making one‑size‑fits‑all offerings increasingly untenable.
Competitive landscape — what leading players are doing
The market exhibits a moderate degree of concentration. The top three players account for a meaningful portion of total revenues, while the top five collectively constitute a majority — conditions that favor both scalable incumbents and nimble specialists with deep application knowledge.
-
Filter Pump Industries / Finish Thompson (Sun Valley, CA) — Strength lies in corrosion‑resistant chemistries and domestic manufacturing. Their lineage in industrial and corrosive environments positions them well for OEM and aftermarket plays where materials and reliability are decisive purchasing factors.
-
Pentair plc (London, UK) — A clear leader in pool systems with heavy investment in variable‑speed and flow technologies. Recent product recognitions and catalog rollouts underscore a go‑to‑market cadence that blends product innovation with channel marketing momentum.
-
Hayward Industries (Charlotte, NC) — Advances in pump lines and automation integration reflect a strategy to lock in system interoperability and long‑term service revenue through vendor ecosystems.
-
Intex & Bestway — Cost‑tier players that dominate the above‑ground residential segment; important to watch for volume and aftermarket access but less influential in industrial or high‑value commercial channels.
-
Grundfos, Xylem, Parker Hannifin, Donaldson — These engineering‑heavy firms bring scale, controls expertise, and strong distribution relationships into industrial and treatment markets. Their emphasis on energy efficiency, integrated controls, and reliability makes them preferred partners for utilities and industrial end‑users.
Recent corporate moves underline the competitive thrust: product awards and multi‑year catalog updates from major pool pump vendors in early 2026, new variable‑speed product integrations, and earlier strategic acquisitions to shore up corrosion‑resistant capabilities. These signals point to a market where product wins are as much about ecosystem compatibility and energy economics as they are about hydraulic performance.
What PW Consulting’s report delivers (practical, transaction‑ready content)
Our approach is designed for executives who need more than descriptive analysis. The report includes:
-
Proprietary topline market sizing and a 2026–2032 forecasting engine built on scenario modeling and sensitivity analysis to price, energy regulation, and channel shifts.
-
Competitive scorecards with capability matrices (engineering, digital controls, manufacturing footprint, channel strength) and an M&A readiness checklist for acquirers and targets.
-
Go‑to‑market playbooks tailored to three strategic archetypes: Scale & Optimize, Specialized Premium, and Platform & Service. Each playbook contains sample P&L impacts, pilot requirements, and 12–18 month roadmaps.
-
Regulatory impact assessment and compliance timelines calibrated to major jurisdictions, plus a decision tree for product redesign vs. retrofit solutions.
-
Channel and pricing optimization templates, including dealer economics, service margin models, and digital subscription options for performance monitoring.
-
Supply chain and sourcing heuristics that prioritize resilience in critical components (motors, seals, electronics) and quantify near‑term CapEx tradeoffs for regional manufacturing vs. contract manufacturing.
Strategic imperatives for 2026 — an action checklist
-
Prioritize energy and control upgrades: For product roadmaps due in 2026–2027, make variable‑speed capability and smart controls the default specification, not an optional extra. Model payback under conservative usage scenarios.
-
Differentiate through application expertise: Where industrial and chemical markets demand corrosion‑resistant materials, invest in validation protocols and service guarantees that reduce buyer perceived risk.
-
Lock in aftermarket economics: Install base monetization via service contracts, consumables, and performance analytics will be a key margin driver as hardware commoditizes.
-
Use M&A selectively: Look for tuck‑ins that fill capability gaps (controls, corrosion materials, aftermarket distribution) rather than large horizontal deals that dilute focus.
-
Align channel incentives: Rebates and financing solutions for energy‑saving retrofits accelerate replacement cycles. Ensure dealer margins and training programs support premium positioning for smart systems.
-
Stress‑test supply chains: Evaluate dual sourcing for motors and electronics and consider near‑shoring critical assembly to mitigate logistics and tariff risks.
-
Embed compliance into product development: Regulatory timelines should be inputs to R&D prioritization and SKU rationalization to avoid costly redesigns.
Use cases — how executives will apply the study
-
Board and investor briefings that demand credible upside scenarios with quantified sensitivities to energy regulation and adoption curves.
-
New product committees that require validated assumptions for BOM costs, warranty exposure, and route‑to‑market economics.
-
Corporate development teams needing an M&A target shortlist and integration playbooks with financial and operational red flags pre‑scored.
-
Commercial teams optimizing channel segmentation, pricing, and after‑sales program rollouts for 2026 promotional calendars.
Concluding perspective — the choice ahead
The filter pump market in 2026 is a classic strategic bifurcation: companies must choose to consolidate share through scale and distribution or to capture higher‑value niches through engineering and systems integration. Both paths are viable, but each requires different investments in R&D, channels, and compliance infrastructure. Our study is purpose‑built to help leaders choose and operationalize the right path with measurable KPIs, pilot architectures, and deal‑making criteria.
Next steps
PW Consulting’s full report contains the underlying segment tables, granular regional and application forecasts, and vendor scorecards that inform the playbooks summarized here. For teams preparing budgets, M&A pipelines, or product roadmaps for the 2026–2027 window, downloading the complete report will convert this strategic orientation into executable plans with timelines and budgetary frameworks.
For detailed analysis of this topic, please visit the official page: Filter Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com