

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Handheld Tester Market Poised to Reach USD 774.25 Million by 2032

Handheld Tester Market 2026: A Strategic Playbook for Executive Decision‑Making
Executive summary
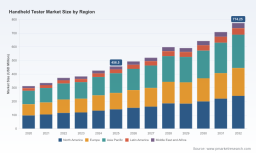
As companies prepare budgets, R&D roadmaps, and channel strategies for 2026, understanding the trajectory of the handheld tester market is essential. PW Consulting’s latest market study shows a market that has expanded meaningfully from its 2020 base and is on track to deliver mid‑single‑digit to high‑single‑digit returns for manufacturers, distributors, and system integrators over the coming seven years. Specifically, the global market grew from the low hundreds of millions of USD in 2020 to approximately USD 456.5 Million in the 2025 base year and is forecast to continue expanding at a compound annual growth rate (CAGR) of 7.85% through 2032, reaching roughly three‑quarters of a billion USD by the end of the forecast window.
Handheld Tester Market
This press release outlines the strategic implications of those macro dynamics for enterprise decision‑makers in 2026: where to allocate R&D and product investment, how to optimize go‑to‑market motions, which competitive moves to anticipate, and what regulatory and end‑market forces will most influence returns. The goal is to present the analytical framing and actionable playbooks found in the full PW Consulting report—while preserving the proprietary, granular detail available exclusively in the full dataset and interactive dashboards.
Handheld Tester Market
Why 2026 is a strategic inflection point
- Scale meets sophistication: The market’s sustained growth to 2025 and the projected CAGR through 2032 indicate both expanding demand and rising product complexity. Buyers are no longer purchasing simple, single‑function tools alone; they seek integrated solutions that reduce carry burden and increase diagnostic throughput in the field.
- Cost of downtime and safety pressure: Multiplying uptime costs across telecom, utilities, manufacturing, and emerging electrified mobility segments raises willingness to pay for higher‑accuracy, certified handhelds and bundled service offerings.
- Regulatory and compliance thresholds: IEC safety standards (including CAT ratings) and jurisdictional certification requirements (such as NRTL approvals under OSHA frameworks) are shaping product specs, procurement cycles, and aftermarket service obligations.
Market dynamics that shape commercial strategy
The market’s growth is driven by a mix of structural and tactical factors. Structural forces include broader electrification trends, accelerated fiber and 5G deployments, and diffusion of distributed generation. Tactical dynamics include suppliers’ product roadmaps, channel economics, and a rising appetite for instruments that converge electrical, network, RF and environmental measurement capabilities.
Handheld Tester Market
- Convergence of capabilities: Expect an expanding share of new offerings to combine traditional electrical measurements with network and RF diagnostics, environmental sensing and enhanced user interfaces (touch, AR‑assisted readouts, cloud connectivity).
- Field instrumentation becomes software‑defined: Firmware flexibility, modular test libraries, and remote calibration/management platforms are shifting value from pure hardware to recurring software and services revenue.
- Safety and certifications as purchase drivers: Compliance to IEC requirements and local certification schemes is a gating factor for enterprise procurement—driving longer lead times but also enabling differentiation for compliant vendors.
- Niche pockets of premiumization: Certain end‑use segments—particularly those with critical uptime or regulatory obligations—are migrating to higher‑end handhelds with built‑in logging, traceable calibration, and secure cloud connectivity.
What the PW Consulting report delivers (practical contents)
The full report is intentionally focused on operational utility for strategic teams. Highlights include:
- Time‑series market sizing and demand modelling calibrated to 2020–2025 tracked data and scenario projections through 2032.
- Channel and buyer segmentation frameworks that map procurement triggers, lead times, and total cost of ownership considerations for enterprise and contractor buyers.
- Product taxonomy and roadmap implications, with prioritized feature sets mapped to buyer willingness‑to‑pay and adoption timelines.
- Competitive positioning matrices and supplier scorecards (product breadth, innovation cadence, channel strength, certification coverage, after‑sales services).
- Go‑to‑market playbooks for suppliers targeting three strategic moves: premiumization and service monetization, low‑cost footprint expansion, and platformization via software ecosystems.
- Regulatory impact analysis that translates standards (IEC, OSHA/NRTL and local rules) into product requirements and compliance cost buckets.
- Deal‑level negotiation guidance and price‑benchmark ranges for enterprise procurement teams (presented as ranges and indexed comparables rather than raw contract figures).
- An interactive data workbook (available to clients) enabling custom slicing by feature set, buyer persona and time horizon—useful for capex planning and M&A screening.
Competitive landscape: strategic takeaways
The handheld tester market blends heritage test instrument vendors with specialized newcomers that are pushing connectivity and RF capability into handheld form factors. The PW Consulting analysis profiles incumbent global manufacturers and targeted challengers, assessing their strengths and strategic postures.
- Established industrial players (e.g., Fluke Corporation): Durable product portfolios, extensive service networks, and deep safety‑certification footprints are their primary defensibility. These firms should prioritize software monetization and retrofit service models to capture aftermarket revenue while protecting margins against low‑cost entrants.
- Specialists in insulation and power test equipment (e.g., Megger Group): Focused expertise in high‑voltage and commissioning tools supports premium positioning for utilities and heavy industry. Strategic play: deepen partnerships with utility OEMs and offer integrated commissioning packages that include handhelds, data logging, and cloud analytics.
- Contractor‑oriented brands (e.g., Klein Tools): Strong channel intimacy with electrician communities and trade distributors is an advantage for penetration at scale. Their path forward lies in expanding modular accessory ecosystems and financing/insurance bundles to make higher‑tier tools accessible.
- RF and 5G‑capable entrants (e.g., Siglent Technologies): Recent product launches integrating spectrum analysis, VNA capabilities, and cable/antenna testing into compact handhelds signal a clear move to capture field technicians supporting 5G rollouts. For incumbents, this is a cue to accelerate cross‑domain feature integration or partner with RF specialists.
- Precision metrology brands (e.g., Hioki): Focus on measurement accuracy and ergonomic design suits safety‑sensitive applications. Strategic emphasis should be on certification breadth, calibration services, and long‑term reliability guarantees.
- Niche and regional specialists (e.g., Seaward, Sonel, Chauvin Arnoux): These players often win on localized product fit, competitive pricing, or specialized use cases (solar PV installation, PAT testing, environmental sensors). Scale advantage can be achieved through selective distribution alliances and shared service infrastructures.
Notably, product innovations such as the compact SHA860A series (announced in April 2025) that integrate spectrum analysis and vector network functions exemplify the convergence trend and underscore the importance of monitoring adjacent technology domains when crafting 2026 plans.
Practical recommendations for corporate leaders (2026 action agenda)
- For product leaders: Prioritize modular architectures that allow software‑led feature activation. Invest in embedded connectivity and secure telemetry to enable SaaS tie‑ins and remote calibration services.
- For commercial leaders: Rebalance channel incentives toward value plays (warranty, calibration subscriptions, training) rather than pure unit discounts. Build OEM and system integrator bundles for priority verticals (telecom rollout, utilities, automotive diagnostics).
- For compliance and quality teams: Bake IEC CAT rating and local certification requirements into product development gates to avoid go‑to‑market delays. Consider third‑party lab partnerships to accelerate approvals in key jurisdictions.
- For M&A and corporate development: Screen targets that add RF/5G capabilities, cloud‑native service platforms, or regional distribution strengths. Use the report’s scenario modelling to quantify revenue synergies under conservative and aggressive adoption cases.
- For procurement: Shift procurement KPIs to lifecycle cost metrics that include calibration, downtime costs, and data management—this will reveal hidden value in higher‑spec instruments and service bundles.
Risk factors and watchlist
- Regulatory shifts: Changes in safety certifications or new national testing requirements could lengthen product certification timelines and increase compliance costs.
- Technology displacement: Rapid adoption of software or cloud substitutes for certain handheld functions (edge diagnostic apps, smartphone sensor modules) could compress margins on commodity products.
- Supply chain volatility: Component scarcity and tariff dynamics can disproportionately affect higher‑spec handhelds that rely on specialized RF or sensor modules.
Concluding perspective and next steps
For executives planning 2026 investments, the handheld tester market presents a clear opportunity: demand is growing and converging toward multifunction, connectivity‑enabled tools, while regulatory and safety imperatives create barriers that reward established, certifying vendors and disciplined challengers. The strategic choices made in 2026—about modular product design, software and services monetization, certification roadmaps, and targeted M&A—will determine which players capture the most attractive portion of market growth.
PW Consulting’s full Handheld Tester Market report provides the granular segmentation, supplier scorecards, pricing models, and interactive scenario tools necessary to translate these high‑level insights into executable plans. To access the complete dataset, benchmark dashboards, and our recommended 12‑ to 36‑month playbooks, please visit the PW Consulting report page or contact our industry practice to arrange a briefing and bespoke modelling session.
For detailed analysis of this topic, please visit the official page: Handheld Tester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com