

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Belt Tensioner Market to Rise from USD 1,609.85 Million in 2025 to USD 2,434.10 Million by 2032 at a 6.08% CAGR

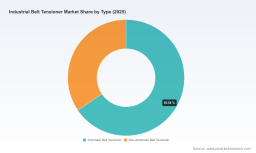
PW Consulting Releases Strategic Brief: Industrial Belt Tensioner Market Outlook 2026 — Actionable Roadmap for Executive Decision-Making
Executive summary
PW Consulting today publishes a strategic briefing drawn from our upcoming Industrial Belt Tensioner Market report (base year 2025; historical window 2020–2025; forecast horizon 2026–2032). The market finished 2025 at approximately USD 1,610 Million and enters the 2026 planning window with momentum consistent with a mid-single-digit compound annual growth trajectory (CAGR 2026–2032: 6.08%). Our forecast model projects the market to re-accelerate over the medium term, reaching a multi-billion dollar scale by the end of the planning horizon. For 2026 specifically, the market path implies near-term demand expansion that will require executives to make targeted product, supply chain, and commercial decisions in Q1–Q2 to capture outsized share.
Industrial Belt Tensioner Market
Why this briefing matters for 2026 strategic choices
- Market timing: With baseline market scale set in 2025 and a 6.08% CAGR baked into our central scenario, 2026 acts as an inflection year where commercial investments and operational shifts begin to compound returns through 2032.
- Cost and supply volatility: Raw-material volatility—particularly in natural rubber and steel—has moved within a wide band in recent years (annual swings of 20–35% have been observed), creating margin pressure and forcing re-engineering of sourcing strategies.
- Regulatory pressure and product differentiation: Updated EU emissions and industrial efficiency standards introduced in 2025 accelerate buyer preference toward energy-efficient and low-emissions drive systems, changing specification criteria for belt tensioners and increasing the importance of lifecycle energy metrics.
- Competitive structure: The market displays moderate concentration among the largest incumbents, producing both risk and opportunity: nimble players can pursue niche specialization, while larger firms can leverage scale to integrate upstream or expand aftermarket service offerings.
What the full report delivers — practical, implementation-ready content
Our report is designed as an executive-to-execution toolkit for 2026 planning. Rather than generic market commentary, clients receive decision-ready assets that translate forecast signals into capital, commercial, and product actions:
Industrial Belt Tensioner Market
- Proprietary forecast model (2026–2032) with scenario toggles for demand elasticity, raw-material price shocks, and regulatory stringency — enabling rapid re-run of ROI on proposed investments.
- Supplier risk matrix and hedging playbook that maps component-level exposures to procurement levers (long-term contracts, multi-source qualification, nearshoring thresholds).
- Pricing-sensitivity and margin-impact simulator to evaluate value-based pricing, indexation clauses, and cost-pass-through strategies under realistic procurement cycles.
- Go-to-market playbooks for OEM, aftermarket, and industrial-distribution channels — including partner economics, inventory policies, and warranty/cost-of-ownership arguments tailored to industrial buyers.
- Product and R&D prioritization framework aligning design choices (e.g., automatic vs. fixed tensioners, sensor-enabled tension monitoring) with targeted customer segments and regulatory requirements.
- M&A and partnership screening filters that identify high-fit targets (sensor suites, aftermarket distributors, regional manufacturing footprints) and produce an integration-value estimate.
- Implementation roadmaps and KPI dashboards to convert strategic choices into board-level deliverables within a 6–18 month window.
To preserve the strategic advantage for clients, the public briefing is intentionally selective: detailed segment-level demand tables, regional and application splits, and deal-by-deal valuation worksheets are reserved for the full report and consulting engagements.
Industrial Belt Tensioner Market
Competitive landscape — positioning and near-term dynamics
The market is served by a mix of global industrials, niche specialists, and regional fabricators. Our competitive analysis highlights how product breadth, engineering depth, aftermarket reach, and service propositions shape strategic options for 2026.
- Gates Corporation (Denver, CO): A broad product portfolio and heavy-duty engineering footprint make Gates a natural scale player in power-transmission systems. Their range enables value capture across OEM and heavy-industrial aftermarket channels; the strategic implication for rivals is to either differentiate on precision/innovation or pursue adjacency through partnerships.
- Fenner Drives (Manheim, PA): Specialization in rotary and linear self-adjusting tensioners positions Fenner to command technical leadership in applications where automated compensation reduces maintenance downtime — a growing procurement criterion for capital-equipment buyers seeking TCO reductions.
- BRECOflex (Eatontown, NJ): Precision-focused manufacturers that serve timing belt and conveyor drive niches can sustain premium positions by emphasizing accuracy, low backlash, and integration for bespoke conveying systems.
- Lovejoy (Timken, Downers Grove, IL): Products that combine elastomeric damping with self-adjustment address vibration-sensitive industrial environments; this composite offering is attractive for buyers prioritizing equipment uptime and reduced bearing failures.
- Dayco (Roseville, MI): Recent product-line expansion and new heavy-duty launches underscore an offensive push into both vehicle-derived industrial markets and severe-duty fleet segments. These moves highlight the ongoing blurring of automotive-grade and industrial-spec components.
- Continental AG (Hanover, Germany) and Bando (Osaka, Japan): Large OEM-oriented suppliers with accessory-drive and auto-tensioning competences. Their investments in precision pulleys and systems-level integration are relevant for manufacturers seeking bundled drive-system solutions.
- SKF (Gothenburg, Sweden): Combines tensioner units with measurement and maintenance tools — an attractive playbook for adding sensor-led aftermarket services and predictive-maintenance offerings.
- B&B Manufacturing (La Porte, IN): ISO-certified customizers and stock producers fill the regional and niche-application gaps, serving buyers that require tailored form-factors or quick-turn replacement parts.
Industry activity through 2025–2026 shows product expansion and trade-show showcases by established players — a signal that incumbents are prioritizing product breadth and aftermarket engagement. For 2026 planning, competitive posture should be evaluated on three axes: product engineering depth, service-led differentiation, and channel reach.
Strategic imperatives for executives in 2026
- Hedge raw-material exposure now. Given large swings in rubber and steel costs, lock in a portion of critical inputs through multi-year agreements with indexation clauses and develop tested alternatives where feasible.
- Prioritize energy-efficient and compliance-ready product variants. EU regulatory updates and buyer procurement preferences make low-energy-loss designs and verified lifecycle-impact claims a commercial differentiator.
- Invest in aftermarket and service monetization. Sensor-enabled tension monitoring, condition-based spare-part programs, and extended-service contracts increase lifetime customer value and buffer cyclical OEM orders.
- Adopt a two-track R&D portfolio: sustain core mechanical reliability while accelerating modular sensor and connectivity options that enable predictive maintenance and remote diagnostics.
- Target bolt-on acquisitions that expand distribution reach or add sensing/software capabilities rather than scale-only acquisitions — the optimal M&A path for 2026 is capability-led.
- Use scenario-based capital allocation. With projected growth but intermittent year-to-year variance, capital should be staged and tied to trigger events in demand or cost trajectories.
How PW Consulting supports execution
PW Consulting’s report is more than a forecast — it is an execution engine. Deliverables include the forecast model, sensitivity workbooks, a supplier-risk playbook, go-to-market templates, and a prioritized implementation roadmap tailored to your business model. For leadership teams preparing 2026 budgets, our model links investment choices to market-share scenarios and NPV outcomes under multiple macro environments.
Because this briefing is intentionally high-level, details that many executive teams consider mission-critical — including full regional and application-level demand tables, split-by-type revenue matrices, and predefined transaction targets — are accessible only through the full report or a consulting engagement.
Next steps and how to engage
For executives and strategy teams preparing budgets, sourcing strategies, or M&A pipelines for 2026, the PW Consulting Industrial Belt Tensioner Market report is designed to convert market intelligence into boardroom-ready decisions. To request the full report, scenario toolkits, or a tailored briefing for your executive committee, contact PW Consulting. Our teams are scheduling interactive workshops to run your 2026 plan through the model and deliver an actionable 6–18 month implementation agenda.
PW Consulting — translating market foresight into strategic advantage for the industrial drive systems value chain.
For detailed analysis of this topic, please visit the official page: Industrial Belt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com