

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Marine Engineering Hydraulic Piling Hammer Market to Expand at 5.3% CAGR, Forecast to Reach USD 257M by 2032 as Asia‑Pacific Leads with USD 82.6M

Marine Engineering Hydraulic Piling Hammer Market — Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present an executive briefing drawn from our latest Marine Engineering Hydraulic Piling Hammer Market study. The research consolidates five years of historical performance (2020–2025) and delivers an actionable forecast through 2032. This briefing highlights the strategic implications that matter for 2026 capital planning, procurement, and technology road‑mapping — while reserving the full, granular segmentation and vendor scorecards for the report itself.
Marine Engineering Hydraulic Piling Hammer Market
Executive snapshot
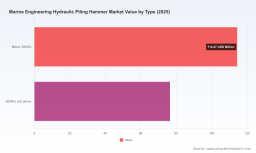
- Market scale: The global market for hydraulic piling hammers reached approximately USD 191.0 Million in the base year (2025).
- Growth trajectory: Our forecast anticipates a compound annual growth rate (CAGR) of about 5.3% over the 2026–2032 horizon, with the market trending toward the upper‑end of the USD 200–260 Million range by the end of the period under standard scenarios.
- Demand drivers: Rapid offshore wind capacity additions, sizeable port and coastal infrastructure programs, and renewed bridge/harbour investment cycles are the dominant structural drivers shaping purchase patterns and fleet composition.
Why this report matters for 2026 decisions
2026 will be a pivotal year for firms managing heavy marine foundation works. Developers, EPC contractors, port authorities, and equipment lessors face a converging set of pressures: larger monopile sizes, stricter underwater‑noise regulation, constrained supply chains for specialized steel and hydraulic systems, and the economics of owning versus renting high‑value units. Our study translates market-level dynamics into concrete decision levers for procurement, operations, and R&D investment so organizations can avoid cost overruns and secure project timelines.
Marine Engineering Hydraulic Piling Hammer Market
Market outlook — what to expect in 2026 and beyond
The mid‑decade profile is one of steady expansion rather than explosive growth. With a 5.3% CAGR baked into our forecast, the market is large enough to support multiple global OEMs and rental providers, while still encouraging differentiation through technology, service and niche specialization.
Marine Engineering Hydraulic Piling Hammer Market
- Scale and timing: Projected yearly market flows support a predictable cadence of new unit deliveries and aftermarket support contracts. That predictability helps procurement teams align CAPEX and rental strategies to avoid both under‑capacity and over‑investment.
- Price and input pressures: High‑capacity hammer systems are capital‑intensive. Specialized materials and hydraulics mean individual units carry multi‑million dollar capital price tags; this remains a primary source of cost volatility and a lever for negotiating long‑lead supplier agreements.
- Regulatory drag: Stringent underwater noise mitigation regimes in sensitive habitats are not marginal — they typically add measurable schedule and cost increments to piling campaigns. Our field synthesis indicates mitigation measures can extend timelines and reshape operational windows, necessitating earlier engagement between engineering, environmental and procurement teams.
Strategic implications for 2026 planning
Below are focused actions that should be considered immediately by organizations that commission or deliver marine foundation works:
- Adopt a hybrid ownership model. Given capital intensity and sporadic project pipelines, a mix of owned and rented hammers reduces balance‑sheet exposure while preserving rapid deployment capability for peak periods.
- Integrate noise mitigation into early tendering. Plan for mitigation systems (e.g., bubble curtains, attenuation arrays) and schedule buffers at RFP stage: otherwise bids will be non‑competitive or project timelines will slip.
- Lock long‑lead supplier agreements. Early framework agreements with steel fabricators, hydraulic component vendors and OEMs yield price stability and delivery predictability in 2026–2027 windows.
- Prioritize modularity and retrofitability. Choose systems with upgrade paths for control electronics, hammer energy envelopes and noise‑reduction add‑ons to extend service life as monopile dimensions and regulatory standards evolve.
- Build scenario financial models. Use scenario analyses (base, upside, policy/constraint) to stress test fleet sizing and rental needs over 3–5 year horizons — our report includes templated cashflow and TCO models to accelerate that work.
Competitive landscape — who matters and why
The hammer market is concentrated around a set of globally capable OEMs and a growing tier of regional suppliers. This creates a competitive dynamic where technological leadership, service networks and track record of large‑monopile performance determine tender outcomes more than price alone.
- MENCK GmbH (Acteon) (Kaltenkirchen, Germany) — A benchmark name in high‑capacity, double‑acting hydraulic impact hammers. Their product portfolio targets monopiles and deepwater foundations and benefits from significant reference exposure in large offshore wind programs. MENCK’s recent control‑system upgrades reflect a maturation toward integrated automation and drive efficiency gains in monopile installation campaigns. (See: https://www.acteon.com)
- IQIP (Sliedrecht, Netherlands) — Known for the Hydrohammer S‑series and IQ‑series, IQIP continues to push capacity boundaries, including water‑driven variants engineered for ultra‑deep applications. A notable 2025 product introduction signals IQIP’s intent to capture next‑generation monopile works by offering high‑capacity, digitally controlled systems. (See: https://iqip.com)
- BRUCE Piling Equipment (Siheung, South Korea) — Focused on energy‑efficient designs compatible with crane‑suspended and leader‑mounted operations, Bruce’s equipment appeals to port and bridge contractors where versatility and on‑site adaptability are decisive.
- Junttan Oy (Kuopio, Finland) — A specialist in leader‑mounted hammers with a strong footprint in marine terminal and coastal projects. Junttan’s emphasis on noise and vibration reduction aligns with regulatory trends and community acceptance considerations. (See: https://junttan.com)
- Chinese OEMs and research institutes — A cohort of manufacturers and research bodies has rapidly matured domestic capabilities, deploying very large single‑acting systems in regional offshore wind programs and advancing noise reduction features. These players are shaping competitive pricing and local supply dynamics.
Collectively, top OEMs control a substantial portion of high‑capacity project awards, though opportunities remain for niche innovators and service‑oriented competitors who can demonstrate compliance, uptime and integrated noise solutions.
Technology and operational priorities
The next wave of differentiation will be technical and operational rather than purely mechanical. Our fieldwork and supplier interviews identify three priority vectors:
- Control systems and automation — higher precision energy delivery and digital monitoring reduce re‑drives and improve pile integrity outcomes.
- Acoustic mitigation integration — OEMs that can supply hammer‑level noise attenuation packages or seamless third‑party integration will win tenders in noise‑sensitive jurisdictions.
- Service and logistics networks — proven global service footprints and rapid parts delivery are decisive for contractors operating on tight installation windows.
Report contents — what you will find inside
The PW Consulting report is structured as a tactical playbook for 2026. Highlights include:
- Market sizing and forward scenarios with discrete CAPEX/OPEX modeling templates for purchase vs rental decisions.
- Vendor benchmarking and procurement scorecards focusing on technical fit, lifecycle cost, delivery lead time and noise‑mitigation capability.
- Project playbooks for offshore wind and port/bridge works covering logistics, scheduling buffers driven by noise mitigation, and contractor/OEM coordination checklists.
- Supply‑chain risk maps with mitigation strategies for critical inputs (steel, high‑pressure hydraulics) and recommended contracting approaches for price and delivery protection.
- Regulatory impact assessments showing how operational windows and mitigation measures affect schedule and cost across representative project archetypes.
Practical next steps for 2026
- Commission a rapid portfolio review: align current fleet capabilities to 2026 pipeline and identify capability gaps where rental or partnership is prudent.
- Engage OEMs early on noise‑mitigation and delivery milestones to lock windows and accelerate permitting.
- Run a pilot retrofit for noise reduction on at least one unit to validate CAPEX payback and operational impacts before wider roll‑out.
- Adopt the report’s procurement scorecard for upcoming RFPs to standardise evaluation across technical, commercial and environmental dimensions.
Conclusion — the strategic payoff
For organizations that move decisively in 2026, the payoff is twofold: fewer schedule and compliance surprises, and materially better unit‑economics across your pile‑driving fleet. The market’s steady growth and technological evolution reward those who combine disciplined procurement, early noise‑mitigation planning, and vendor alliances that guarantee upgrades and service. PW Consulting’s full report packages the analytics, templates and vendor intelligence required to convert the market’s growth into project success — while protecting margins and reputations in noise‑sensitive environments.
To access the complete dataset, vendor scorecards, and bespoke modelling tools referenced here, please consult the PW Consulting Marine Engineering Hydraulic Piling Hammer Market report webpage — where the full, actionable intelligence is available to support your 2026 strategy and tender teams.
For detailed analysis of this topic, please visit the official page: Marine Engineering Hydraulic Piling Hammer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com