

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Electric Tailgate Radar Market to Surge at 8.65% CAGR, New Insights Signal Strong Growth

Electric Tailgate Radar Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence—Electric Tailgate Radar Market: Strategic Outlook 2026–2032—equips executives with the practical, decision-grade insights required to convert sensor technology trends into competitive advantage. Anchored on a 2025 base year and a robust compound annual growth rate (CAGR) of 8.65% across the 2026–2032 forecast horizon, our analysis synthesizes market sizing, scenario planning, regulatory impact, and supplier benchmarking to inform product roadmaps, sourcing strategies, and M&A prioritization heading into 2026.
Electric Tailgate Radar Market
Market Trajectory at a Glance
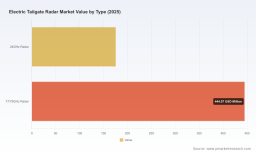
The electric tailgate radar market has evolved from niche convenience electronics into a mainstream component of modern vehicle access systems. Our topline sizing captures this transformation: the market has grown from roughly USD 312.5 million in 2020 to USD 620.5 million in 2025, with a forecast stepping to an estimated USD 683.1 million in 2026 and continuing to expand toward USD 1.11 billion by 2032. These milestones illustrate a transition from early-adoption volumes to a phase where safety integration, regulatory compliance, and multi-sensor fusion are primary growth levers.
Electric Tailgate Radar Market
Why This Matters for 2026 Strategy
- Demand is shifting from optional comfort to embedded safety: Tailgate radar modules are increasingly leveraged for obstacle detection and functional-safety responsibilities—raising the bar on systems engineering, validation, and supplier accountability.
- Frequency and platform choices are strategic: The market’s maturation favors higher-frequency millimeter-wave solutions for superior gesture recognition and interference resilience, requiring upstream alignment with semiconductor roadmaps and standards bodies.
- Time-to-production window is tightening: Semiconductor lead-time improvements and regulatory harmonization are compressing development cycles—creating first-mover advantages for OEMs and Tier-1s that can demonstrate ASIL-compliant integration by mid-2026.
Key Market Dynamics Driving 2026 Decisions
- Regulatory push and harmonization: Updated frequency allocations and certification frameworks (notably UN ECE R10 and national frequency authorities referencing 79 GHz) are shaping technology choices. Compliance is no longer optional—platform-level certification workflows must be designed into 2026 development plans.
- Functional safety expectations: ISO 26262 continues to define the safety envelope for radar-based tailgate obstacle detection. Our analysis indicates radar sub-systems are expected to meet ASIL-B requirements in many OEM applications; this has direct implications for testing, redundancy strategies, and supplier selection.
- Supply-side relief—and new dependencies: Semiconductor supply-chain stabilization has reduced lead times for mmWave radar chips (our industry contacts report a roughly 25% lead-time improvement in Q1 2026 versus prior-year averages). That improvement accelerates program cadence but increases reliance on a smaller pool of qualified mmWave silicon suppliers.
- Technology convergence: Integration of UWB, radar, and camera data—along with embedded ML—changes the value chain. Companies that can offer validated sensor fusion stacks, or that secure priority silicon access, will capture higher-value systems contracts.
What’s Inside the PW Consulting Report (Practical Deliverables)
Our report is designed for operational use. It combines an executive-grade narrative with tools and templates to accelerate 2026 decision-making:
Electric Tailgate Radar Market
- Market sizing and top-down/bottom-up validation with scenario outputs for conservative, base, and aggressive adoption paths through 2032.
- Regulatory impact assessment mapping UN ECE, FCC/ETSI, and ISO 26262 implications to development timelines and cost of validation.
- Comprehensive competitive landscaping and supplier scorecards across sensor, module, and chip tiers—covering technology readiness, production capacity, and quality certifications.
- Commercial playbooks: supplier selection criteria, contract levers, cost-down pathways, and negotiation checklists tuned for 2026 procurement cycles.
- Practical engineering annexes: test protocols for electromagnetic compatibility and interference, ASIL-B verification checklists, and integration templates for RADAR-to-ECU interfaces.
- Executable growth strategies: white-space opportunity identification, partnership frameworks (licensing, JVs), and M&A targets with estimated synergies and payback windows.
- Model deliverables: an interactive financial model (Excel) that lets you stress-test adoption scenarios, component price trajectories, and margin outcomes under alternative supply and regulation assumptions.
Consistent with the “trailer” principle, the report previews strategic conclusions and provides visualization of trends while preserving detailed segmented metrics behind the paywall. This approach ensures you can validate directional strategy quickly while preserving the proprietary analytics that support transactional decision-making.
Competitive Landscape — Core Players & Strategic Positions
The market shows a moderate concentration dynamic, with the top three suppliers accounting for approximately 41.8% of market volumes and the top five approaching 58.6%. This structure creates an environment where Tier-1s and semiconductor suppliers can exert pricing and road-map influence, while smaller specialists continue to compete on integration and bespoke features.
- Huf Group (Velbert, Germany) — Offers compact 79 GHz radar kick sensors designed for hands-free tailgate activation. Huf’s recent series-production wins demonstrate their capability to deliver high-reliability, production-ready modules for OEM programs.
- InnoSenT GmbH (Donnersdorf, Germany) — Specializes in radar-based kick sensors tailored for contactless tailgate opening. Their focus is on automotive-grade robustness and straightforward integration into rear bumper architectures.
- Continental AG (Hanover, Germany) — Provides integrated radar and sensor systems for power tailgates, packaging obstacle detection and activation logic into broader vehicle safety and access modules.
- Brose Fahrzeugteile (Coburg, Germany) — Develops electric tailgate drive systems with integrated sensor interfaces and has showcased UWB-plus-sensor demonstrators at recent trade shows, signaling a systems-first approach.
- Aisin Corporation (Kariya, Japan) — Supplies power tailgate systems for Asian OEMs with integrated radar and proximity sensing, emphasizing platform compatibility for regional vehicle architectures.
- Texas Instruments (Dallas, USA) — A principal mmWave silicon provider; TI’s chipsets underpin many kick-sensor modules and are central to supplier selection and long-lead component commitments.
- Huf Hülsbeck & Fürst GmbH & Co. KG (Velbert, Germany) — Focused on advanced kick sensors and tailgate release systems with emphasis on production-ready designs.
Recent notable industry moves we analyze in the report include Huf’s 2025 series-production order for 79 GHz kick sensors, Brose’s sensor-integration demonstrations at Auto Shanghai, and developments in UWB SoCs from vendors such as Calterah—each signaling differentiated approaches to reliability, integration complexity, and supplier capture strategies.
Strategic Recommendations for 2026
- Prioritize ASIL-aligned architecture early: Design validation and supplier contracts should embed ASIL-B requirements from concept phase to avoid late-stage rework and certification delays.
- Secure silicon access via multi-year commitments: Given the market’s supplier concentration and the strategic role of mmWave chips, OEMs and Tier-1s should consider strategic procurement agreements or equity partnerships to guarantee supply and roadmap alignment.
- Adopt a modular sensor fusion strategy: Invest in a validated sensor-fusion stack that supports radar, UWB, and camera inputs to provide feature differentiation while simplifying integration across platforms.
- Dual-source critical modules: Where safety-critical functions are embedded, dual-sourcing reduces program risk—use our supplier scorecards to identify complementary second sources capable of achieving production ramp timelines.
- Leverage regulatory windows: Use current harmonization efforts on 79 GHz frequencies as an acceleration lever for production programs that can demonstrate compliance ahead of peers.
- Target high-value retrofit and aftersales plays: As the installed-base of vehicles grows, aftermarket modules and authorized retrofit solutions will create incremental revenue pools—consider certified aftermarket paths for validated modules.
How to Use This Intelligence
For 2026 planning cycles, this report acts as both a situational map and an implementation guide. Product teams will find the engineering annexes directly applicable to test-plan development; procurement teams can use the commercial playbooks to renegotiate supplier agreements; corporate development teams can prioritize targets for bolt-on acquisitions that fill capability gaps in sensor fusion or mmWave silicon access.
The Electric Tailgate Radar Market is no longer an accessory play. It has become a strategic intersection of safety, user experience, and platform differentiation. Our research converts that reality into executable choices—while preserving the granular segmentation and supplier-level metrics that are mission-critical when executing transactions or sourcing decisions in 2026.
For the full dataset, interactive forecast model, supplier scorecards, and implementation templates, please visit our report page to access the complete Electric Tailgate Radar Market report and download PW Consulting’s operative toolset.
For detailed analysis of this topic, please visit the official page: Electric Tailgate Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com