

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: External Tooth Slewing Bearing Market Poised to Reach USD 3,873.1 Million by 2032 on a 6.85% CAGR

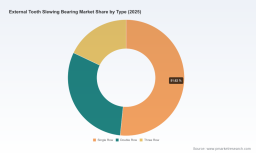
External Tooth Slewing Bearing Market: Strategic Intelligence for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a distilled, actionable orientation for executives shaping their 2026 plans in the external tooth slewing bearing ecosystem. Our new market research—anchored on a 2025 base year and a 2026–2032 forecast horizon—combines rigorous market-sizing, competitive diagnostics, and operable playbooks. This briefing highlights the strategic value of the report for corporate leaders while preserving the “trailer” principle: we demonstrate analytical depth and direction without disclosing the proprietary segment-level figures that differentiate the full report.
External Tooth Slewing Bearing Market
Executive snapshot: market scale, trajectory, and concentration
Key macro facts every boardroom should internalize. The external tooth slewing bearing market reached roughly USD 2,435.8 Million in 2025 (base year). Our modeling forecasts a compound annual growth rate (CAGR) of 6.85% over the 2026–2032 period, taking the market toward an estimated USD 3,873.1 Million by 2032. These headline dynamics reflect structural demand across heavy construction, renewables, and industrial modernization.
External Tooth Slewing Bearing Market
Market concentration is meaningful but not prohibitive: the top three players command close to 42.5% of the market, while the top five together approach 58.3%. That mix creates a landscape of dominant, global incumbents alongside a broad field of regional and specialist suppliers—an environment that rewards scale, engineering differentiation, and supply chain agility.
External Tooth Slewing Bearing Market
Why this market matters in 2026
-
Capital projects restarting after multi‑year uncertainty are lifting demand for heavy‑duty slewing rings. The combined effects of infrastructure stimulus in some geographies and ongoing wind‑power installations underpin multi‑year order pipelines.
-
Wind energy OEMs and tower suppliers continue to prioritize large‑diameter, externally geared slewing bearings with tight tolerances and proven fatigue life—creating a premium segment that favors manufacturers with extensive metallurgical and heat‑treatment expertise.
-
Raw material dynamics matter: high‑chromium alloy steels (e.g., 42CrMo4) remain the dominant metallurgy for these components, and steel accounts for an outsized share of production materials. Price volatility and environmental regulation are direct cost and compliance levers that will shape supplier margins and capital needs through 2026.
-
Aftermarket and replacement demand (including third‑party replacements) is a persistent revenue pool that smart OEMs and independent manufacturers monetize via service agreements, certifiable replacements, and logistics optimization.
What our report delivers — practical, transaction‑ready intelligence
Decision‑makers require more than directional insight. The full PW Consulting report provides operationally actionable content designed to support investment, procurement, and go‑to‑market decisions:
-
Validated market sizing and a probabilistic forecast model (2026–2032) with scenario toggles for commodity shocks, demand acceleration, and regulatory tightening.
-
Competitive benchmarking of global manufacturers by capability (e.g., large‑diameter manufacturing, external gear machining, heat treatment, aftermarket services) and go‑to‑market tactics.
-
Supply chain risk maps and mitigation playbooks—covering raw material exposures, supplier single‑sourcing, and logistics flex options.
-
M&A and JV heatmaps identifying targets whose assets (tooling, proprietary heat treatment, distribution networks) deliver immediate scale or technical synergies.
-
Commercial levers and pricing frameworks—including value‑based pricing templates for ruggedized, high‑precision slewing bearings and service bundles.
-
Capex and footprint optimization models to inform localization, nearshoring, or consolidation decisions.
Competitive landscape: players, positioning, and tactical implications
The industry blends long‑established engineering leaders with nimble, specialized manufacturers. Our report profiles—and models the competitive behavior of—companies that define the sector:
-
SKF (Gothenburg, Sweden): A global engineering system supplier with both standard and bespoke external‑tooth slewing bearings, SKF differentiates through scale, broad aftermarket channels, and the ability to supply very large diameters for heavy applications. For competitors, SKF’s strength lies in integrated supply and service propositions; for OEMs, it offers a de‑risked single‑vendor option for large programs.
-
thyssenkrupp rothe erde (Lippstadt, Germany): A segment leader in very large‑diameter slewing rings, thyssenkrupp leverages deep materials and manufacturing know‑how. Its strategic play is in engineering customization and long‑cycle, high‑value projects (e.g., turbine foundations, large cranes), creating a high barrier for entrants in these niches.
-
Kaydon Bearings (SKF Group) (Muskegon, USA): Focused on precision slewing rings with proven external gear series, Kaydon’s strengths are precision engineering and niche OEM relationships—especially where rotational accuracy and tight clearances are imperative.
-
Chinese manufacturers and specialists (e.g., Fenghe, XZWD, Tedin, SlewMaster): These suppliers combine cost competitiveness, rapid customization, and aftermarket agility. Many compete successfully on replacement parts and heavy machinery retrofit markets. Their volume play creates pricing pressure but also expands addressable demand by lowering total installed‑cost thresholds for some OEMs.
-
RIMA S.p.A. and similar European specialists : They focus on four‑point contact designs and geared solutions for lifting and earthmoving equipment, prioritizing engineering sophistication and compliance with European standards.
Strategic implication: incumbents with scale and advanced metallurgy will continue to win large, complex programs; small and mid‑sized players will capture aftermarket, retrofit, and cost‑sensitive OEM segments. For participants, the pathway to premium margins runs through engineering IP, integrated service offers, and validated quality systems.
Supply chain realities and material policy
Material inputs are the single most important cost and technical determinant in 2026. Two facts are essential for procurement and operations leaders:
-
High‑chromium alloy steels (notably grades such as 42CrMo4) remain the production mainstay, and steel comprises roughly 88.6% of the material mix for slewing ring bearings as of 2025. Any procurement strategy must therefore treat steel price volatility and availability as strategic risks.
-
Tightening environmental regulations are already pushing manufacturers to optimize heat‑treatment processes and to integrate higher recycled‑steel content into production—changes that affect both CAPEX (new furnaces, process controls) and OPEX (energy, cycle time). Early movers can convert compliance into a competitive advantage through validated, lower‑CO2 product lines.
Recommended operational moves include multi‑tiered supplier contracts with price collars, strategic inventory buffers keyed to lead‑time variability, supplier development programs for secondary material qualification, and investments in process automation to tighten quality and reduce scrap rates.
Top strategic actions for 2026 (prioritized)
-
Reposition product portfolio: Segment offerings into premium engineered solutions (large diameter, tight‑tolerance external gear) and cost‑optimized lines for replacement and mid‑market OEMs. Align go‑to‑market teams accordingly.
-
Hedge raw material exposure: Implement financial and physical hedges for key steel inputs, and qualify recycled‑content supply streams to anticipate regulatory shifts.
-
Invest in metallurgy and heat treatment: Capex directed to process control and metallurgy pays back through improved fatigue life and lower warranty costs—factors that materially improve tender success on high‑value projects.
-
Monetize aftermarket: Build certified replacement programs and service agreements; use digital condition monitoring to move from reactive replacement to predictive maintenance offerings.
-
Pursue targeted M&A: Acquire capabilities that shorten time to market (bearing machining, gear hobbing, heat treatment) or open new distribution corridors; prioritize bolt‑on targets that improve CR3/CR5 position in desired geographies.
-
Compliance and sustainability: Publish product lifecycle emissions and align with customer decarbonization timelines—this reduces procurement friction with large infrastructure and renewables customers.
Why PW Consulting’s report is the decisive tool for 2026 decisions
Boards and executive teams need more than intuition in 2026; they need reproducible, auditable decision tools. Our report combines proprietary demand‑mapping, supplier scoring, and sensitivity models with industry‑validated assumptions—built from trade show intelligence (e.g., The Bearing Show North America, Zhengzhou Exhibition, 2026) and primary interviews with OEMs and bearings manufacturers.
Included in the full deliverable are deployment‑ready artifacts: a dynamic forecasting workbook, supplier risk dashboards, a 36‑month commercialization timeline template, and an M&A valuation sleeve that converts technical synergies into cash‑flow impacts. These are the assets that enable procurement teams, CFOs, and business unit leaders to convert market insight into execution plans without ambiguity.
Closing: the strategic inflection in 2026
The external tooth slewing bearing market is at an inflection where technical differentiation, supply chain resilience, and sustainability credentials determine which players capture the fastest growth and the highest margins. With a 6.85% CAGR projected through 2032 and a market value approaching USD 3.87 billion by the end of the forecast horizon, this domain is sufficiently large to sustain competing business models—provided those models are tightly aligned to material realities and customer total cost of ownership.
PW Consulting’s full report translates these macro realities into executable plans. For teams preparing budgets, negotiating supplier contracts, or evaluating M&A in 2026, the granular scenario analyses and step‑by‑step playbooks in the full study are purpose‑built to reduce downside and accelerate capture. To access the comprehensive dataset, proprietary segmentation, and transaction‑ready templates, please visit the PW Consulting report page for External Tooth Slewing Bearing Market (full report access required).
For detailed analysis of this topic, please visit the official page: External Tooth Slewing Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com