

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Facial Recognition Payment Devices Market to Grow at 19.85% CAGR During 2026–2032

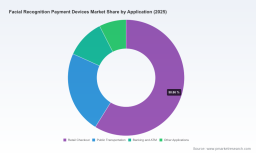
Facial Recognition Payment Devices Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market research on Facial Recognition Payment Devices synthesizes seven years of historical performance with a seven‑year forward outlook to arm boards, payment architects, and deployment teams with the intelligence required to make confident decisions in 2026. The market for facial recognition payment devices has transitioned from niche pilots to measurable commercial traction: total industry revenue rose from USD 7.85 Million in 2020 to USD 20.1 Million in our 2025 base year, and our financial model projects expansion to USD 73.25 Million by 2032 at a compound annual growth rate (CAGR) of 19.85% across the 2026–2032 forecast window. This brief unpacks the report’s strategic value while deliberately withholding deep sub‑segment breakouts to guide practitioners toward the full study for procurement‑grade detail.
Facial Recognition Payment Devices Market
Why this market matters to enterprise decision‑makers in 2026
-
From pilot to program: In many industries — from retail to transport, hospitality to quick‑serve restaurants — facial recognition moved from proof‑of‑concepts to operational pilots between 2020 and 2025. Our dataset captures that transition and quantifies the pace at which vendors, integrators, and operators are converting pilots into revenue‑generating deployments.
Facial Recognition Payment Devices Market -
Structural growth with practical inflection points: The double‑digit CAGR projected into the early 2030s reflects not just vendor hype but concrete drivers — improved 3D sensing hardware, software maturity in biometrics, POS platform integrations, and institutional acceptance. For 2026 planning cycles this translates to timing decisions: when to pilot, when to scale pilots, and when to move from vendor selection to long‑term partnership agreements.
Facial Recognition Payment Devices Market -
Consolidation and concentration: The market exhibits a mid‑level concentration: the top three vendors account for a significant share but are far from monopolistic, and the top five consolidate over half of industry revenue. That profile creates competitive supplier dynamics favourable to large buyers seeking strategic leverage while demanding rigorous vendor risk management.
What our report delivers — practical, decision‑ready content
PW Consulting’s report is designed as a playbook, not simply an academic exercise. The deliverables are structured to support procurement cycles, technology roadmaps, and compliance workstreams across 2026 implementations:
-
Market sizing and validated demand scenarios — multiple, auditable demand curves that map to enterprise adoption triggers and macroeconomic sensitivity. These scenarios enable CFOs and strategy leads to stress‑test investment cases under conservative, baseline, and accelerated adoption paths.
-
Vendor evaluation frameworks — comparative scorecards covering technology maturity, hardware‑software integration, certification and auditability, privacy‑by‑design, commercial terms, and service delivery capabilities. The framework converts qualitative vendor claims into quantifiable procurement metrics.
-
Deployment and operations playbooks — step‑by‑step templates for pilot design, biometric accuracy validation, enrollment UX, edge vs cloud processing tradeoffs, on‑premises vs managed service TCO, and long‑term maintenance scheduling. These are field‑tested by PW Consulting across multiple retail and transport pilots.
-
Regulatory and privacy checklists — jurisdictional decision trees that map legal obligations to design choices, including consent flows, data retention policies, and breach response plans. The checklists are pragmatically aligned with the latest regulatory developments to reduce legal friction during rollouts.
-
Risk and ethics scorecard — an operationally focused tool to quantify and track reputational, regulatory, and algorithmic fairness risks tied to deployments. The scorecard is built to be embedded in vendor SLAs and enterprise governance frameworks.
-
Integration and ecosystem guidance — reference architectures, API patterns, and partner profiles that reduce time‑to‑integration with POS platforms, payment processors, and loyalty systems.
Competitive landscape — who matters and why
The vendor landscape spans hardware specialists, POS OEMs, pure‑play algorithm developers, and system integrators. PW Consulting’s competitive review synthesizes product roadmaps, distribution channels, and strategic partnerships to identify where to source core capabilities and where to expect third‑party consolidation activity.
-
Newland NPT (Fuzhou, China) — a POS OEM that pairs payments engineering with facial capabilities, positioned to serve retail and unattended environments. Its strength lies in scale of terminal distribution and field service reach for multi‑site rollouts.
-
Telpo (Guangdong, China) — notable for depth‑camera and 3D sensing integration in its C‑series payment terminals. Telpo’s value proposition is focused on financial‑grade authentication and self‑checkout use cases that require liveness detection.
-
PAX Technology (Shenzhen, China) — a global Android POS platform player expanding into multimodal biometrics through partnerships. PAX’s momentum underscores an important route to market: platform‑enabled integrations that accelerate merchant adoption.
-
NEC Corporation (Tokyo, Japan) — a systems integrator and algorithm leader, demonstrating high‑profile hands‑free experiences at financial events and large exhibitions. NEC illustrates the value of combining enterprise‑grade algorithms with payments ecosystems (e.g., demonstrated integrations with Stripe Terminal).
-
VisionLabs (Amsterdam), PopID (Pasadena), PayByFace B.V., Intema, Orbbec — a mix of algorithm suppliers, payments‑centric startups, and sensor module vendors. These companies collectively supply critical software IP, UX design, and sensing components that enable differentiated merchant experiences.
Recent industry moves give practical signals for procurement timing: NEC’s demonstrations of integrated, hands‑free checkout and its in‑field deployments at major venues indicate enterprise readiness for contactless retailing; PAX’s partnership activity shows POS vendors are accelerating multimodal biometric roadmaps. Buyers evaluating pilots in 2026 should expect increasing interoperability between POS platforms and biometric providers — and should insist on measurable metrics for accuracy, false acceptance/rejection rates, and liveness performance as contractual gates.
Regulatory landscape and operational risk — realities for 2026
Regulation is the single most important external variable influencing adoption timelines. Two regulatory developments are particularly consequential for 2026 planning:
-
China’s Security Management Measures for Facial Recognition Technology (effective June 1, 2025) — these measures require justification of necessity, restrict mandatory use where alternatives exist, and introduce registration thresholds for large‑scale processing. Enterprises operating in or sourcing from China must factor new compliance controls into vendor assessments and procurement contracts.
-
The EU AI Act (high‑risk obligations effective from August 2025) — biometric systems used in identification and payments are subject to risk assessments, documentation, and prohibitions on certain uses (for example emotion‑scoring). The Act increases the compliance burden for deployments in the EU and for vendors who sell into EU markets.
Our report converts these legal texts into operational requirements: consent and data mapping templates, registry triggers, developer documentation obligations, and audit plans that buyers can insert into RFPs to ensure regulatory traceability from procurement through decommissioning.
Practical recommendations for enterprise leaders in 2026
-
Adopt an evidence‑based pilot approach: start with operational environments that minimize privacy surface‑area and allow for measurable impact on throughput and conversion metrics. Use A/B testing to isolate biometric impact on transaction speed, lift in average ticket, and customer satisfaction.
-
Embed regulatory compliance into vendor contracts: require vendors to supply documentation that aligns with jurisdictional obligations (risk assessments, technical documentation, and data processing agreements) and include termination rights tied to regulatory changes.
-
Insist on independent performance validation: third‑party verification of accuracy, demographic performance variance, and liveness detection should be contractually mandated before scaling beyond pilot phase.
-
Negotiate commercial flexibility: given the market concentration profile, buyers can secure multi‑vendor strategies or platform‑level integrations to avoid single‑source lock‑in while optimizing TCO across hardware refresh cycles.
-
Plan for privacy‑first UX: design enrollment and opt‑in flows that are transparent, reversible, and frictionless. The success of biometric payments will depend as much on customer trust as on raw biometric accuracy.
Conclusion — how PW Consulting’s study helps you make the right call in 2026
For executives preparing 2026 budgets and operational roadmaps, our research offers a clear, actionable view of where facial recognition payments stand today and where they are headed. We provide validated market sizing, strategic vendor analysis, regulatory playbooks, and deployment templates that convert abstract opportunity into executable programs. The market’s projected growth trajectory — rising sharply from the 2025 base year and anticipated to expand robustly through 2032 — creates a window for early scale advantages, but regulatory constraints and measurable performance gates mean that cautious, evidence‑driven scaling will reward disciplined early movers.
This release is a high‑level preview intended to outline strategic direction and operational priorities. For procurement teams, technology leaders, and policy managers who require segment‑level metrics, vendor scorecards, contract language, and the full suite of deployment templates, access to the full report is required. Visit our report page to obtain the complete study and the downloadable toolset to accelerate your 2026 program planning.
For detailed analysis of this topic, please visit the official page: Facial Recognition Payment Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com