

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automatic Leak Detection Equipment Market Valued at USD 4,158.5 Million in 2025, Poised to Grow at a 5.85% CAGR During 2026–2032

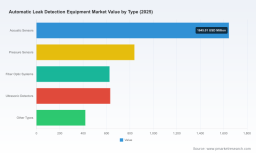
Automatic Leak Detection Equipment Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As companies plan budgets, procurement and product strategies for 2026, automatic leak detection (ALD) has moved from a niche technical capability to an operational and regulatory imperative. PW Consulting’s new market study — based on a 2025 base year and projecting through 2032 — shows a market that expanded steadily through the early 2020s and is forecast to continue growing at a mid-single-digit CAGR. The market grew from roughly USD 3.1 billion in 2020 to about USD 4.16 billion in 2025, with our model projecting a rise to approximately USD 6.19 billion by 2032 at a compound annual growth rate of 5.85% (2026–2032). These headline figures understate a more nuanced reality: demand drivers are increasingly regulatory and service-led, and competitive dynamics point to selective consolidation rather than a winner-takes-all outcome (CR3 ~38.5%; CR5 ~52.7%).
Automatic Leak Detection Equipment Market
Why this report matters for 2026 decision-making
-
Compliance-driven procurement: New and tightening regulations mean that ALD is now a line-item in capital and operational project plans for refrigeration OEMs, utilities, pipeline operators and commercial real estate managers. Companies making 2026 purchasing or retrofit decisions need validated cost and deployment scenarios that reflect the new regulatory timelines.
Automatic Leak Detection Equipment Market -
Technology selection under uncertainty: Multiple sensing approaches — from acoustic and fiber-optic monitoring to pressure- and gas-based detectors — are commercially mature, but their value depends on deployment scale, asset topology and service model. Our study offers decision frameworks for selecting a technology mix that balances sensitivity, false-alarm profiles and lifecycle cost without disclosing the proprietary split-level allocations in the full dataset.
Automatic Leak Detection Equipment Market -
Channel and service strategy: For vendors and systems integrators, the opportunity is as much in recurring monitoring and managed services as it is in hardware sales. The report identifies how vendors can convert one-time equipment sales into subscription-like revenue through analytics, permanent monitoring networks and SLA-backed inspection services.
What the report contains — practical content for immediate action
-
Market sizing and methodology: A transparent reconciliation of historical volumes and value (2020–2025) with scenario-based forecasts for 2026–2032, accompanied by sensitivity ranges and model access for licensed clients.
-
Regulatory impact models: Quantified implications of recent rules (including refrigerant-focused ALD mandates and pipeline detection performance standards) on near-term demand and retrofit cycles, with timelines and cost buckets for planning CAPEX and O&M.
-
Technology due diligence playbook: Side-by-side evaluation templates that score vendor technology across detection performance, integration complexity, installation time and lifecycle cost—designed to be reused directly during RFP and pilot phases.
-
Vendor benchmarking and sourcing matrix: Comparative profiles of established and emerging suppliers, go-to-market posture and service footprint — with executable vendor shortlists for utility, industrial and refrigeration procurements (note: detailed segment allocations and vendor market shares are included in the full report only).
-
Commercial templates and case studies: Negotiation checklists, sample service agreements and retrofit phasing templates built from live project data across water utilities, pipelines, industrial sites and commercial buildings.
-
M&A and investment thesis: Deal-screening criteria and valuation approaches for investors seeking exposure to ALD hardware, software analytics platforms and managed-monitoring service businesses.
Market dynamics shaping the 2026 agenda
Three forces are creating an urgent 12–24 month agenda for buyers and suppliers alike:
-
Regulatory acceleration. Recent rulemaking has moved ALD from guidance to enforceable requirement in several end markets. Notably, refrigerant-focused mandates require automatic leak detection systems to be operational within 30 days for new commercial and industrial refrigeration appliances with large refrigerant charges (effective Jan 1, 2026), and require retrofits on a defined cadence for pre-existing equipment by January 1, 2027. Separately, pipeline safety regulators have established advanced leak detection performance standards for gas transmission systems.
-
Shift from episodic inspection to continuous monitoring. Permanent networked monitoring (including acoustic and hydrophone-based permanent loggers and fiber-optic distributed sensors) is gaining traction in high-consequence infrastructure because it reduces detection time and enables analytics-driven prioritization of field crews.
-
Service economics and lifecycle thinking. The revenue opportunity is being rebalanced toward recurring services (monitoring, verification, false-alarm management) as owners seek to convert capital outlays into predictable operational performance. Vendors that combine hardware with software subscriptions and field-service SLAs are positioned to capture disproportionately high lifetime value.
Competitive landscape — what to watch among core players
The ALD sector is characterized by a mix of specialist instrumentation firms, industrial OEMs with system-level offerings, and service-centric players. The competitive set we profile in this study — including InterTech Development Company, Veeder-Root, GUTERMANN AG, INFICON and Hermann Sewerin GmbH — illustrates the range of strategic approaches currently winning business:
-
InterTech Development Company (Skokie, IL) : A specialist in automated leak and flow test systems, InterTech’s patented mass-flow and hydraulic technologies address high-precision industrial and medical applications. Recent trade-show visibility (MD&M West, Feb 2026) highlights demand in high-speed manufacturing and medical-device leak testing where throughput and resolution are critical. Strategic implication: InterTech’s strengths fit customers prioritizing production-line speed and traceability, and the company is a logical partner for OEMs that require embedded testing in manufacturing lines.
-
Veeder-Root (Simsbury, CT) : Established in tank gauging and digital pressurized line leak detection, Veeder-Root’s solutions are recognized for regulatory compliance in fuel storage and pipeline contexts. For buyers confronting fuel and fuel-handling regulations, Veeder-Root’s systems offer a credible compliance path with mature operational support networks. Strategic implication: companies operating distributed fueling assets should prioritize vendors with demonstrated regulatory testability and field-service coverage.
-
GUTERMANN AG (Zug, Switzerland) : A leader in acoustic detection for water networks, GUTERMANN has recently expanded its permanent monitoring line with a high-sensitivity hydrophone logger launched in late 2025. This product release underlines a market shift toward permanent detection in plastic-pipe networks. Strategic implication: utilities planning long-term leakage reduction programs should evaluate permanent acoustic networks as part of asset-management roadmaps, not only as one-off detection tools.
-
INFICON (Bad Ragaz, Switzerland) : INFICON’s gas-leak detection portfolio (helium, hydrogen, refrigerant, vacuum) plays to manufacturing and service markets where trace-gas detection underpins product quality and safety. Their breadth across tracer gases positions them well where regulators or customers demand traceable leak-rate verification. Strategic implication: manufacturers with strict quality controls or service providers conducting instrumented maintenance will find INFICON’s portfolio compelling.
-
Hermann Sewerin GmbH (Gütersloh, Germany) : With acoustic correlators, ground microphones and pipe locators, Sewerin is a strong contender in utility and municipal markets. Their field-hardened tools and channel relationships with contracting crews make them a logical choice for capital projects and reactive leakage programs. Strategic implication: procurement strategies should account for the ease of integration with existing field teams and training pathways — an area where Sewerin shows strength.
Strategic recommendations for 2026
-
Start retrofit procurement cycles now. Organizations subject to the 2027 retrofit deadlines should initiate pilot and procurement processes in 2026 to avoid compressed installation windows and higher spot-market prices for field services.
-
Prioritize vendors offering integrated compliance evidence. Select solutions that not only detect leaks but also provide audit-ready records and verification workflows to reduce compliance effort and downstream inspection costs.
-
Run a technology pilot that measures both detection performance and false-alarm handling costs. Sensitivity alone is not a business-case winner; end-to-end signal-to-action time and the effort required to validate events determine the operational ROI.
-
Evaluate service-partner networks as a differentiator. For large or geographically dispersed portfolios, the availability of certified local service, calibration and emergency response should be weighted heavily in vendor selection.
-
Consider layered procurement: combine permanent monitoring in high-risk corridors with portable and periodic systems elsewhere to optimize capital and O&M spend.
-
For investors and acquirers: look for businesses combining hardware, software analytics and recurring service revenue. These hybrid models command premium multiples as markets move from capex-driven to service-centric economics.
Why PW Consulting’s analysis is different
Our research blends a rigorous bottom-up market model with practical, executable outputs that executives can use immediately. Key differentiators include scenario-calibrated forecasts anchored to recent regulatory milestones, executable procurement templates, vendor scorecards designed for RFP use, and deployment playbooks that account for field labor, permitting and verification workflows. We intentionally present headline market and concentration metrics in this brief to orient readers; the complete report contains the full regional, type and application splits, vendor market shares, and transactional datasets that underpin our conclusions.
Next steps
For procurement leads, asset owners, systems integrators and investors preparing 2026 plans, the window to influence vendor selection, pilot outcomes and compliance pathways is short. Access the full PW Consulting Automatic Leak Detection Equipment Market report to obtain the complete segmentation, vendor benchmarking tables and downloadable decision tools necessary to convert these insights into executable plans. Contact PW Consulting via our website to request the full report and a tailored briefing that maps findings to your asset portfolio and regulatory obligations.
For detailed analysis of this topic, please visit the official page: Automatic Leak Detection Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com