

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Drawer-Type Switchgear Cabinets Market Poised for 6.0% CAGR Through 2032

Drawer Type Switchgear Cabinets Market: A 2026 Strategic Briefing for C-Suite Decision Makers
Executive snapshot
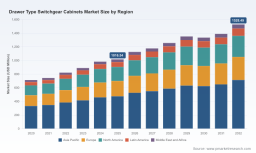
The global drawer type switchgear cabinets market is entering 2026 from a position of steady expansion and increasing strategic complexity. Our PW Consulting benchmark shows the market surpassing the one‑billion USD threshold in the base year (2025), rising to an anticipated 1.13 billion USD in 2026, and tracking to roughly 1.53 billion USD by 2032 on a 6.0% compound annual growth rate (forecast period 2026–2032). Market concentration is moderate: the largest three players account for just under 40% of the market while the top five capture roughly 53%, underscoring both global leadership and remaining room for regional or niche challengers.
Drawer Type Switchgear Cabinets Market
Why this briefing matters for 2026 decisions
- Translate macro momentum into executable plans: With predictable growth at a mid-single-digit CAGR and accelerating opportunities in data center, industrial modernization and critical power distribution, 2026 is a pivotal planning year to convert strategic intent into capacity, product and go‑to‑market moves.
- Manage margin pressure while investing for differentiation: Raw material volatility and trade policy shifts are compressing margins at OEMs. Firms that can re‑engineer cost structures and monetize higher‑value features (safety, digital telemetry, rapid serviceability) will widen competitive gaps.
- Prioritize capital allocation with optionality: Facility expansions, automation, and software-enabled product upgrades carry different lead times and return profiles. Scenario planning now reduces exposure to execution risk over the 2026–2032 horizon.
Market dynamics shaping 2026 strategy
Three structural dynamics will define the near term:
Drawer Type Switchgear Cabinets Market
- Demand composition is shifting toward modular, withdrawable drawer architectures that enable faster maintenance, safer operations and higher service revenues. Buyers increasingly favor systems that support both traditional distribution and emerging critical loads such as AI data centers.
- Input cost and policy volatility. Copper and electrical steel cost swings and targeted tariffs are elevating procurement and product‑cost risk. Organizations that implement robust raw‑material hedging, local sourcing strategies and product redesigns to reduce material intensity will protect margin.
- Consolidation and capability play. The market’s concentration metrics reflect a dual reality: established global players control a material share, yet regional OEMs and specialists retain tactical advantages in local channels and cost positions. Expect targeted M&A, JV activity and capacity plays in 2026 as incumbents shore up service footprints and niche technology stacks.
Competitive landscape: What industry leaders are doing
Our analysis of leading suppliers shows clear, differentiated strategic postures that buyers and investors should factor into their 2026 planning.
Drawer Type Switchgear Cabinets Market
- ABB (Zurich) — Platform scale and vertical integration: ABB’s investment in a major European manufacturing facility and its continued push to pair modular drawer systems with advanced breakers and digital protection positions it to capture high‑specification demand (notably AI‑ready data centers and large industrial users). Expect ABB to compete on system integrability, digital services and scale economics.
- Siemens AG (Munich) — Systems & services bundling: Siemens continues to emphasize turnkey distribution systems and lifecycle services. Their strength is in integrating switchgear into broader electrification and automation projects, which favors clients seeking single‑vendor accountability for complex installations.
- Schneider Electric (Rueil‑Malmaison) — End‑to‑end energy management: Schneider blends modular drawer‑type hardware with energy management software and service programs, enabling premium pricing for bundled lifecycle outcomes, especially in commercial and critical power applications.
- Eaton Corporation (Dublin) — Safety and power‑handling innovation: Eaton’s product innovations (e.g., rotating contact mechanisms and arc‑flash mitigation) aim to differentiate on safety, uptime and high current ratings—attributes that command warranty and service premium margins.
- Regional and specialist OEMs — China‑based suppliers and smaller global players continue to hold relevance by offering competitive pricing, rapid local delivery and customization. These vendors are often preferred for volume and retrofit work where cost and lead time are decisive.
Recent industry moves and what they imply
- Capacity investments by global incumbents signal an expectation of premium, specification‑driven demand growth (e.g., investments supporting AI‑ready data centers). For executives, this raises the bar on product development—if you want to compete at that level, your R&D and certification roadmaps must be fully funded in 2026.
- Product launches focused on higher amperage ratings, reduced arc flash risk and increased modularity indicate an ongoing migration up the value chain. Feature parity is reducing, so differentiation will come from integration of safety, digital telemetry, and proven field reliability.
- Regional OEMs’ continued strength underscores the need for layered go‑to‑market strategies—global OEMs will push platform standardization while regional players win on channel intimacy and cost agility.
Supply chain and cost pressures you cannot ignore
Raw material and trade developments are immediate tactical considerations for 2026:
- Copper and grain‑oriented electrical steel price volatility is materially impacting BOM costs and can reduce OEM margins if not mitigated. Procurement strategies must now include longer‑term contracts, formula pricing, and material‑substitution roadmaps where technically feasible.
- Protectionist trade measures and tariffs introduce localized cost differentials and may justify near‑market production or tariff‑aware sourcing. Scenario planning should evaluate the ROI of regionalizing capacity versus accepting tariff exposure.
- Supply chain resilience investments—dual sourcing, safety stock optimization, digitized supplier scorecards—deliver disproportionate value in a market characterized by intermittent commodity shocks and lead‑time variability.
Strategic imperatives for executives in 2026
Based on our scenario modelling and client advisory engagements, PW Consulting recommends five priority actions:
- Rebalance portfolio toward modular, serviceable, higher‑margin configurations. Where feasible, accelerate certifications and interoperability capabilities demanded by hyperscalers and large industrial OEMs.
- Lock in cost and supply through creative procurement: multi‑year offtake agreements, regional supplier partnerships, and design for material efficiency to offset copper/steel pressure.
- Invest selectively in factory modernization and digital test capabilities that shorten product time‑to‑market and reduce warranty exposure—especially if you target the upper end of the market spectrum.
- Use M&A and strategic partnerships to close capability gaps (digital protection, arc‑flash mitigation, aftermarket field services) rather than building all capabilities organically.
- Formalize a 2026 commercial playbook that differentiates on lifecycle economics, not just upfront hardware cost—warranty programs, performance SLAs and remote diagnostics are rapidly becoming differentiators.
What the PW Consulting report delivers (practical content)
Our full Drawer Type Switchgear Cabinets Market report is built as an operational toolkit for 2026 decision cycles. Key deliverables include:
- A validated market model with historical (2020–2025) and forecast (2026–2032) revenue series, scenario toggles and sensitivity levers that allow you to stress test assumptions across commodity, tariff and demand scenarios.
- A detailed competitive map with capability matrices, go‑to‑market archetypes and supplier scorecards to guide sourcing and partnership decisions.
- Actionable strategic playbooks: product development roadmaps, CapEx prioritization frameworks, M&A screens, and commercial pricing strategies tailored to different customer verticals and risk appetites.
- Operational templates: SKU rationalization tools, factory modernization ROI calculators, and a two‑year implementation schedule for supply chain resilience measures.
- Risk registers and mitigation playbooks covering raw‑material exposure, regulatory shocks and channel disruption—designed for board‑level oversight and auditability.
What we intentionally withheld — and why
To preserve the report’s role as the definitive source for executable detail, we have deliberately not published the granular regional and application revenue splits or the full proprietary company-level revenue breakdowns in this briefing. Those detailed segment tables, competitor revenue lines and downloadable financial models are available in the full report and are essential for transaction diligence, detailed pricing strategy and localized capacity planning.
How to use the report in your 2026 planning cycle
- CEOs & Boards — Use the scenario model to stress test strategy choices (build vs. buy; regionalize vs. centralize). Set funding thresholds for capability development and M&A screening informed by the model’s ROI outputs.
- COOs & Supply Chain — Implement procurement and sourcing playbooks immediately; use our supplier scorecards to reprioritize suppliers and restructure contracts before commodity shocks escalate.
- Product & Engineering — Prioritize modularity, safety and digital telemetry in the 2026 roadmap; leverage the report’s feature‑value matrices to optimize BOM redesign and certification sequencing.
- Commercial & Service — Reframe go‑to‑market offers around lifecycle value. Pilot bundled service agreements with selected accounts to validate pricing and operational readiness.
Final perspective
The drawer type switchgear cabinets market in 2026 presents both a continuity of steady, predictable growth and a set of accelerating strategic inflection points—material cost pressure, demand for higher‑value modular systems, and a competitive field split between global platforms and nimble regional specialists. Firms that treat 2026 as a year to reallocate capital, shore up supply resilience, and invest in differentiated product‑service propositions will enter the 2026–2032 window with optionality and defensibility.
For the exhaustive segment datasets, competitor revenue breakdowns, downloadable financial models, and a customized briefing for your management team, consult the full PW Consulting Drawer Type Switchgear Cabinets Market report on our website.
For detailed analysis of this topic, please visit the official page: Drawer Type Switchgear Cabinets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com