

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
Rubber Antioxidant Market Outlook 2032: Unlocking 5.5% CAGR Drivers and Asia Pacific's 99.21M Surge
By pmarketresearch, 2026-09-21
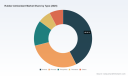
Navigating the Rubber Antioxidant Market: Strategic Trends and Commercial Opportunities
The rubber antioxidant market is experiencing a period of reconfiguration rather than straightforward expansion. While underlying demand continues to rise, the strategic landscape is being reshaped by regulatory scrutiny, supply chain volatility, and material substitution pressures. Market participants who treat this sector as a commodity play are likely to face margin compression, whereas those positioning themselves around technical differentiation, regulatory foresight, and regional capacity strategy can capture disproportionate value.
Over the forecast horizon, the market is expected to grow at a 5.5% compound annual rate, reflecting steady demand from industrial and automotive rubber applications. This trajectory is not uniform across time or geography, however. Growth will be uneven, driven by localized production shifts, evolving tire mandates, and the pace at which alternative chemistries reach commercial viability. The current market structure reflects a moderately concentrated environment, where scale advantages in synthesis and downstream integration matter, but differentiation is increasingly determined by compliance readiness and application-specific performance.
For executives and investors, the immediate question is not whether demand will persist, but where the structural shifts will occur and how quickly they will translate into pricing power, capacity utilization, or substitution risk. What follows is an analysis of the forces shaping the market, the competitive positioning that defines winners and laggards, and the strategic moves that decision-makers should prioritize.
Market Landscape and Defining Challenges
The market has expanded from the mid-2020s onward, crossing incremental thresholds as global automotive production, tire output, and industrial rubber consumption continued to recover and modernize. This expansion, however, masks underlying strain points that are beginning to redefine competitive dynamics. Growth in headline revenue is increasingly disconnected from margin stability, as input cost volatility and regulatory uncertainty introduce new variables into procurement and product design decisions.
One of the most significant challenges is the regulatory focus on specific aromatic amine chemistries, particularly 6PPD and its environmental transformation products. Authorities in the United States, Europe, and Canada have intensified scrutiny, driven by environmental toxicity concerns. While formal bans have not yet been enacted, major tire manufacturers have already begun evaluating alternatives. This creates a substitution pipeline that could unlock replacement demand exceeding $800 million by 2030. The strategic implication is clear: product portfolios anchored heavily on legacy amine chemistries face a gradual but accelerating reassessment risk, even before legislative action crystallizes.
A second challenge lies in raw material linkage. Precursors such as aniline, acetone, and isopropanol are derived from the benzene-toluene-xylene complex, tying antioxidant economics to crude oil price fluctuations and petrochemical cycle dynamics. Producers with flexible feedstock strategies, integrated supply arrangements, or hedging mechanisms can absorb volatility more effectively, while smaller or less integrated players face periodic margin disruption. This cost structure is not merely a production issue; it influences which regions and company profiles can sustain competitive pricing during cyclical downturns.
A third pressure point is demand composition. Tire-related consumption remains the dominant application driver, and tire industry demand for antioxidants has grown sharply in recent periods, reflecting rising automotive production and tightening safety and performance standards. Yet this concentration also means that market participants are exposed to the cyclicality of tire manufacturing, fleet replacement cycles, and regional capacity investments. Companies that rely on a narrow application base must manage periodic demand swings more carefully than those with broader industrial, footwear, and automotive rubber exposure.
Strategically, the challenge for incumbents is to balance near-term volume growth with long-term chemistry risk, while maintaining cost discipline in a feedstock-sensitive environment. The market is not contracting, but it is becoming more selective about which products, regions, and supply relationships will be rewarded.
Key Drivers Reshaping the Market
Technological Innovation and Process Efficiency
Process modernization is becoming a meaningful competitive lever. The installation of AI-based smart manufacturing systems in antioxidant plants has demonstrated measurable efficiency gains, including reduced energy consumption on key production lines for IPPD and 6PPD. These improvements matter because they directly affect operating costs and throughput stability, particularly in capacity-intensive segments. Automation and data-driven process control also support consistency in product quality, which is increasingly important as downstream rubber manufacturers demand tighter specification control for high-performance tire and industrial applications.
Beyond plant-level efficiency, innovation is also emerging in formulation design and application engineering. As end-users look for antioxidants that can meet both performance and evolving environmental expectations, suppliers with strong technical service capabilities are better positioned to co-develop tailored solutions. This shifts the value proposition from pure volume supply toward application support, helping companies defend pricing and build longer-term relationships with tire and rubber producers.
Regulatory and Environmental Scrutiny
Regulatory dynamics are no longer a peripheral compliance issue; they are becoming a market-shaping force. The heightened attention on aromatic amine antioxidants, particularly 6PPD and its quinone transformation product, has triggered legislative discussions across multiple jurisdictions. The market response has been preemptive rather than reactive. Tire manufacturers are initiating alternative evaluation programs, and this early-mover activity is creating a substitution landscape that could reorganize demand over the next several years.
PW Consulting Chemical & Energy Research Center
At the same time, regulatory pressure is not uniform across chemistries or regions. Phenolic and phosphite-based options, along with emerging alternatives, may gain relative advantage if they can demonstrate comparable performance with lower environmental risk profiles. The strategic opportunity lies in anticipating which chemistries will be scrutinized, which can be reformulated or substituted, and how quickly customers will change procurement specifications. Companies that build regulatory foresight into their R&D and portfolio planning will be better prepared to guide customers through specification transitions.
Demand-Side Evolution in Tire and Industrial Rubber
Demand continues to be anchored by tire manufacturing, where antioxidant usage is closely tied to production volume, tread performance requirements, and durability standards. Growth in tire-related antioxidant consumption has been supported by rising global automotive output and improving safety expectations, especially in markets where fleet modernization and higher-performance tire adoption are accelerating. In parallel, industrial rubber products and automotive rubber components contribute additional demand stability, though with different growth rhythms and specification sensitivities.
Rubber Additives Market
A notable shift on the demand side is the increasing importance of performance durability under harsher operating conditions. As vehicles, industrial equipment, and infrastructure rubber components face more demanding use environments, formulators are looking for antioxidants that deliver longer service life without compromising other rubber properties. This elevates the importance of product reliability and technical validation, reinforcing the value of suppliers that can provide consistent quality and application evidence rather than price-only competition.
Supply Chain and Cost Structure Dynamics
The cost base of antioxidant production remains tightly connected to petrochemical cycles. Since key precursors are derivatives of the BTX complex, price movements in crude oil and refining margins can quickly translate into input cost pressure. This dynamic rewards supply chain resilience: diversified sourcing, long-term contracts, regional production footprints, and inventory management discipline can all influence competitiveness. Producers that are able to localize capacity closer to major demand centers, or that can manage feedstock exposure more effectively, may gain an edge in both pricing stability and service reliability.
Capacity expansion also plays a role in shaping supply-side dynamics. Recent facility and packaging upgrades in key production locations have increased throughput for tire and industrial rubber applications. These expansions reflect a strategic response to sustained demand, but they also introduce the potential for regional supply imbalances if demand growth slows or if substitution accelerates faster than expected. The balance between capacity addition and demand realization will be a central factor in pricing behavior over the forecast period.
Competitive Positioning and Strategic Differentiation
The competitive landscape includes a mix of large multinational producers and specialized regional manufacturers, each pursuing distinct positioning strategies. Monolithic scale alone is no longer sufficient; leadership increasingly depends on chemistry focus, application access, and operational efficiency. Several companies illustrate how strategic differentiation is being built in this market.
Shanghai Chembroad New Materials has concentrated on TMQ and IPPD antioxidants, building a supplier identity around established chemistries with clear application relevance. Shandong Ekesen Chemical has focused on high-volume production of 6PPD and 4-ADPA, leveraging substantial annual capacity to serve demand-intensive lines. Jiangsu Sinorgchem Technology operates as a global leader in PPD and TMQ antioxidants under a major chemical affiliation, combining scale with broader organizational resources and market reach. Kemai Chemical has positioned itself as a leading manufacturer of TMQ, emphasizing product leadership in a widely used antioxidant category. NOCIL Limited has expanded capacity in recent years, reinforcing its role as an antioxidant supplier seeking growth through operational investment. Lanxess AG, through its Vulkanox portfolio and related additive offerings, brings a broader specialty chemicals perspective, where antioxidants are integrated into a wider value proposition for rubber and polymer applications.
What distinguishes stronger positioning is not simply product breadth but the ability to align capacity, technical support, and regulatory readiness with customer needs. Companies that can supply consistent volumes, support specification changes, and demonstrate operational reliability are more likely to retain preference during procurement cycles. In contrast, suppliers that are heavily exposed to a single chemistry facing elevated scrutiny, or that lack application-level engagement, may find it harder to defend share as customers reassess formulations.
Recent corporate activity reflects these strategic priorities. Capacity and packaging upgrades have improved throughput and responsiveness in key production locations, supporting tire and industrial rubber demand. Distribution partnerships are extending portfolio reach across multiple markets, improving availability and local service coverage. Technology upgrades in manufacturing have reduced energy consumption and improved process control on important production lines. These moves suggest a market where competitive advantage is being built through a combination of operational efficiency, distribution access, and portfolio alignment rather than through price alone.
The market structure is also evolving. Consolidation trends are plausible where scale, integrated feedstock handling, and regulatory compliance capabilities create barriers, while fragmentation may persist in niche chemistry segments or regional specialties. New entry will likely be selective, since successful participation requires not only production capability but also customer qualification, quality consistency, and the ability to navigate an increasingly complex regulatory environment. The most durable competitive positions will belong to players that can combine reliable supply, technical credibility, and anticipatory portfolio management.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. The first is accelerated portfolio diversification away from heavily scrutinized aromatic amine chemistries toward alternatives that can meet performance requirements while reducing environmental risk exposure. This trend does not imply immediate obsolescence, but it does suggest that formulation roadmaps will increasingly include substitution options. Companies that can offer credible alternatives, support qualification processes, and maintain supply reliability during transition periods will be well positioned to capture replacement demand.
Worldwide TMQ Rubber Antioxidant Market
The second trend is operational modernization as a competitive necessity. Energy efficiency, automation, and process control are becoming central to cost management and quality consistency. As margin pressure persists and customer expectations rise, producers that continue to invest in smart manufacturing, packaging automation, and throughput optimization will be better equipped to protect profitability. This also reinforces the importance of scaling efficiently rather than expanding indiscriminately, since overbuilding in the wrong regions or product lines could create utilization risk if substitution or demand shifts occur faster than anticipated.
The third trend is regional realignment of supply and demand. Capacity additions in key manufacturing regions, combined with shifting tire production and industrial rubber consumption patterns, will affect where supply is most accessible and where cost advantages are realized. This could favor companies with regional production footprints and local distribution capabilities, especially if customers prioritize supply security and shorter lead times. At the same time, feedstock linkage to petrochemical cycles means that regional cost structures will remain sensitive to energy and refining dynamics, reinforcing the need for flexible sourcing strategies.
The commercial opportunity across these trends is substantial for participants that act early and selectively. Substitution preparation can convert regulatory pressure into new product demand. Operational efficiency can protect margins even when input costs fluctuate. Regional supply alignment can improve customer stickiness and service differentiation. The risks are equally real: lagging regulation can change procurement timelines abruptly, feedstock volatility can compress margins for less flexible players, and premature capacity additions can undermine returns if demand growth or substitution timing diverges from expectations.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority should be to strengthen portfolio resilience around chemistry risk while continuing to invest in process efficiency. This means evaluating exposure to heavily scrutinized antioxidants, developing qualified alternatives where feasible, and ensuring that technical service capabilities are sufficient to support customer specification changes. Equally important is disciplined capacity planning: expansion should be tied to credible demand signals and substitution timing, not merely to current order momentum.
For investors, the key is to assess which companies are positioned to benefit from substitution demand, operational efficiency gains, and regional supply alignment, rather than relying on headline volume growth alone. Due diligence should focus on chemistry exposure, feedstock management, regulatory readiness, and the quality of customer relationships in tire and industrial rubber applications. Companies that can demonstrate both margin resilience and a credible transition pathway for future formulation requirements are likely to offer more durable value.
For procurement and supply chain leaders, the focus should be on securing supply continuity while preparing for formulation change. This includes diversifying supplier relationships where possible, evaluating alternative antioxidant options before mandatory shifts occur, and incorporating regulatory and sustainability considerations into sourcing criteria. Early engagement with suppliers that offer technical support and transition readiness can reduce disruption risk and improve negotiation leverage during specification changes.
In a market where regulatory direction, feedstock exposure, and substitution timing are all in motion, strategic advantage will go to organizations that can interpret these signals early and act with discipline. Detailed segment-level data, regional supply analysis, and company-specific capacity assessments can sharpen those decisions further. For decision-makers seeking a deeper operational view, the full research report provides expanded breakdowns and customized guidance to support planning across product, region, and application dimensions.
For detailed analysis of this topic, please visit the official page: Rubber Antioxidant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Antioxidants Market 2026: Why 6.8% CAGR and Natural Shifts Change Everything
By pmarketresearch, 2026-09-21
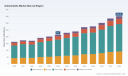
The Antioxidants Market at a Crossroads: Strategic Shifts and Commercial Opportunities Through 2032
The global antioxidants market has matured into a structurally complex industry where growth is no longer a simple function of volume expansion. Historical performance from 2020 through 2025 shows a market that navigated pandemic-era disruptions, supply chain recalibrations, and shifting downstream demand, while forecasted trajectory from 2026 through 2032 points to a steady but uneven expansion at a CAGR of 6.8 percent. Revenue is projected to move from the 215 million USD range in the base year toward the mid-300 million USD mark by the end of the forecast horizon, reflecting incremental gains rather than explosive jumps. This growth profile underscores an industry transitioning from broad-scale proliferation to targeted, value-driven deployment across polymers, personal care, food systems, and industrial additives.
Yet the headline trajectory masks several friction points that executives and investors must weigh carefully. Input cost volatility, particularly in petrochemical-linked feedstocks, continues to compress margins for manufacturers that rely on fixed-price contracts or thin operational buffers. Geopolitical instability, logistics bottlenecks, and energy market fluctuations have repeatedly forced portfolio-wide pricing adjustments, signaling that cost pass-through mechanisms are becoming a permanent feature of the operating environment rather than a cyclical anomaly. Regulatory divergence across regions adds another layer of complexity, as food-contact approvals, safety profiles for specific polymer applications, and stabilizer classifications vary widely, forcing companies to navigate fragmented compliance pathways while maintaining consistent quality standards. A third challenge lies in the tension between synthetic and natural formulations. While synthetic antioxidants continue to dominate in performance-critical industrial and polymer applications, natural alternatives are gaining traction in consumer-facing segments, creating a dual-track market where formulation strategy, sourcing resilience, and certification readiness determine competitive positioning.
For strategic decision-makers, these dynamics translate into a clear operational imperative: growth must be engineered through supply chain agility, formulation differentiation, and regulatory foresight rather than assumed from macro expansion alone. Companies that treat antioxidant procurement and production as a static cost line will face margin erosion and supply risk, while those that embed flexibility into sourcing, pricing, and application development will be better positioned to capture the relatively modest but durable expansion projected over the next several years.
Worldwide Polyolefin Antioxidants Market
Key Drivers Reshaping the Antioxidants Landscape
Technological Innovation and Formulation Breakthroughs
Product innovation remains one of the strongest levers for market evolution, particularly where performance requirements intersect with safety and regulatory constraints. Recent introductions of hindered phenolic and phosphite antioxidants with enhanced safety profiles demonstrate how formulation science is moving beyond basic stabilization toward application-specific risk mitigation. In spandex and rubber segments, for example, newer phenolic variants are being designed to balance oxidative protection with handling safety and processing compatibility, enabling formulators to meet stricter workplace and end-use standards without sacrificing material longevity. Phosphite antioxidants approved for food contact across dozens of countries illustrate a parallel trend: regulatory acceptance is expanding the addressable market for high-purity stabilizers that can bridge industrial performance with consumer safety expectations.
From a commercial standpoint, these breakthroughs reward companies that invest in application engineering and technical service capabilities. Antioxidants are increasingly evaluated not only by oxidation inhibition metrics but also by compatibility with complex polymer blends, processing temperatures, and downstream regulatory regimes. Businesses that embed formulation expertise into customer engagements can command stronger positioning, reduce substitution risk, and unlock premium segments where reliability and compliance justify differentiated pricing.
Policy and Regulatory Environment as a Market Shaper
Regulatory dynamics are no longer a background compliance function; they are actively reshaping capacity deployment, product roadmaps, and geographic allocation. Expanded production capacity for specialized stabilizers in China reflects how regulatory and market access considerations influence manufacturing footprint decisions. At the same time, approvals that allow specific antioxidants to be used in food-contact contexts across a broad set of countries create new commercial pathways, but only for suppliers that can document purity, traceability, and consistent quality under rigorous audit conditions.
The regulatory environment also amplifies the importance of regional differentiation. Markets with stringent food-contact, cosmetic, and industrial chemical regulations tend to reward manufacturers with established documentation practices and localized technical support, while faster-growing regions may prioritize cost efficiency and supply reliability. Executives should therefore view regulatory strategy as a core component of market entry and expansion planning, not merely a legal checklist. Companies that align product portfolios with the most demanding standards early often gain a durable advantage when those standards become reference points elsewhere.
Demand-Side Shifts Across Consumer and Industrial Channels
Demand patterns are being shaped by both consumer behavior and industrial engineering requirements, creating divergent growth vectors within the same market. In food and beverage applications, consumer preferences for cleaner labels and longer shelf stability continue to drive interest in antioxidants that can deliver protection without complicating ingredient declarations. In personal care and pharmaceutical contexts, the emphasis shifts toward safety, stability, and compatibility with sensitive formulations, encouraging adoption of antioxidants that meet stringent handling and purity expectations. Meanwhile, industrial demand in plastics, rubber, and lubricant applications remains anchored by durability, processing efficiency, and total cost of ownership rather than label appeal alone.
This dual demand structure means that market growth is unlikely to be uniform across segments. Consumer-facing categories may experience more visible enthusiasm for natural or low-risk alternatives, while industrial categories will continue to prioritize performance consistency and supply security. For producers and buyers alike, the strategic lesson is to avoid treating the antioxidants market as a monolith. Segment-level positioning, technical validation, and customer engagement models must be calibrated to the decision criteria that matter most in each channel.
Supply Chain Reconfiguration and Cost Structure Pressure
Cost structures in the antioxidants market are increasingly influenced by feedstock dynamics, energy pricing, and logistics exposure. Phenol and acetone price trends in early 2026 highlighted how upstream benzene and propylene-linked feedstocks can transmit cost pressure quickly through antioxidant production pathways. When combined with energy and freight volatility, these input dynamics create an environment where cost management becomes a strategic capability rather than a back-office function.
Recent pricing adjustments across major portfolios underscore how suppliers are responding to these pressures. Price actions have been framed not as opportunistic increases but as responses to cumulative cost escalation in raw materials, energy, and logistics. For downstream buyers, this reality necessitates more resilient procurement strategies: diversified sourcing, longer-term contractual flexibility, and closer alignment with suppliers that can demonstrate transparent cost pass-through logic and reliable production continuity. For manufacturers, the opportunity lies in improving operational efficiency, optimizing feedstock integration, and pursuing geographic diversification that reduces exposure to single-region disruptions.
PW Consulting Chemical & Energy Research Center
Competitive Landscape and Leader Strategies
Strategic Positioning Among Established Players
The market features a concentrated group of multi-application suppliers with global manufacturing footprints, technical service depth, and broad antioxidant portfolios. Leading companies are positioned around several differentiating strengths: portfolio breadth spanning phenolic, aminic, and phosphite chemistries; geographic manufacturing diversity that supports supply resilience; and application-specific expertise that connects stabilization performance to end-use requirements. In plastics, lubricants, polymers, rubber, and specialty coatings, the most effective competitors are those that can pair chemical capability with practical processing knowledge, enabling customers to integrate antioxidants into complex formulations with minimal trial-and-error.
Geographic diversification is particularly significant. Manufacturing expansion in regions such as Mexico and Antwerp, alongside specialized capacity additions in Asia, reflects a deliberate effort to balance proximity to key demand centers with supply chain redundancy. This footprint strategy matters because antioxidants are often needed in consistent quality and reliable volume by downstream manufacturers who cannot afford extended downtime or formulation variability. Suppliers that can offer both technical credibility and logistical reliability tend to secure more defensible relationships in performance-driven applications.
Differentiation Through Portfolio and Compliance Depth
Competitive advantage is increasingly defined by how well companies align chemistry, compliance, and commercial execution. Some suppliers emphasize higher-purity, food-contact-ready stabilizers that unlock consumer-adjacent applications. Others focus on robust industrial-grade portfolios designed for rubber, fuels, and lubricants, where oxidative stability under demanding conditions is paramount. A third group differentiates through specialty formulations that address narrow but valuable use cases, such as spandex-compatible phenolic systems or phosphite antioxidants with enhanced safety characteristics.
This segmentation of differentiation suggests that scale alone is insufficient. The most resilient players combine portfolio breadth with targeted specialization, enabling them to serve both high-volume industrial accounts and niche performance markets. For decision-makers evaluating supplier relationships or competitive threats, the relevant question is not only who offers the widest range of antioxidants, but who can credibly support the regulatory, safety, and processing requirements of the specific applications in scope.
Market Structure Evolution: Consolidation, Diversification, and Entry Risk
Market concentration indicates that a relatively small group of major suppliers commands a significant share of revenue, which tends to reinforce pricing influence and technical standardization within core applications. At the same time, the presence of regional manufacturers and specialty producers ensures that competition remains active, particularly where local service, formulation customization, or cost positioning creates room for differentiated offers. New entry is possible, but it is most viable where a company can bring a clear technical advantage, regulatory readiness, or supply advantage rather than attempting to compete purely on commodity terms.
The evolving structure also points toward selective consolidation in areas where scale, feedstock integration, and compliance infrastructure provide durable advantages. In contrast, specialty niches may remain fragmented as companies compete on application performance and customer proximity. For executives, this means that competitive strategy should be tailored to the layer of the market in question: large-scale industrial supply may reward scale and reliability, while performance-sensitive applications may reward technical differentiation and regulatory readiness.
Forward Outlook: Trends and Commercial Implications for 2026-2032
Trend One: Cost Resilience Becomes a Competitive Moat
Over the next several years, volatility in feedstocks, energy, and logistics is expected to remain a defining feature of the market. Companies that build stronger cost resilience through feedstock integration, manufacturing efficiency, and supply diversification will be better equipped to manage pricing without sacrificing customer trust. Commercial opportunities will accrue to suppliers that can offer transparent cost logic, reliable continuity, and flexible contracting models, while buyers that establish multi-source strategies and application-level cost optimization will be less exposed to abrupt portfolio-wide adjustments.
Worldwide Phenolic Antioxidant Market
Trend Two: Regulation-Led Market Access Will Separate Winners from Followers
As approvals, safety expectations, and compliance documentation become more central to commercial access, regulatory capability will increasingly function as a market-entry filter. Products that achieve broad food-contact or application-specific safety acceptance can open new demand pools, but only when supported by rigorous quality systems and traceable manufacturing practices. Businesses that proactively align development pipelines with the most demanding regulatory environments are likely to gain first-mover advantages that translate into broader geographic and segment expansion later.
Trend Three: Application-Specific Formulation Will Outpace Generic Growth
The market’s growth trajectory will be supported less by uniform volume increases than by tailored solutions that match antioxidant properties to specific polymers, processing conditions, and end-use requirements. This favors suppliers and buyers that invest in technical collaboration, formulation testing, and application engineering. The commercial upside lies in moving from transactional supply to solution-based relationships, where antioxidant selection is integrated into broader material design and quality strategies.
Risks and Uncertainties to Monitor
Despite a constructive growth outlook, several uncertainties could alter the path. Feedstock price spikes or prolonged energy cost pressure could compress margins and delay investment. Regulatory changes in key regions could shift acceptable chemistries or documentation requirements unexpectedly. Demand patterns in consumer-facing segments may evolve faster than industrial categories, creating portfolio mismatches for suppliers that over-index on one track. Supply chain disruptions affecting logistics or regional manufacturing could also create temporary dislocations, particularly if concentration leaves limited fallback options in certain applications.
Strategic Actions for Decision-Makers
For Manufacturers and Suppliers
Priority should be placed on strengthening the intersection of formulation capability, regulatory readiness, and supply resilience. Investment in application-specific development can create defensible differentiation, especially where safety profiles, food-contact readiness, or processing compatibility unlock higher-value segments. At the same time, operational efficiency and geographic diversification should be treated as strategic assets that reduce exposure to input and logistics volatility. Companies that can communicate clear value logic to downstream customers, rather than competing primarily on price, will be better positioned to preserve margins through cost cycles.
For Investors and Strategic Partners
The market opportunity is not in broad-based assumptions of rapid expansion, but in identifying companies and segments where differentiation, compliance depth, and supply reliability can translate growth into durable profitability. Due diligence should focus on feedstock exposure, manufacturing footprint flexibility, regulatory track record, and the extent to which a business serves application-specific demand rather than undifferentiated commodity volume. In this environment, value creation is likely to come from businesses that can navigate cost pressure while expanding into regulated or performance-sensitive applications.
For Buyers and Procurement Leaders
Procurement strategy should move beyond spot purchasing toward structured resilience. Diversifying suppliers, securing contractual flexibility, and aligning antioxidant selection with application requirements can reduce exposure to pricing shocks and supply disruptions. Technical evaluation should include regulatory status, safety documentation, and processing compatibility, especially when substituting materials or expanding into new end-use categories. Close coordination between procurement, R&D, and quality functions will be essential to balance cost objectives with performance and compliance needs.
The antioxidants market is entering a phase where strategic advantage depends on how well organizations integrate technical, regulatory, and supply-chain capabilities into their commercial approach. For readers seeking deeper segmentation detail, regional breakdowns, and customized scenario planning for specific applications or buyer-supplier configurations, the full PW Consulting research report provides extended data and tailored analysis to support more granular decision-making.
For detailed analysis of this topic, please visit the official page: Antioxidants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Adhesives Market: Why 6.01% CAGR and Regional Shifts Matter
By pmarketresearch, 2026-09-21
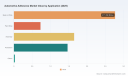
The Automotive Adhesives Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global automotive adhesives market has established itself as a critical enabler of modern vehicle manufacturing, quietly transforming how cars are assembled, bonded, and performance-tested. Valued at approximately USD 6.65 billion in 2025, the sector has expanded steadily from a base of USD 4.97 billion in 2020, reflecting a compound annual growth rate of 6.01 percent through the forecast horizon extending to 2032. At that point, the market is projected to cross the USD 10 billion threshold, signaling a structural shift rather than a cyclical upturn. This trajectory is not merely a function of rising vehicle production volumes. It is being reshaped by material science breakthroughs, regulatory tightening, the electrification of powertrains, and a competitive landscape where consolidation and specialization are occurring simultaneously.
For executives, strategy teams, investors, and procurement leaders, the implications are significant. Adhesives are no longer peripheral consumables; they are strategic inputs that influence body-in-white integrity, battery pack durability, lightweight multi-material assembly, and compliance with environmental mandates. The market's concentration profile—with the top three players accounting for roughly 48.6 percent of revenue and the top five capturing approximately 60.2 percent—indicates a landscape where scale, certification, and application-specific expertise create meaningful barriers. Yet fragmentation persists in niche segments, regional manufacturing hubs, and emerging EV-specific formulations. Understanding where value is created, where margins are pressured, and where capability gaps open doors is essential for making informed capital and partnership decisions.
Market Snapshot and Core Challenges
Over the historical period from 2020 to 2025, the automotive adhesives market grew from USD 4.97 billion to USD 6.65 billion, a pace that accelerated as OEMs and tier suppliers increasingly adopted bonding technologies to replace mechanical fasteners, reduce weight, and improve crashworthiness. The forward trajectory through 2032 points to continued expansion, with year-on-year increments that reflect both volume growth and value migration toward higher-performance formulations. Revenue distribution across regions underscores a clear geographic rebalancing: Asia Pacific leads in aggregate demand, Europe maintains a substantial share driven by stringent safety and emissions standards, North America anchors high-value OEM and aftermarket applications, while Latin America and the Middle East and Africa collectively represent growing but still developing basins of opportunity.
Segmentation by chemistry and application reveals where the market's center of gravity resides. Reactive and structural chemistries—including polyurethane, acrylic, epoxy, and silane-modified polymer systems—command significant share, reflecting the industry's need for durable, crash-resistant, and thermally stable bonds. Application-wise, body-in-white bonding represents the largest demand pool, followed by assembly, powertrain, and paint shop usage, with specialized electronics and sensor modules emerging as faster-growing niches. This distribution is not static; it is being re-drawn by vehicle architecture changes and manufacturing process automation.
Challenge One: Electrification-Driven Specification Complexity
The transition to electric vehicles has introduced a new layer of technical and regulatory complexity. Battery pack assembly now demands adhesives that meet functional safety expectations aligned with ISO 26262, alongside performance characteristics such as thermal stability, electrical insulation, and, increasingly, debonding-on-demand capabilities to support end-of-life recycling. Suppliers that cannot deliver certified, application-validated formulations risk exclusion from increasingly narrow supplier qualification lists. For manufacturers, this complexity raises the cost of validation, extends cycle times for new platform launches, and forces brittle dependencies on a small set of qualified chemistry providers.
Challenge Two: Regulatory Pressure and Emissions-Compliant Formulations
Low-VOC and water-based adhesive systems are no longer optional enhancements; they are becoming baseline requirements under evolving EU and US automotive emission directives. The shift imposes reformulation costs, can alter bonding performance profiles, and demands re-qualification of processes already in production. Companies that treat compliance as a checkbox rather than a product architecture principle may find themselves locked out of certain plants or facing costly retrofits. Conversely, those that embed low-emission design early can convert regulation into a differentiator, especially in European and North American assembly networks where procurement teams are explicitly scoring sustainability metrics.
Engineering Adhesives Market
Challenge Three: Supply Chain Timing and Regional Manufacturing Alignment
Just-in-time delivery expectations are intensifying as vehicle platforms become more customized and production footprints diversify. The establishment of specialized adhesive warehousing and regional distribution nodes—such as recent facility expansions in India to support growing EV and component manufacturing—illustrates how proximity, inventory strategy, and lead-time reliability are being re-evaluated. Companies that depend on distant, inflexible supply chains face higher working capital costs and greater disruption risk. Aligning formulation availability with regional manufacturing rhythms is becoming a competitive necessity rather than an operational nicety.
Key Drivers Reshaping the Market
Technology Innovation and Material Performance Ceilings
Advancements in structural adhesive chemistry are expanding the envelope of what bonding can achieve. Silane-modified polymer systems, next-generation epoxy platforms, and high-temperature resistant hot-melt and reactive formulations are enabling stronger, lighter, and more durable joints across mixed-material bodies. Recent product introductions targeting vibration damping, increased structural integrity, and display-component bonding demonstrate how chemistry is being tuned to specific vehicle subsystems rather than sold as generic industrial inputs. At the same time, adhesives engineered for electronics, lidar, and autonomous driving modules are gaining relevance as sensor suites proliferate, creating a parallel growth path beyond traditional metal-to-metal or metal-to-composite bonding. These innovations are not just performance upgrades; they are value-creation levers that let suppliers command premium positioning in safety-critical and electronics-intensive applications.
Policy and Regulatory Environment as a Market Filter
Regulatory frameworks are increasingly functioning as market filters rather than background conditions. IATF 16949 certification has become effectively mandatory for automotive adhesive suppliers seeking to remain in OEM supply chains, raising the quality management bar and compressing the list of eligible vendors. Simultaneously, low-emission formulation requirements are reshaping chemistry roadmaps, pushing manufacturers toward water-based, low-VOC, and reactive systems that satisfy both performance and environmental criteria. The effect is twofold: incumbents with mature certification infrastructure and reformulation capabilities gain a defensive moat, while new entrants must invest early in quality systems and compliance documentation to be taken seriously. Policy, in this context, is accelerating consolidation among qualified suppliers and raising the cost of market entry for undifferentiated players.
Electronic Adhesives Market
Demand-Side Shifts in Material Architecture and Platform Strategy
Vehicle architecture is moving toward mixed-material construction, where aluminum, high-strength steel, composites, and polymers are combined to optimize weight, cost, and crash performance. This shift increases reliance on adhesives that can handle dissimilar substrates, manage thermal expansion mismatches, and maintain structural continuity under dynamic loading. Body-in-white bonding remains the largest demand pool, but assembly and powertrain segments are expanding as manufacturers use adhesives to streamline line operations, reduce spot-welding dependencies, and enable new joining sequences. On the EV side, battery module and pack assembly has emerged as a distinct demand driver, pulling specialized formulations that balance mechanical strength with thermal and electrical considerations. Procurement behavior is also evolving: OEMs are increasingly seeking single-supplier or reduced-supplier strategies for adhesive families to simplify validation and logistics, which tends to favor suppliers that can offer broad, certified portfolios across multiple vehicle subsystems.
Supply Chain and Cost Structure Dynamics
Raw material volatility, energy costs, and formulation complexity are reshaping cost structures across the adhesives value chain. High-temperature resistant chemistries required for under-hood and powertrain applications depend on specialized feedstocks, and the shift toward low-emission systems can alter raw material baskets and processing requirements. At the same time, regional manufacturing expansion is changing logistics economics: closer proximity to assembly plants reduces freight exposure and improves service levels, but it also requires local inventories and demand-forecasting discipline. Companies that can balance formulation performance with cost-stable sourcing, and that invest in regional distribution to support just-in-time expectations, are better positioned to protect margins while meeting OEM service-level agreements. The broader effect is a market where cost leadership alone is insufficient; reliability, certification, and regional responsiveness are becoming equally weighted in supplier selection.
Competitive Landscape and Leading Strategies
The competitive field is defined by a core group of multinational suppliers with established automotive credentials, complemented by specialized players that compete on chemistry depth, application focus, or regional proximity. Henkel AG & Co. KGaA remains a prominent force with its Teroson structural adhesive portfolio, targeting body-in-white, EV battery assembly, and lightweight designs under IATF 16949 certification. Recent activity underscores a dual strategy of product refinement and geographic enablement: new structural adhesive series have been introduced to enhance integrity, durability, and vibration damping, while silane-modified polymer offerings for display components have extended the portfolio into electronics-adjacent applications. Henkel's regional warehouse expansion in India further illustrates a focus on just-in-time service for growing manufacturing hubs. The company's positioning is broad-spectrum and certification-led, aiming to serve as a multi-application partner across the vehicle.
PW Consulting Chemical & Energy Research Center
3M Company continues to leverage its Scotch-Weld structural and repair adhesives across OEM assembly, collision repair, and high-strength bonding contexts. Its strength lies in a well-recognized brand, broad application coverage, and a repair-market presence that complements original equipment supply. 3M's portfolio approach allows it to address both factory-floor and aftermarket demand, diversifying revenue streams and reducing dependence on any single platform cycle. Sika AG, through its Sikaflex and SikaPower lines, emphasizes crash-durable body shop bonding, exterior applications, and mixed-material joining, aligning closely with the trend toward multi-substrate architectures. Its strategy reflects deep application engineering and strong relationships in body-shop and structural bonding workflows.
H.B. Fuller Company focuses on low-emission water-based, hot-melt, and reactive adhesives for lightweight vehicle structures and aftermarket repair, positioning compliance and process flexibility as core selling points. Dow Inc.'s DOWSIL silicone adhesives and sealants target under-hood, electronics, and mobility applications, capitalizing on thermal and environmental resistance characteristics that are difficult to replicate with other chemistries. Arkema S.A. brings Bostik Pliogrip and EV battery adhesives to the market, with emphasis on composite and battery module bonding, aligning product development with electrification-driven demand. BASF SE's Acronal polymer dispersions address sound-damping and interior trim lamination, reflecting a focus on comfort,NVH, and interior assembly efficiency. Permabond LLC supplies anaerobic, cyanoacrylate, and epoxy adhesives for under-bonnet and high-temperature formed-in-place gasket applications, where thermal endurance up to 250°C is a decisive factor. DELO Industrial Adhesives GmbH has reinforced its automotive quality credentials with IATF 16949 certification and offers UV-cured and two-component adhesives for vehicle electronics, lidar, and autonomous driving modules, capturing value in sensor and electronics bonding. Jowat SE contributes hot-melt and dispersion adhesives for interior lamination and automated assembly, supporting high-speed production environments. Illinois Tool Works Inc. provides Plexus structural adhesives for EV battery assembly and lightweight bonding, aligning with electrification and weight-reduction priorities. Lord Corporation rounds out the field with Chemlok and engineered adhesives for vibration damping, motion management, and structural applications, addressing both performance and functional safety requirements in demanding contexts.
Strategic Positioning and Differentiation
Across this group, several differentiation patterns emerge. Certification and quality systems have become table stakes; suppliers that can demonstrate IATF 16949 compliance and functional safety alignment are better positioned to pass qualification gates. Chemistry breadth and application specificity are the next layer of advantage: companies that can cover body-in-white, battery, electronics, and interior applications with validated portfolios reduce the number of suppliers OEMs need to manage, which has real procurement value. Regional service capability—warehousing, technical support, and rapid response—translates directly into just-in-time reliability and can sway selection in cost-sensitive or high-service environments. Finally, sustainability-enabled formulations are shifting from reactive compliance to proactive differentiation, particularly where emission directives are tightening and where OEM sustainability scorecards influence purchasing decisions.
Evolving Market Structure: Consolidation, Fragmentation, and New Entrants
The market is experiencing simultaneous consolidation and fragmentation. Consolidation is visible in acquisitions that expand adhesive and sealant capabilities, such as PPG Industries' acquisition of Revocoat from the Axson Group to broaden automotive offerings. Such moves allow established coatings or materials players to add bonding technologies, capture cross-selling opportunities, and strengthen regional footprints. Fragmentation persists in specialized niches—electronics-grade UV-cured systems, high-temperature gasketing adhesives, and debonding-on-demand formulations for battery recycling—where smaller or more focused suppliers can win on technical performance and faster iteration cycles. New entrants face a steep climb because certification, validation, and regional service expectations are high, but opportunities exist where incumbents are slow to adapt to EV-specific requirements, low-emission chemistry, or localized supply expectations. In practice, the landscape is likely to tilt toward a core of large, certified suppliers with broad portfolios, complemented by targeted specialists and regional players that serve specific applications or geographies with agility.
Forward Outlook: Trends Shaping the Next Three to Five Years
The next several years will be defined by the convergence of electrification, advanced driver-assistance hardware, and sustainability mandates. One clear trajectory is the expansion of EV battery and high-voltage system bonding as a distinct growth engine. As platforms standardize around modular packs and as recycling considerations become more prominent, demand will grow for adhesives that balance structural and thermal performance with functional safety alignment and debonding-on-demand capability. This trend opens opportunities for suppliers that can deliver validated, recyclable-friendly formulations and provide the documentation and testing support that OEMs require. It also introduces risk: qualification cycles are long, and any performance or safety inconsistency can stall adoption at the platform level.
A second trend is the rise of electronics- and sensor-intensive bonding. Lidar, camera modules, and autonomous-driving hardware require adhesives with precise curing behavior, thermal stability, and fine-tolerance application control. UV-cured and two-component systems are well suited to these applications, and suppliers with strong electronics bonding expertise are positioned to capture value as sensor suites become standard across more vehicle segments. The commercial opportunity lies in pairing material performance with application engineering and process support, because integration complexity often matters as much as the adhesive itself. The uncertainty here stems from the pace of sensor normalization, cost pressure on electronic hardware, and the possibility that alternative mounting technologies could compete with adhesives in certain contexts.
A third trend is the regulatory and operational push toward low-emission, water-based, and low-VOC formulations as a baseline expectation. Companies that treat sustainability as embedded product architecture—rather than as a separate compliance line—can convert regulation into a competitive edge, particularly in European and North American plants where procurement teams are scoring emissions and VOC performance. The associated risk is reformulation cost and the potential for performance trade-offs that require re-validation; suppliers and buyers alike will need to manage the tension between compliance timelines and production continuity.
Across these trends, the commercial opportunity is not simply to sell more adhesive volume. It is to win influence over platform design, reduce supplier fragmentation for OEMs, and build regional service models that make bonding processes more reliable and repeatable. The risk side is equally clear: over-concentration in a small set of chemistries, lagging certification readiness, and inflexible supply chains can quickly erode a supplier's relevance as vehicle architectures and regulations evolve.
Actionable Guidance for Decision Makers
For Manufacturers and Tier Suppliers
Invest early in certification and quality infrastructure, including IATF 16949 alignment and functional safety documentation where relevant. Treat low-emission and water-based formulation development as a core product strategy rather than a reactive fix, and prioritize chemistries that can span multiple applications to reduce the supplier count OEMs must manage. Strengthen regional service capabilities—warehousing, technical support, and rapid issue resolution—to meet just-in-time expectations and to differentiate in competitive bid situations. Finally, build validation partnerships with OEMs on EV battery and electronics bonding applications before platform decisions lock in supplier lists, because late entry is difficult to remedy once qualification cycles close.
For Investors
Focus on suppliers with credible certification records, broad automotive portfolios, and demonstrated ability to scale regional service. Preference should lean toward companies that are expanding into EV-specific bonding, electronics-grade adhesives, and debonding-on-demand or recyclable-friendly formulations, as these areas align with the strongest demand tailwinds. Monitor consolidation activity that adds adhesive and sealant capabilities to existing materials or coatings platforms, since cross-selling and footprint expansion can accelerate revenue and margin improvement. Be cautious about purely volume-driven plays without certification depth or regional responsiveness, because those factors increasingly determine who retains preferred status in OEM supply chains.
For Procurement and Sourcing Leaders
Structure sourcing strategies to balance breadth and reliability: favor suppliers that can provide certified, multi-application portfolios while maintaining regional availability and low-emission compliance. Build transparency into qualification criteria so that sustainability metrics, functional safety documentation, and service-level commitments are weighed alongside unit cost. Encourage early engagement with adhesive suppliers during vehicle architecture planning, because bonding decisions made late in the process often force compromises on performance, logistics, or compliance. Where possible, pilot new formulations on non-critical assemblies first to validate process fit before scaling to structural or battery applications.
The automotive adhesives market is moving from a mature, volume-driven market into a more performance- and compliance-shaped environment where certification, chemistry specificity, regional service, and sustainability are decisive. The companies and investors that understand these shifts—and act on them with discipline—will be better positioned to capture the next phase of growth. For decision makers seeking deeper segmentation, detailed regional and application-level data, and customized strategic recommendations, the full market research report provides the granular evidence base needed to translate these trends into concrete plans and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Urea Formaldehyde Resin Market: Why the 2% CAGR Trajectory Signals Real Growth Drivers
By pmarketresearch, 2026-09-21
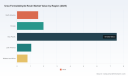
Urea Formaldehyde Resin Market: Navigating the Crossroads of Compliance, Cost, and Innovation
The global urea formaldehyde resin market stands at a strategic inflection point, where established demand patterns intersect with tightening regulatory frameworks and evolving supply chain dynamics. Valued at approximately $11.71 billion in 2020, the market expanded steadily through 2023, reaching $12.47 billion, before experiencing a modest contraction to $12.93 billion in 2025. Looking ahead, the trajectory projects growth to $14.85 billion by 2032, reflecting a compound annual growth rate of roughly 2.0% over the forecast horizon. This measured expansion masks significant underlying volatility, as the market navigates structural shifts in end-use demand, raw material pricing pressures, and regulatory mandates that are fundamentally reshaping product specifications and competitive positioning. For executives and investors operating in downstream manufacturing, chemical distribution, or advanced materials, understanding these dynamics is no longer optional; it is a prerequisite for capital allocation, product roadmap planning, and supplier diversification strategies.
Market Landscape and Structural Headwinds
A Moderating Growth Curve with Regional Asymmetry
The market’s historical progression from $11.79 billion in 2021 to $13.08 billion in 2024 illustrates a period of steady adoption, primarily fueled by construction activity, furniture manufacturing, and panelboard production across key industrial corridors. However, the slight pullback in 2025 to $12.93 billion signals a transitional phase rather than a cyclical downturn. Demand composition remains heavily anchored in traditional adhesive applications, with powder and liquid formulations splitting the revenue base in ways that reflect both application engineering preferences and logistical constraints. Liquid grades continue to dominate environments requiring on-site mixing flexibility or continuous processing lines, while powder variants maintain relevance in settings where shelf stability, transportation efficiency, and controlled inventory management outweigh handling complexity.
PW Consulting Chemical & Energy Research Center
Three Critical Challenges Shaping the Next Cycle
First, regulatory tightening around volatile organic compound emissions has moved from a compliance checkbox to a product architecture constraint. Standards such as CARB Phase-III and EPA TSCA Title VI now require composite wood products to limit formaldehyde emissions to 0.05 ppm, effectively mandating reformulation across legacy adhesive portfolios. The operational implication extends beyond chemistry; it touches manufacturing line validation, certification timelines, and customer acceptance cycles, creating a compliance burden that disproportionately affects mid-tier producers without dedicated R&D or regulatory affairs capacity.
Second, raw material cost volatility has introduced margin compression risks that are difficult to hedge through conventional procurement strategies. Formaldehyde pricing in Europe reached 370 euros per ton in early 2025, marking a historical high, while urea formaldehyde resin prices in the United States climbed to 908 USD per metric ton in September 2025, closely tracking feedstock urea movements. These cost pressures are not isolated to a single region or feedstock; they reflect broader energy, logistics, and agricultural input dynamics that ripple through the value chain and challenge the economics of both conventional and low-emission formulations.
Third, the cost differential between conventional and low-emission resin variants introduces a strategic dilemma for downstream buyers. Industry analysis indicates that meeting EU and global low-emission requirements can add 10–15% to production costs for standard UF resins compared with compliant low-emission grades. This premium is not uniformly absorbed across end markets; cost-sensitive applications face pricing resistance, while premium wood bonding and construction panel segments increasingly treat low-emission compliance as a baseline entry requirement rather than a differentiated feature.
Paraformaldehyde Market
Key Drivers Reshaping the Market Trajectory
Regulatory Architecture as a Catalyst for Product Innovation
Regulatory pressure is no longer a static compliance backdrop; it is actively steering formulation pathways and competitive differentiation. The requirement for a 40% reduction in VOC emissions by 2026 under CARB Phase-III has accelerated reformulation programs across the adhesive and panelboard ecosystem. This regulatory trajectory is pushing producers to invest in low-emission UF grades that meet E0, CARB, and LEF/ULEF standards without sacrificing bond strength, cure speed, or process compatibility. The practical outcome is a market where regulatory conformity becomes a gatekeeper for market access, particularly in North American and European composite wood segments, while simultaneously creating a technical moat for suppliers that can deliver compliant formulations at scale.
Green Chemistry and Low-Emission Formulation as Competitive Levers
The push toward reduced formaldehyde emissions has coincided with broader sustainability mandates across the chemical and manufacturing sectors, creating a convergence of compliance and corporate ESG objectives. Leading producers are responding by developing resin lines that lower formaldehyde output while maintaining performance benchmarks for plywood, particleboard, fibreboard, and impregnation applications. Some offerings now emphasize emission reductions of up to 90% relative to conventional benchmarks, positioning low-emission grades as enablers for downstream manufacturers seeking to satisfy both regulatory standards and customer-facing sustainability claims. This trend is not merely a technical adjustment; it is reshaping procurement criteria, as panel producers and wood product manufacturers increasingly evaluate resin suppliers on emission profiles, certification support, and formulation flexibility alongside price and delivery reliability.
Demand-Side Shifts in Construction, Furniture, and Panel Manufacturing
Downstream demand patterns are evolving in response to housing market dynamics, interior fit-out cycles, and the expansion of engineered wood solutions in both developed and emerging economies. Wood adhesives remain the dominant application driver, reflecting the continued reliance on UF resins in panelboard production and furniture assembly. At the same time, demand for molding compounds, surface coatings, and textile finishing applications introduces segments with distinct performance requirements and growth profiles. The practical implication for resin producers is that volume growth is increasingly tied to application-specific engineering rather than broad commodity displacement. Customers are looking for formulations that balance cure compatibility, moisture resistance, emission compliance, and total cost of ownership, which elevates the importance of technical service, application testing, and co-development arrangements.
Supply Chain Reconfiguration and Cost Structure Dynamics
Feedstock pricing, energy costs, and logistics constraints are collectively reshaping the cost structure of UF resin production. The convergence of elevated formaldehyde prices in Europe and urea-linked resin pricing movements in the United States underscores the vulnerability of input cost pass-through strategies, particularly in markets where downstream price sensitivity limits aggressive adjustments. In response, some producers are exploring formulation optimization, regional sourcing adjustments, and inventory positioning strategies to mitigate exposure. For downstream manufacturers, this environment heightens the importance of supplier diversification, contractual flexibility, and scenario planning around input cost trajectories. It also reinforces the strategic value of long-term supply agreements that incorporate transparency on feedstock indices and formulation change timelines.
Urea Formaldehyde Concentrate (UFC) Market
Competitive Landscape and Strategic Positioning
Fragmented Leadership with Clear Differentiation Paths
The market exhibits a moderate concentration profile, with a handful of large players commanding a significant share of revenue while a broader base of specialty and regional suppliers competes on formulation, service, and application expertise. This structure supports both scale-driven efficiency and differentiation-driven premium positioning, depending on the segment and geography. Leading companies are pursuing distinct strategic paths that reflect their product portfolios, geographic footprints, and sustainability commitments.
Ercros has focused on low-emission UF resin offerings designed to meet stringent formaldehyde standards across plywood, particleboard, fibreboard, and impregnation applications. Its resin range emphasizes compatibility with LEF, ULEF, CARB, and E0 requirements, positioning the company as a solution provider for downstream manufacturers navigating emission compliance without sacrificing processing performance. Prefere Resins has pursued a sustainability-forward strategy, integrating green chemistry principles into its amino resin portfolio for wood adhesives, insulation, and construction panels. The company’s emphasis on CO2-neutral and bio-based resin innovations, reinforced by recent sustainability certifications and reporting, signals a strategic alignment between regulatory compliance and corporate ESG positioning.
Hexion Inc. continues to leverage established methylated UF grades and resin platforms tailored for wood panel adhesives and particleboard production, emphasizing performance consistency and application familiarity in mature markets. BASF SE maintains a broad specialty chemicals footprint, with urea formaldehyde resin grades positioned for wood bonding and adjacent applications, benefiting from integrated supply chain capabilities and cross-market formulation expertise. Dynea Oy and Advachem contribute through specialized resin technology and niche chemical portfolios, respectively, serving panel adhesives and wood product manufacturing with focused application support. Kronospan Limited’s in-house UF resin production for particleboard, MDF, and plywood illustrates a vertical integration model that prioritizes supply control and formulation alignment with internal panel specifications. Metadynea International GmbH complements this landscape with targeted UF resin offerings for wood panel and adhesive applications, reinforcing the diversity of strategic approaches across the competitive field.
Strategic Takeaways from Recent Industry Moves
Recent developments underscore how sustainability credentials and transparency are becoming embedded in competitive positioning. Prefere Resins’ achievement of an EcoVadis Gold rating for ESG performance, alongside the publication of its first Group Sustainability Report covering 2023–2024, reflects a broader trend in which ESG performance is increasingly treated as a procurement consideration rather than a peripheral corporate initiative. The company’s earlier emphasis on Mission Zero 2050 CO2-neutral bio-based resin innovations further illustrates how long-term decarbonization targets are being translated into product strategy. For buyers and investors, these moves signal that supplier selection is increasingly influenced by verifiable sustainability performance, formulation roadmaps, and the ability to support downstream compliance narratives.
Market Evolution: Integration, Specialization, and New Entrant Dynamics
The competitive landscape is evolving along two complementary paths. On one hand, scale-oriented players continue to pursue integration and portfolio breadth to capture efficiency advantages, support multi-application supply, and reinforce regional distribution reach. On the other hand, specialization is intensifying around low-emission formulations, application-specific engineering, and sustainability-linked product attributes. This dual dynamic creates opportunities for incumbents to defend share through performance and compliance leadership, while also opening space for new entrants or expanding specialists that can address underserved application niches or regional compliance requirements. The likely outcome over the next several years is a market where broad-scale suppliers coexist with highly differentiated formulation specialists, and where downstream buyers increasingly manage a dual-sourcing strategy that balances cost, compliance, and technical support.
Forward Outlook: Three Trends Shaping the 2026–2032 Window
Low-Emission Compliance as a Baseline, Not a Premium
As regulatory mandates mature and enforcement intensifies, low-emission UF grades are likely to transition from differentiated offerings to market-entry requirements in key regions. This shift will compress the commercial advantage of early compliance while simultaneously raising the cost of late adaptation. Manufacturers that have already validated low-emission formulations, secured certification pathways, and aligned production lines with compliant grades will be better positioned to manage transition risk. Conversely, suppliers and downstream buyers that delay reformulation or certification readiness may face margin erosion, supply disruption, or exclusion from regulated procurement channels.
Formulation Engineering and Application-Specific Value Creation
Volume growth is expected to increasingly depend on application-specific value creation rather than broad-based resin displacement. Wood adhesives will remain the core demand anchor, but opportunities in molding compounds, surface coatings, and textile finishing will require tailored performance profiles, processing compatibility, and technical service. This trend favors suppliers that can combine formulation flexibility with application engineering, testing support, and regional responsiveness. For downstream manufacturers, it creates an incentive to deepen technical collaboration with resin partners, particularly where product performance, emission profile, and total cost of ownership must be optimized simultaneously.
Cost Volatility and Supply Chain Resilience as Strategic Priorities
Input cost volatility, particularly around formaldehyde and urea-linked feedstocks, is likely to remain a defining feature of the market environment. While long-term contracts, index-linked pricing, and regional sourcing adjustments can mitigate some exposure, the broader reality is that cost resilience will become a strategic priority for both producers and buyers. This includes evaluating supplier diversity, inventory positioning, formulation flexibility, and scenario planning around feedstock price trajectories. For investors, this environment rewards companies that demonstrate disciplined cost management, transparent input exposure, and the ability to adapt formulations without compromising compliance or performance.
Strategic Actions for Decision-Makers
For Manufacturers and Panel Producers
- Validate low-emission resin compatibility across existing and planned production lines before regulatory deadlines tighten further, prioritizing formulations that meet CARB, EPA TSCA, and E0/EU expectations without disrupting cure profiles or bond performance.
- Diversify resin sourcing to balance cost, compliance, and technical support, while establishing clear criteria for supplier evaluation that include emission data, certification support, formulation adaptability, and supply continuity.
- Invest in application testing and co-development with resin suppliers where performance or emission targets require custom formulation, reducing the risk of line stoppages, rework, or certification delays.
For Investors and Strategic Capital Allocators
- Prioritize companies that demonstrate verifiable progress on low-emission formulation roadmaps, ESG transparency, and cost discipline, as these attributes are increasingly correlated with market access and procurement preference in regulated segments.
- Monitor feedstock exposure and pricing pass-through capabilities, recognizing that margin resilience will depend on formulation optimization, regional sourcing flexibility, and contract structures that align input costs with downstream pricing reality.
- Evaluate consolidation and specialization dynamics as indicators of where value is being created, particularly in segments where low-emission compliance, application engineering, and sustainability credentials are reshaping buyer selection criteria.
For Procurement and Supply Chain Leaders
- Integrate emission compliance, certification support, and sustainability reporting into supplier scorecards alongside price, lead time, and quality metrics, ensuring that procurement decisions reflect both regulatory readiness and corporate ESG objectives.
- Establish scenario planning for raw material cost movements, including index-linked contracting, alternative supplier qualification, and inventory strategies that reduce exposure to sudden feedstock price spikes.
- Engage early with resin suppliers on formulation change timelines and certification requirements, aligning procurement calendars with technical validation cycles to avoid disruption during regulatory transitions.
Closing Perspective
The urea formaldehyde resin market is not defined by a single growth driver or a uniform competitive narrative. It is a market in which regulatory compliance, feedstock economics, application-specific performance, and sustainability positioning intersect to shape buyer behavior and supplier strategy. The modest headline growth projection conceals a more nuanced reality: value creation is shifting toward compliance readiness, formulation flexibility, and supply chain resilience, while cost volatility and certification complexity reward companies that act early and coordinate across technical, commercial, and procurement functions. For executives, investors, and supply chain leaders, the practical imperative is to treat resin selection and supplier relationships as strategic variables rather than transactional inputs, and to align product roadmaps, sourcing decisions, and investment priorities with the regulatory and cost realities that will define the next cycle.
For detailed segmentation data, regional demand profiles, application-level revenue splits, and tailored scenario analysis, the full research report provides the granular data and customized recommendations needed to translate these market dynamics into concrete planning parameters.
For detailed analysis of this topic, please visit the official page: Urea Formaldehyde Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electrical Insulation Paper Market: 3.9% CAGR Growth and Strategic Shifts Through 2032
By pmarketresearch, 2026-09-21
The Electrical Insulation Paper Market: Navigating Strategic Shifts and Commercial Opportunities Through 2032
The electrical insulation paper market operates at the intersection of grid modernization, materials science, and industrial infrastructure. Valued at approximately 172.8 million USD in 2025, the sector has demonstrated a measured but steady trajectory over the past five years, recovering from a temporary contraction in 2022 before expanding to its current baseline. Looking ahead to 2032, the market is projected to reach roughly 224.9 million USD, reflecting a compound annual growth rate of 3.9 percent. This expansion is not merely a function of incremental demand; it signals a structural realignment in how electrical assets are designed, maintained, and decommissioned across mature and emerging economies alike. For executives and investors, the growth story masks a more nuanced reality: value creation will increasingly depend on technological differentiation, supply-chain resilience, and alignment with evolving regulatory frameworks.
The regional distribution of demand underscores this complexity. North America, Europe, and the Asia Pacific region collectively account for the largest share of consumption, with Asia Pacific standing out as both a volume driver and an innovation incubator. Latin America and the Middle East and Africa contribute smaller but growing portions, often tied to localized grid expansion, renewable integration, and aging asset replacement programs. Rather than treating geography as a static backdrop, it is more useful to view regional dynamics as distinct demand engines with different pacing, procurement cycles, and compliance requirements.
Market Snapshot and Core Challenges
The market's five-year arc from 2020 to 2025 reveals resilience in the face of supply disruptions and shifting project timelines. After reaching 142.8 million USD in 2020, the sector expanded to 152.1 million USD in 2021, experienced a brief pullback to 148.9 million USD in 2022, and then accelerated through 2023 and 2024 before stabilizing near 170.8 million USD and settling at 172.8 million USD in 2025. This pattern reflects the interplay of delayed infrastructure orders, inventory normalization, and the gradual ramp-up of high-voltage and distribution projects. The forward trajectory through 2032 suggests that growth will be incremental rather than explosive, with annual gains becoming more pronounced as capital expenditure cycles mature and replacement demand gains momentum.
Within this macro framework, several challenges and inflection points are reshaping how participants position themselves:
- Raw-material volatility and cost asymmetry : Cellulose-based insulation materials remain highly sensitive to pulp pricing and processing inputs. Recent cycles have shown cellulose pulp costs rising by 9–14 percent in certain production periods, contributing to roughly 28 percent fluctuation in overall production costs for insulation paper manufacturers. This volatility compresses margins for suppliers that lack long-term contract structures or value-added differentiation, while simultaneously creating pricing power for manufacturers that can secure stable feedstock or offer performance-guaranteed specifications.
- Regulatory and compliance pressure on processing : Environmental regulations governing emissions, wastewater, and chemical handling during paper processing are tightening across multiple jurisdictions. Producers operating in regulated regions face compliance costs estimated at 6–11 percent of operational expenditure. These requirements are not merely cost centers; they increasingly function as market-access gatekeepers, influencing procurement decisions for utilities and OEMs that must document the sustainability and compliance profile of their supply chains.
- Technology transition and specification shifts : The insulation paper segment is undergoing a quiet but meaningful shift in performance expectations. End users are demanding better thermal stability, longer service life, and more predictable behavior under load cycling and high-voltage stress. This creates a bifurcated market: commoditized grades compete primarily on price and availability, while engineered grades with thermal upgrading, controlled creping, and specialized coatings command premium positioning and longer-term contracts.
These challenges are not isolated. They interact with one another in ways that determine which players can scale profitably and which are forced into cyclical pricing battles. The organizations that navigate this environment effectively treat raw-material strategy, regulatory readiness, and product engineering as a single integrated capability rather than separate functional concerns.
Key Demand Drivers Behind Market Evolution
Understanding why the electrical insulation paper market is moving requires looking beyond top-line growth to the forces shaping procurement behavior, product design, and supply economics. Four drivers stand out as particularly decisive over the next several years.
Technological Innovation and Material Performance
Innovation in insulation paper is shifting from incremental grade improvements to system-level performance optimization. Manufacturers are investing in thermal upgrading technologies, controlled creping, and coating processes that enhance dielectric strength, reduce moisture absorption, and improve mechanical integrity under prolonged thermal stress. A notable example of this direction appeared in March 2026, when Weidmann Electrical Technology AG published technical guidance focused on optimizing transformer insulation systems for improved performance, cost efficiency, and supply reliability. Rather than presenting a single product launch, the release reflected a broader industry pivot toward helping customers design insulation systems that balance longevity, operational flexibility, and total cost of ownership.
This matters because insulation paper is increasingly evaluated not as a standalone material but as part of a transformer or cable insulation architecture. Buyers are more willing to pay for grades that reduce maintenance intervals, support higher loading conditions, and provide more consistent behavior across temperature and humidity ranges. For producers, the implication is clear: value is migrating toward engineered solutions and technical services, while undifferentiated commodity grades face persistent margin pressure.
Policy and Regulatory Environment
Policy frameworks are playing a larger role in shaping demand timing, product eligibility, and supplier qualification. Environmental regulations are raising the bar for emissions and processing standards, while grid policy in many regions is accelerating modernization programs that indirectly increase demand for reliable insulation materials. Utilities and equipment manufacturers are incorporating supplier compliance records into their procurement criteria, especially where public funding, environmental disclosures, or long-term service agreements are involved.
The compliance dimension also affects innovation pathways. Materials and processes that can demonstrate lower environmental impact, recyclable or sustainably sourced fiber inputs, and reduced processing emissions are becoming more relevant in bids and specification documents. This does not mean that regulation is a pure constraint; it also creates a qualification barrier that can protect established players with robust compliance infrastructure and penalize smaller competitors that struggle to absorb the operational expenditure associated with emissions control and documentation.
Electrical Insulation Tape Market
Demand-Side Behavior and Infrastructure Priorities
On the demand side, procurement behavior is being reshaped by asset age profiles, load growth, and the need to reduce outage risk. Power transformers and distribution transformers remain central to the insulation paper market, reflecting the continued reliance on transformer-based grid architecture even as alternative equipment formats evolve. At the same time, cable and wire applications, motors and generators, and capacitor-related uses contribute meaningful demand, each with its own specification requirements and replacement cycles.
A broader shift is also underway in how end users evaluate reliability. Rather than focus exclusively on lowest initial material cost, many buyers are weighing insulation performance against the financial and operational consequences of failure, especially in networks where outage costs are high or where renewable integration increases loading variability. This behavioral change favors suppliers that can provide consistency, traceability, and technical support, and it encourages longer-term purchasing relationships rather than spot-market procurement.
PW Consulting Chemical & Energy Research Center
Supply Chain and Cost Structure Dynamics
The cost structure of insulation paper production is tightly linked to kraft pulp availability, processing complexity, and logistics. Kraft pulp remains the primary raw material for cellulose-based electrical insulation paper, and its properties directly influence dielectric performance and mechanical durability. Sustainability perceptions around fiber sourcing can also influence buyer preferences, particularly where utilities or OEMs emphasize responsible procurement in their public commitments.
Recent pricing dynamics illustrate the sensitivity of the sector. Kraft pulp serves as the foundational input, and price movements can ripple quickly through producer cost models. For example, kraft pulp prices were recorded at 4,824 CNY/T on June 5, 2026, down 0.25 percent from the prior day and 23 percent over the preceding month, highlighting how quickly input costs can shift within a single production cycle. When combined with the broader pattern of cellulose-pulp price increases of 9–14 percent in recent cycles and the associated 28 percent fluctuation in production costs, the message is unambiguous: cost management is now a strategic capability, not a tactical accounting task.
Insulating Oil Market
Suppliers are responding by combining feedstock security, product mix optimization, and engineering differentiation. The most resilient operators are those that can maintain stable input access while directing more of their manufacturing capability toward grades that carry higher performance value and more defensible pricing.
Competitive Landscape and Leading Strategies
The competitive structure of the electrical insulation paper market is moderately concentrated, with the top three players accounting for roughly 35 percent of market share and the top five reaching about 42 percent. This concentration level suggests that while established manufacturers hold significant influence, there is still room for regional specialists, niche grade providers, and technology-focused entrants to compete on specification, service, or local responsiveness.
Strategic Positioning of Key Players
The market's leading participants differentiate themselves through a combination of material heritage, processing capability, product range, and technical engagement with customers.
- Weidmann Electrical Technology AG , headquartered in Rapperswil, Switzerland, is positioned around high-quality kraft flat paper and presspaper made from 100 percent electrical-grade kraft wood pulp. Its processing capabilities, including creping, coating, slitting, and transformer-focused processing, support a product portfolio aimed at performance-sensitive applications. The company's March 2026 technical guidance on optimizing transformer insulation systems highlights an approach that extends beyond material supply into system-level optimization, cost efficiency, and supply reliability. This kind of technical engagement helps anchor long-term relationships with customers that value engineering support as much as material consistency.
- Ahlstrom-Munksjö Oyj , based in Espoo, Finland, offers electrotechnical kraft insulation paper under the Elektro-Tek brand, serving power transformers, instrument transformers, and high-voltage cables. Its portfolio spans plain and creped grades, with thermal upgrading capabilities under Thermotrans. The breadth of its electrotechnical offering, combined with brand recognition in engineered paper solutions, gives the company a strong platform in segments where specification accuracy and thermal performance are critical. Its scale and material expertise also support consistent supply and documentation practices that are increasingly important to regulated buyers.
- Krempel GmbH , located in Vaihingen/Enz, Germany, leads in electrical insulation materials including kraft papers and composites for energy-sector transformers and components. Its positioning emphasizes an integrated view of insulation materials beyond paper alone, which can be attractive to customers seeking coordinated solutions across transformer and component applications. In a market where material interaction and system reliability matter, a composite-aware portfolio can support stronger specification influence and deeper engineering partnerships.
- Cottrell Paper Company, Inc. , a family-owned manufacturer in Rock City Falls, New York, has produced high-grade electrical insulating papers and specialty materials since 1926, including copaco and glazed variants for transformers and motors. Its long operational history and family-owned structure contribute to a positioning centered on continuity, specialty grade depth, and relationship-based service. For certain regional and application-specific buyers, this profile can be a meaningful differentiator, particularly where supply continuity and product familiarity are valued alongside technical performance.
How the Competitive Landscape Is Evolving
The market is not static. Several patterns are shaping its evolution:
- Consolidation pressure on scale and compliance : Larger producers benefit from broader product portfolios, stronger compliance infrastructure, and greater ability to absorb raw-material volatility. This encourages gradual consolidation or partnership activity, especially where feedstock access, technical service capacity, or regional distribution networks need reinforcement.
- Differentiation through engineered grades : As commoditized segments face pricing pressure, competition increasingly centers on thermal upgrading, grade consistency, coating technology, and technical support. Players that can validate performance claims and reduce customer risk are better positioned to maintain margins and win specification decisions.
- Regional and specialty niches remain viable : Despite concentration at the top, the market still rewards localized responsiveness, long-standing customer relationships, and specialized grades for motors, capacitors, and cable applications. New entrants and smaller manufacturers can compete by serving underserved specifications or by offering flexible service models that larger players may not prioritize in every region.
Forward-Looking Trends and Commercial Implications
If current dynamics persist, three trends are likely to shape the market over the next three to five years.
Trend One: Performance Specifications Will Become More System-Centric
Insulation paper will increasingly be evaluated in the context of complete insulation systems rather than as a standalone commodity. Thermal upgrading, controlled processing, and application-specific grading will matter more as utilities and OEMs seek to manage load cycling, extend asset life, and reduce failure risk. The commercial opportunity lies in helping customers match material grades to actual operating conditions, which can justify premium pricing and create stickier relationships. The risk is that suppliers who cannot demonstrate measurable performance benefits may be forced into price competition or replaced by alternatives that offer clearer technical value.
Trend Two: Cost and Compliance Will Function as Strategic Filters
Raw-material volatility and regulatory compliance costs will continue to influence both supplier survival and buyer selection. Producers that can stabilize input exposure, optimize product mix, and document compliance with confidence will be better placed to protect margins and win long-term contracts. The opportunity is to treat these factors as part of a broader value proposition rather than as overhead. The risk is that short-term pricing pressure leads to underinvestment in compliance and quality systems, which can erode trust and restrict access to regulated or quality-sensitive markets over time.
Trend Three: Regional Demand Will Diverge in Pace and Preference
Growth will not be uniform across regions. Some markets will be driven by grid expansion and new asset installation, while others will be shaped by replacement cycles, load growth, and selective modernization. Procurement preferences will also diverge, with some regions emphasizing price competitiveness and others prioritizing reliability, traceability, and compliance documentation. This creates opportunities for suppliers that can tailor product offerings, service models, and commercial terms to regional realities. The risk is that a one-size-fits-all strategy leaves a company over-exposed in slower-growing markets while under-serving faster-growing ones.
Strategic Recommendations for Decision Makers
For manufacturers, investors, and procurement leaders, the practical question is how to translate these dynamics into action. A few strategic priorities stand out.
For Manufacturers and Suppliers
- Shift value capture toward engineered solutions : Reduce reliance on undifferentiated commodity grades by expanding thermal upgrading, coating, and custom processing capabilities. Pair product innovation with technical support that helps customers optimize insulation system design, because performance validation is becoming a key determinant of specification wins.
- Build feedstock and cost resilience : Lock in stable input access where possible, hedge exposure to pulp price swings, and use product mix to balance margin variability. Cost volatility is large enough that manufacturers without a clear feedstock and pricing strategy will find it difficult to sustain profitability through cyclical swings.
- Invest in compliance as market access, not just cost control : Treat emissions, processing, and documentation requirements as part of the competitive moat. Buyers in regulated environments increasingly use compliance status as a qualification filter, so robust compliance capability can open doors even when price alone is not the deciding factor.
For Investors
- Focus on differentiation and system-level capability : Evaluate companies not only on volume and footprint but also on technical engagement, engineered product depth, and the ability to reduce customer risk. In a market where performance expectations are rising, these qualities are more likely to support durable pricing than pure scale alone.
- Monitor feedstock exposure and margin structure : Because production costs can fluctuate significantly with cellulose pulp pricing, investor diligence should include how a company manages input volatility, whether it has contract structures that stabilize costs, and how much of its revenue comes from premium grades versus commoditized segments.
- Watch regulatory-driven consolidation signals : Compliance costs and qualification requirements can advantage larger, better-resourced players. Investment theses should consider whether a target is positioned to gain from consolidation or whether it depends on a niche that remains defensible despite increasing scale and regulatory pressure.
For Procurement and End-User Decision Makers
- Evaluate total cost of ownership rather than material price alone : Insulation paper choices affect maintenance intervals, thermal behavior, and asset reliability. Procurement processes that weigh lifecycle risk, specification accuracy, and supplier technical support are better aligned with long-term operational goals than those focused narrowly on initial purchase cost.
- Require documentation and traceability : Given tightening compliance expectations and the importance of responsible sourcing, buyers should seek clear documentation on material origin, processing standards, and performance validation. This not only supports regulatory and sustainability objectives but also reduces uncertainty in storage, handling, and application.
- Plan for specification evolution : As insulation requirements become more system-centric, procurement teams should anticipate changes in grade selection, thermal upgrading needs, and supplier collaboration. Early engagement with suppliers on performance targets and operating conditions can prevent mismatches and improve long-term supply reliability.
The electrical insulation paper market is entering a phase where growth, competition, and value creation are increasingly determined by technical differentiation, cost resilience, and regulatory readiness. The broad trajectory through 2032 points to steady expansion, but the real strategic prize will go to organizations that can align product engineering, supply-chain planning, and compliance capability with the evolving expectations of utilities, OEMs, and regional project markets. For decision makers seeking a more granular view of segmentations, regional dynamics, and actionable commercial scenarios, the full PW Consulting study provides deeper quantitative breakdowns and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrical Insulation Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Short Fiber Reinforced Thermoplastic Market: Why the 2032 $3.8M Outlook Changes Strategy
By pmarketresearch, 2026-09-21
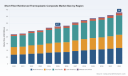
Navigating the Short Fiber Reinforced Thermoplastic Composite Market: Strategic Trends and Commercial Opportunities
Market Landscape: Growth Trajectory Amid Structural Shifts
The short fiber reinforced thermoplastic composite market has established itself as a critical materials ecosystem, bridging the gap between traditional unreinforced polymers and heavier, more complex continuous fiber solutions. Over the historical period from 2020 through 2025, the sector demonstrated consistent expansion, reflecting steady adoption across manufacturing verticals that prioritize weight reduction, mechanical performance, and processing efficiency. The market’s evolution from a niche engineering substitute to a mainstream component material underscores a fundamental shift in how designers approach lightweighting and structural optimization.
Looking ahead to the forecast horizon of 2026 through 2032, the market is projected to sustain a compound annual growth rate of approximately 4.52 percent, culminating in a total revenue base that will meaningfully outpace the starting valuation of the current cycle. This growth trajectory is not merely a continuation of historical momentum; it is being reshaped by material science breakthroughs, regulatory pressures favoring recyclable and lightweight structures, and a recalibration of supply chain priorities. The convergence of these forces is creating a market that rewards players who can balance cost efficiency with tailored performance characteristics.
Despite the positive outlook, the industry faces several structural challenges that will define competitive outcomes over the next few years. First, the tension between fiber loading optimization and processability remains a persistent bottleneck. Short fiber composites offer significant stiffness and strength improvements over neat thermoplastics, yet achieving high fiber loadings without compromising melt flow, surface finish, or cycle time requires sophisticated compounding expertise and sometimes costly processing adaptations. Manufacturers must navigate this trade-off carefully, particularly when end-users demand both performance and cost parity with unreinforced alternatives.
Second, raw material volatility and feedstock availability continue to inject uncertainty into cost structures. The prices of glass and carbon fibers, as well as the engineering resins that serve as polymer matrices, are subject to fluctuations driven by energy costs, capacity constraints, and regional supply dynamics. These variables complicate long-term pricing strategies and can compress margins for compounders and converters who lack vertical integration or long-term supply agreements.
Third, the market is experiencing a gradual but decisive shift toward sustainability-driven material selection. While short fiber reinforced thermoplastics inherently offer recyclability advantages over thermoset composites, the industry must still address end-of-life processing, fiber recovery, and the environmental footprint of virgin fiber production. Regulatory frameworks and corporate sustainability targets are increasingly mandating verifiable lifecycle benefits, pushing material developers to innovate in bio-based reinforcements, recycled fiber integration, and design-for-disassembly principles.
Key Drivers Reshaping the Market
Technological Innovation and Material Performance Breakthroughs
The pace of compounding and formulation technology has accelerated, enabling more precise control over fiber length distribution, dispersion quality, and interfacial bonding between fiber and matrix. Advances in twin-screw extrusion, reactive compatibilization, and surface treatment chemistries are allowing manufacturers to push fiber loadings higher while maintaining manageable viscosity profiles. These improvements translate directly into parts that can replace metal components or continuous fiber assemblies in applications where absolute maximum strength is less critical than balanced stiffness-to-weight ratios and high-volume producibility.
Equally important is the evolution of multi-material and hybrid reinforcement strategies. Formulators are increasingly blending glass and carbon short fibers, or combining synthetic fibers with natural reinforcements, to tune cost and performance curves for specific use cases. This customization capability is expanding the addressable market beyond traditional heavy-duty structural components into sectors that previously relied on metal insertion molding or unreinforced engineering plastics. The ability to dial in mechanical, thermal, and dimensional stability characteristics at the compound level is turning short fiber reinforced thermoplastics into a more versatile design tool rather than a single-purpose material class.
Policy and Regulatory Environment as a Catalyst
Regulatory momentum is converging on two fronts that directly benefit short fiber reinforced thermoplastic composites: lightweighting mandates and sustainability requirements. In transportation and industrial equipment, efficiency standards continue to tighten, compelling OEMs to reduce mass without sacrificing safety or durability. Short fiber reinforced thermoplastics offer a practical pathway to weight reduction through part consolidation, thinner wall designs, and substitution of heavier metals, all while retaining compatibility with high-volume injection molding and extrusion processes.
On the sustainability side, policies promoting circular economy practices and extended producer responsibility are reshaping procurement criteria. Unlike thermoset composites, thermoplastic matrices can theoretically be reprocessed, and short fibers do not inherently preclude recycling streams. However, achieving credible circularity claims requires clear data on recyclability, fiber recovery economics, and the performance of recycled-content compounds. Regulatory pressure is therefore pushing both material suppliers and end-users to invest in lifecycle assessment, standardized testing, and transparent reporting, which in turn elevates the strategic value of compounds that can demonstrably reduce environmental impact without compromising functional requirements.
Demand-Side Shifts in End-Use Markets
Demand is being reshaped by a broader design philosophy shift toward multi-material architectures and smart component optimization. Engineers are increasingly selecting materials based on localized performance needs rather than defaulting to a single material across an entire assembly. This approach favors short fiber reinforced compounds in applications where ribbing, boss features, and moderate load-bearing requirements can be met efficiently without the cost and complexity of continuous fiber layup or metal machining. The result is a growing emphasis on application-specific compound design, where mechanical properties, moisture resistance, thermal stability, and surface appearance are tailored to the part’s functional environment.
At the same time, sectors such as transportation, electrical and electronics, and consumer goods are driving volume growth through different mechanisms. Transportation continues to be a dominant demand center as vehicle platforms pursue mass reduction and corrosion resistance. Electrical and electronics applications are benefiting from the need for flame-retardant, dimensionally stable, and lightweight housing and connector materials. Consumer goods and industrial equipment manufacturers are exploring short fiber reinforced thermoplastics for durability and aesthetic improvements in high-wear components. This diversified demand base reduces dependence on any single vertical and provides a buffer against cyclical downturns in individual sectors.
Supply Chain Reconfiguration and Cost Structure Evolution
Supply chain dynamics are undergoing a structural reorientation as manufacturers reassess resilience, proximity, and total cost of ownership. The post-pandemic emphasis on supply security has encouraged regionalization of compounding and conversion capacity, reducing reliance on distant supply nodes and shortening lead times for custom formulations. This trend favors compounders with flexible production assets and strong technical service capabilities, as they can respond more rapidly to design changes, pilot runs, and localized demand fluctuations.
Cost structures are also being reshaped by the interplay between resin pricing, fiber costs, and processing efficiency. While engineering resins such as polyamide and polybutylene terephthalate command premium pricing relative to commodity grades, their ability to deliver higher thermal and mechanical performance can justify the added material cost when part consolidation and metal replacement are achieved. Similarly, the choice between glass and carbon fiber reinforcement creates a spectrum of cost-performance options, allowing formulators to align material economics with the criticality of the application. Companies that can optimize fiber-matrix compatibility, minimize scrap rates, and integrate compounding with downstream conversion are gaining a meaningful cost advantage in a market where margin preservation is increasingly tied to process excellence rather than raw material arbitrage alone.
Thermoplastic Composites Market
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate concentration, with a handful of established compounders and specialty material suppliers capturing a meaningful share of differentiated, higher-performance formulations. Leading players have built their positions not simply on volume, but on technical depth, application engineering support, and the ability to deliver consistent quality across complex short fiber reinforced systems. The most successful companies treat compounding as a service capability, working closely with molders and design engineers to match fiber type, loading, and matrix selection to the functional, regulatory, and economic requirements of each part.
A representative group of companies illustrates the diversity of strategic approaches. One major U.S.-based manufacturer focuses on a broad portfolio of short fiber reinforced formulations with fiber loadings ranging from 10 to 50 percent, spanning commodity and engineering resins intended for semi-structural components. This breadth allows the company to serve a wide range of customers who need ready-to-process compounds with predictable behavior across multiple resin systems. Its competitive advantage lies in offering a library of standardized yet customizable options that reduce development time for parts requiring moderate reinforcement without the lead time of fully bespoke formulations.
A German producer takes a more bespoke approach, engineering tailor-made thermoplastic composites across a spectrum of fibers including glass, carbon, aramid, and natural fibers, and extending up to high-performance polymer matrices. This strategy positions the company in applications where standard compounds are insufficient and where performance, chemistry compatibility, or extreme environmental resistance dictate a custom solution. Its differentiation stems from deep formulation expertise and the ability to adjust fiber-matrix interactions for demanding conditions, making it a preferred partner for engineering teams that require precise control over material behavior.
A U.S.-based supplier specializing in short glass fiber reinforced compounds, offering chopped and milled glass fibers in a range of lengths across commodity and engineering thermoplastics, emphasizes structural and high-performance part solutions. This focus on controlled fiber geometry and consistent dispersion supports applications where predictable mechanical output and processing stability are critical. The company’s positioning reflects a practical, application-oriented approach that appeals to manufacturers seeking reliable reinforcement without the need for extensive material re-engineering.
The competitive environment is evolving along multiple vectors. Consolidation activity is expected to intensify as larger players pursue capability expansion, geographic reach, and access to specialized formulation know-how. At the same time, market differentiation is becoming more granular; companies are unlikely to win on price alone because the value proposition increasingly depends on engineering support, consistent quality, and the ability to solve application-specific challenges. New entrants and niche specialists may find openings in high-growth subsegments that require uncommon fiber combinations, bio-based or recycled content, or exceptional processing characteristics for advanced molding technologies. Ultimately, the market is moving toward a structure where scale provides cost leverage, but technical service and formulation agility determine customer loyalty and premium positioning.
Future Outlook: Trends and Commercial Implications
The next three to five years are likely to be defined by a tightening integration between material design and application engineering. Short fiber reinforced thermoplastic composites will increasingly be specified as part of optimized multi-material systems rather than as standalone replacements. This will elevate the importance of simulation-driven material selection, where finite element analysis and process modeling guide fiber loading, orientation, and matrix choice before tooling is committed. Suppliers that offer validated data packages, application notes, and process window guidance will be better positioned to shorten development cycles and reduce the risk of redesign.
PW Consulting Chemical & Energy Research Center
Sustainability and circularity will shift from aspirational goals to procurement requirements. Buyers will increasingly request evidence of recyclability, recycled content, and reduced carbon intensity, and materials that can integrate recovered fibers or bio-derived reinforcements without sacrificing performance will capture premium interest. Commercial opportunities will emerge for compounders that can deliver certified, drop-in sustainable formulations compatible with existing molds and processing equipment, thereby removing the friction that often accompanies material substitution. There is also potential in design-for-disassembly architectures, where short fiber reinforced thermoplastics are selected specifically because they can be separated and reprocessed more readily than thermoset counterparts.
A third trend is the continued expansion of processing versatility, particularly around high-speed injection molding, extrusion, and hybrid manufacturing flows. Improved fiber length control and dispersion will allow molders to produce parts with more consistent mechanical properties and fewer defects, expanding the range of geometries that can be economically molded. This trend opens opportunities in sectors that value part complexity and consolidation, such as under-the-hood automotive components, electronic housings, and industrial equipment where weight, durability, and cost must be balanced simultaneously. The risk is that processing windows can become narrower as fiber loadings and matrix performance increase, so the commercial winners will be those that pair advanced compounds with clear processing guidance and technical support.
Potential risks include raw material cost spikes, especially if fiber or resin supply tightens in key regions, and regulatory divergence that complicates global product rollouts. Another uncertainty lies in the pace of recycling infrastructure development; if post-industrial and post-consumer recovery systems do not scale in line with material adoption, circularity claims may remain limited to closed-loop or industrial scrap scenarios, constraining the breadth of sustainability-driven demand. Companies that diversify fiber and resin sources, invest in application-specific validation, and build transparent sustainability data will be better insulated against these uncertainties.
Strategic Actions for Decision-Makers
For Manufacturers and Compounders
Prioritize formulation agility as a core competitive asset. The ability to rapidly adjust fiber type, length, loading, and surface treatment in response to application requirements will differentiate suppliers in a market where standard compounds face increasing price scrutiny. Investing in compounding process control, dispersion quality, and consistent lot-to-lot performance will reduce customer risk and strengthen repeat business. Manufacturers should also expand technical service capabilities so that material recommendations are tied directly to part design, processing conditions, and end-use environment, not merely to generic property tables.
Develop a clear sustainability roadmap that connects material choices to verifiable lifecycle benefits. This includes exploring recycled and bio-based fiber options, documenting recyclability and recovery pathways, and aligning product offerings with the procurement criteria that OEMs and industrial buyers are beginning to enforce. A credible sustainability position can become a differentiator in bids where performance is comparable but environmental attributes influence selection.
For Investors
Focus on companies that combine scale with technical differentiation rather than volume alone. In a market where margin preservation depends on formulation expertise, application support, and process efficiency, businesses that can command premium pricing through value-added services are more resilient than undifferentiated commodity players. Pay attention to capabilities in high-performance matrices, hybrid fiber systems, and sustainable content, as these are likely to command stronger demand in segments pursuing lightweighting and circularity simultaneously.
Assess supply chain resilience and geographic positioning as part of the investment thesis. Regional compounding assets, diversified feedstock access, and strong customer technical relationships reduce exposure to logistics disruptions and price volatility. Investors should also evaluate the breadth of application exposure, since a diversified demand base provides stability when individual verticals face cyclical pressure or regulatory shifts.
Worldwide Advanced Thermoplastic Composite Market
For Procurement and Sourcing Leaders
Treat short fiber reinforced thermoplastic selection as a system-level decision rather than a simple material swap. Engage early with compounders and converters to align fiber loading, matrix choice, and processing parameters with part geometry, performance targets, and cost objectives. Early collaboration reduces the risk of suboptimal properties, rework, or processing bottlenecks that can erode the apparent cost advantage of a reinforcement strategy.
Require transparent data on processing windows, mechanical consistency, and sustainability attributes. Specification documents should encompass not only baseline mechanical properties but also tolerance to processing variation, moisture sensitivity where relevant, and available recycled or bio-based content options. Building these requirements into procurement criteria encourages suppliers to compete on overall value, including reliability and lifecycle performance, rather than on unit price alone.
For organizations seeking a more detailed segmentation view, competitive benchmarking, and tailored scenario planning across specific resin systems, fiber types, applications, and regional dynamics, the full PW Consulting research report provides the granular data and customized guidance needed to translate these strategic themes into concrete decisions.
For detailed analysis of this topic, please visit the official page: Short Fiber Reinforced Thermoplastic Composite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stone Paper Market: Why 6.5% CAGR and Packaging Demand Redefine the 2032 Outlook
By pmarketresearch, 2026-09-21
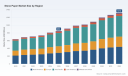
The Stone Paper Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Core Challenges
The stone paper market has evolved from a niche sustainable material into a measurable commercial segment with clear growth trajectory. Valued at 640.0 million in 2020, the market expanded to 737.24 million by 2023 and reached 850.0 million in 2025, reflecting a compound annual growth rate of approximately 6.5 percent through 2032. By the end of the forecast period, revenue is projected to approach 1.3 billion, signaling sustained commercial momentum rather than short-term experimentation. This trajectory is anchored in a tangible shift away from conventional pulp-based and petroleum-derived alternatives, particularly in application areas where durability, moisture resistance, and reduced fiber dependency align with procurement priorities.
The composition of demand further clarifies where commercial attention is concentrating. Packaging-related uses represent the largest application share, followed by labeling and self-adhesive formats, indicating that stone paper is increasingly evaluated not as a general-purpose substitute but as a purpose-fit material for specific functional and sustainability requirements. On the supply side, the market is moderately consolidated. The top three participants account for roughly 35 percent of revenue, while the top five collectively hold just above 52 percent. This concentration suggests that scale advantages, formulation expertise, and regulatory readiness are becoming differentiating factors, even as regional demand continues to diversify across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the market is navigating several structural pressures that will shape profitability and adoption speed over the next few years.
The first challenge lies in cost arithmetic and raw material sensitivity. Stone paper does not eliminate cost exposure; it shifts it. Production depends on mineral fillers and resin systems, meaning margin stability is tied to feedstock pricing and energy inputs rather than fiber markets. When input costs rise, manufacturers must absorb volatility or pass it through to buyers who may still compare stone paper against established alternatives on price alone. This creates a persistent tension between sustainability positioning and commercial competitiveness, especially in price-sensitive segments where environmental claims must be matched by total cost-of-ownership logic.
The second challenge is performance perception versus application reality. Stone paper offers distinct advantages in waterproofing, durability, and tree-free production, but it is not a universal replacement for every paper grade. Adoption depends on matching the material to the right use case, printing conditions, converting requirements, and end-of-life pathways. Overgeneralization can create disappointment in contexts where stone paper underperforms expectations, while selective deployment can build credible reference accounts and repeat demand. The market is therefore moving through an inflection point where technical education and application-specific validation matter as much as regulatory tailwinds.
The third challenge is regulatory and standards complexity. The same policies that accelerate interest in stone paper also raise the bar for substantiation. Extended producer responsibility frameworks, single-use packaging obligations, and recycling-target-driven procurement increasingly require documented environmental performance rather than broad eco-friendly positioning. In practice, this means manufacturers and buyers must navigate varying regional expectations, verify food-contact suitability where relevant, and ensure that sustainability claims hold up under procurement scrutiny. Companies that treat compliance as a core capability rather than a backend activity are better positioned to convert demand into durable contracts.
Core Drivers of Market Change
The expansion of the stone paper market is not driven by a single force. It is being shaped by overlapping technical, regulatory, behavioral, and supply-side dynamics that reinforce one another in specific application spaces.
Technological Innovation and Material Refinement
Material formulation remains the most direct lever of market progress. Recent developments point to a pattern of incremental but commercially meaningful refinement rather than sudden breakthrough rhetoric. For example, Taiwan Lung Meng completed installation of an advanced production line that reduced carbon footprint by 15 percent while improving efficiency, reinforcing that process optimization is becoming a competitive necessity as buyers evaluate environmental impact alongside operational performance. Similarly, TBM expanded its LIMEX-based offerings with a sheet designed for global packaging applications, emphasizing durability and sustainability in a format that aligns with converting and handling requirements. These moves matter because they bridge the gap between laboratory-level green promise and production-ready reliability.
At the same time, product launches are becoming more application-specific. Shenzhen Stone Paper introduced wholesale stone powder synthetic paper for vegetable packaging in the printing and packaging industry, illustrating how stone paper is being tailored to fresh-produce and food-adjacent contexts where moisture resistance, printability, and material safety are critical. This kind of targeted innovation increases the likelihood of adoption because it reduces the burden on buyers to adapt the material to their processes. The broader lesson is that stone paper's commercial relevance is increasing as suppliers narrow the gap between material properties and real-world packaging needs.
Policy and Regulatory Dynamics
Regulatory pressure is acting as a demand catalyst, particularly in regions where packaging waste and single-use materials are being re-priced through policy. Extended producer responsibility policies for packaging and printed paper in North America and Europe are encouraging organizations to evaluate stone paper as a plastic alternative that can support recycling targets and reduce single-use plastic waste. In parallel, California's EPR regulations for single-use packaging require producers to bear recycling costs, accelerating adoption of lower-impact alternatives by changing the economic calculus of material selection.
These developments do not automatically translate into demand, but they alter procurement logic. When producers internalize end-of-life costs, materials with lower embedded environmental liability become more attractive in business cases that previously favored the cheapest upfront option. This regulatory context is especially relevant for packaging and labeling applications, where compliance exposure is high and sustainability commitments are increasingly tied to measurable policy outcomes rather than voluntary branding.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand is also being reshaped by procurement behavior. Corporate buyers are increasingly treating sustainable packaging as an operational requirement rather than a differentiator, particularly when customer expectations, retail specifications, or internal targets push them toward reduced plastic use and lower environmental impact. Stone paper is benefiting from this shift because it can be presented as a tree-free, waterproof, and durable option with clear narrative appeal, especially in labeling, retail packaging, and industrial applications where material performance must coexist with sustainability storytelling.
Importantly, demand growth is strongest where the value proposition is concrete. Labeling and adhesive-backed formats, for instance, benefit from stone paper's durability and moisture resistance, while packaging applications gain from its alternative-to-plastic positioning. This suggests that adoption will continue to be opportunistic and segment-specific rather than uniform, with the most successful deployments tied to contexts where performance and policy alignment reinforce each other.
Supply Chain and Cost Structure Dynamics
The cost environment for stone paper production is influenced by the pricing of key raw materials, especially calcium carbonate. Recent pricing signals show meaningful regional variation, with calcium carbonate prices in the USA reaching 437 USD per metric ton in March 2026, the European price index averaging 0.33 USD per kilogram in May 2026, and Chinese prices at 317.10 USD per metric ton FOB in April 2026. These differences matter because they shape regional competitiveness and sourcing strategy.
Asian-based producers, for example, benefit from comparatively lower feedstock costs, which can support price competitiveness in export-oriented or regionally focused operations. European and North American producers, by contrast, must manage higher input costs while still meeting local regulatory and customer expectations. The net effect is that supply chain strategy is becoming a differentiator: companies that secure stable feedstock access, optimize formulation ratios, and manage energy intensity are better positioned to protect margins without sacrificing performance. In this environment, cost leadership is less about raw price cutting and more about input stability, process efficiency, and formulation discipline.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small group of focused manufacturers with differentiated positioning, alongside ongoing room for specialization and regional expansion. Taiwan Lung Meng, TBM, and Shenzhen Stone Paper each illustrate a different pathway to commercial relevance.
Strategic Positioning and Differentiation
Taiwan Lung Meng is positioned around tree-free, waterproof stone composite material based on calcium carbonate and non-toxic resin, serving packaging, labels, and stationery. Its Cradle-to-Cradle certification and export presence across more than 40 countries indicate a strategy rooted in verified sustainability credentials and international reach. In a market where claims must withstand procurement scrutiny, certification and export scale can function as trust multipliers.
Worldwide Flexible Stone Market
TBM is building its case around LIMEX mineral paper for packaging, with emphasis on food and non-food applications and eco-friendly properties. Its recent activities suggest a dual strategy: expanding product formats for global packaging use while also engaging broader corporate decarbonization ecosystems. The memorandum of understanding with Vietnam's FPT Group in August 2025, aimed at supporting corporate decarbonization efforts, reflects an approach that connects material offering with wider sustainability programs rather than treating stone paper as a standalone product transaction.
Shenzhen Stone Paper is pursuing customization and food-contact-safe formulations, targeting industrial and retail packaging with rich mineral paper and high-durability labels. Its wholesale stone powder synthetic paper for vegetable packaging indicates a strategy focused on application-specific solutions, where formulation control and customization can create defensible accounts in niche but commercially meaningful segments.
Market Structure and Evolution Trends
The market is likely to evolve along three interconnected lines. First, consolidation pressure may increase as scale, compliance readiness, and cost control become more important, especially in applications where buyers require dependable supply and documented performance. Second, segmentation will probably deepen, with more specialized offerings for food packaging, labeling, and industrial uses, because generic stone paper positioning is increasingly insufficient for complex procurement decisions. Third, new entrants may find traction not by challenging incumbents directly across all applications, but by targeting specific regional cost advantages, formulation needs, or niche packaging requirements.
This does not imply a winner-take-all structure. Instead, it suggests a landscape where advantage accrues to companies that can combine credible environmental credentials, application-fit formulation, and stable input economics. SMEs and regional players can still compete by serving localized demand or specialized converting needs, while larger or more globally connected participants can leverage certification, export reach, and process efficiency.
Future Outlook: Trends and Commercial Implications
Over the next three to five years, the stone paper market is likely to be shaped by trends that reward precision, credibility, and supply chain discipline.
Trend 1: Application-First Adoption Will Outpace Broad Substitution Narratives
The market will probably move further toward use-case-led deployment. Packaging, labeling, and adhesive applications will continue to generate the strongest pull because they align with stone paper's functional strengths and with regulatory pressure on plastic alternatives. Broad claims that stone paper can replace conventional paper across the board will become less persuasive as buyers demand evidence in specific conditions. Commercially, this creates opportunity for suppliers and end-users who invest in application validation, pilot programs, and reference deployments rather than relying on category-level sustainability messaging.
PW Consulting Chemical & Energy Research Center
Trend 2: Regulatory Pressure Will Keep Raising the Stakes for Substantiation
Policy momentum in packaging and printed paper is expected to intensify the need for credible documentation. Extended producer responsibility and single-use packaging regulations will continue to shift cost considerations toward materials that support recycling targets and reduce disposal liability. This will advantage participants that can clearly articulate environmental performance, food-contact suitability where needed, and recycling or end-of-life compatibility. The commercial implication is that sustainability claims will increasingly need to be operationalized into procurement specifications, not just marketing narratives.
Trend 3: Regional Cost Dispersion Will Shape Sourcing and Competitive Positioning
Because calcium carbonate pricing varies by region, competitive dynamics will remain geographically uneven. Asian producers may retain feedstock cost advantages, while North American and European players will need to compete on efficiency, certification, local compliance alignment, and service differentiation. Procurement teams may also increasingly consider regional sourcing as part of broader supply chain resilience and carbon-reduction strategies. For investors and manufacturers, this means that feedstock access, formulation control, and regional regulatory fit will be central to margin stability and market access.
Worldwide Natural Stone Market
Potential risks and uncertainties should not be understated. Raw material price volatility can still compress margins if not managed through contracts, formulation adjustments, or efficiency gains. Performance misapplication remains a risk if stone paper is positioned where it does not fit technical requirements. In addition, the regulatory environment can evolve in ways that change the relative attractiveness of different materials, especially if recycling infrastructure, compostability rules, or packaging compliance definitions shift. These uncertainties do not undermine the market's direction, but they do require active monitoring and scenario planning.
Strategic Implications for Decision-Makers
For Manufacturers and Material Suppliers
- Prioritize application-specific differentiation. Develop formulations and product formats that solve concrete packaging, labeling, or adhesive challenges rather than competing on generic eco-friendly positioning.
- Treat process efficiency as a market-facing capability. Production improvements that reduce carbon footprint and improve yield are not just internal gains; they support pricing resilience and customer trust in a market where both cost and sustainability claims are scrutinized.
- Strengthen documentation and compliance readiness. Certification, food-contact safety where relevant, and clear end-of-life or recycling alignment can become decisive in procurement decisions, especially under extended producer responsibility and single-use packaging obligations.
For Investors and Strategic Backers
- Focus on players with defensible feedstock strategy and formulation expertise. Cost volatility and performance fit are the principal swing factors, so businesses that can manage input economics and tailor material properties to real applications are more likely to sustain competitiveness.
- Watch for consolidation and specialization signals. Moderately concentrated markets with clear application leadership may present acquisition, partnership, or capacity-extension opportunities, especially where regional cost structures or certification capabilities differ.
- Assess regulatory exposure by region. Procurement shifts driven by EPR and single-use packaging rules can accelerate adoption in some markets faster than others, creating uneven but potentially high-value opportunities.
For Procurement and Business Leaders Evaluating Stone Paper
- Match the material to the task. Evaluate stone paper against the specific functional requirements of the application, including moisture exposure, converting needs, printability, durability, and end-of-life expectations, rather than adopting it as a blanket paper replacement.
- Use total cost and compliance logic in the business case. Where recycling costs, single-use obligations, or packaging compliance raise the cost of conventional options, stone paper's value may be strongest when assessed across the full procurement and disposal picture.
- Demand evidence and reference use cases. Ask for application-appropriate testing, food-contact compatibility where relevant, and documented environmental performance to ensure that procurement decisions are based on verifiable attributes.
Conclusion
The stone paper market is moving from early-stage curiosity to a more structured commercial segment defined by application fit, regulatory pressure, and input economics. Growth to nearly 1.3 billion by 2032 is plausible within the current trajectory, but the more important question for decision-makers is not whether the market is expanding, but where expansion will be most profitable and durable. The strongest opportunities are likely to emerge where material performance, sustainability substantiation, and regional cost dynamics align in packaging, labeling, and adhesive applications. Companies that build differentiation through formulation, process efficiency, certification, and targeted use-case validation are better positioned to convert momentum into repeatable commercial advantage. For leaders seeking to act on these dynamics with greater precision, more granular segmentation data and customized strategic guidance will be essential to move from directional confidence to execution-ready decisions.
For detailed analysis of this topic, please visit the official page: Stone Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrazine Hydrate Market: Why the 5.5% CAGR Shift Reshapes 2032 Forecasts
By pmarketresearch, 2026-09-21
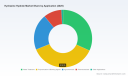
Hydrazine Hydrate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global hydrazine hydrate market has demonstrated steady expansion over the 2020–2025 period, driven by consistent demand across industrial, agricultural, and specialty chemical applications. Valued at approximately USD 215.0 million in 2020, the market grew to an estimated USD 280.6 million by 2025. Forward-looking projections indicate a compound annual growth rate of 5.5 percent through 2032, with revenues expected to approach USD 408.8 million by the end of the forecast horizon. This trajectory reflects a maturing but still dynamic market where volume growth is increasingly intertwined with regulatory adaptation and technological refinement rather than raw demand expansion alone.
While the aggregate figures point to resilience, the underlying structure reveals a market navigating several inflection points. First, regulatory scrutiny has intensified significantly across major jurisdictions. Hydrazine is classified as a substance of very high concern under the European Union REACH framework, placing producers and downstream users under continuous pressure to maintain authorization dossiers and justify continued use. This regulatory posture does not eliminate demand, but it raises compliance costs and compresses margins for operators with weaker regulatory infrastructure. Second, logistics and handling constraints remain a persistent bottleneck. Transporting hydrazine hydrate requires insulated, pressure-rated containers and certified handlers under United Nations Model Regulations, which limits supply chain flexibility and increases operational overhead for regional distributors and end-users alike. Third, feedstock cost volatility has emerged as a structural challenge. Recent periods have seen upstream raw material costs for hydrazine hydrate production rise by roughly 15 percent, squeezing profitability and forcing manufacturers to recalibrate pricing strategies without alienating price-sensitive industrial customers.
These challenges are not merely operational friction points; they are reshaping competitive boundaries. Companies that can absorb compliance costs, secure reliable feedstock contracts, and maintain rigorous handling standards are gradually separating themselves from smaller or less integrated players. The market is therefore transitioning from a capacity-driven growth phase to one where operational sophistication, regulatory readiness, and supply chain resilience determine long-term positioning. For decision-makers, the practical implication is clear: market entry or expansion now requires a holistic view of compliance, logistics, and input cost management rather than a narrow focus on production volume or end-market demand alone.
Key Drivers Shaping Market Direction
Technological Innovation and Product Specialization
Technological advancement in hydrazine hydrate is less about breakthrough chemistry and more about precision, purity, and application-specific differentiation. Industry participants have increasingly moved toward high-purity formulations tailored for demanding sectors such as aerospace and specialty synthesis. In February 2024, LANXESS AG introduced a high-purity 100 percent hydrazine hydrate variant specifically developed for aerospace applications, signaling a deliberate shift toward niche, performance-driven segments where tolerance for impurities is extremely low and customers are willing to pay for reliability. Alongside product refinement, trade platforms have become conduits for showcasing integrated value propositions. In May 2025, Arkema S.A. and LANXESS AG both participated in Chemspec Europe 2025, highlighting hydrazine hydrate alongside complementary chemicals such as thionyl chloride for crop protection agent synthesis. These engagements underscore a broader trend: manufacturers are positioning hydrazine hydrate not as a standalone commodity but as a critical input within larger synthetic and formulation workflows. For businesses, this implies that competitive advantage increasingly comes from offering application-ready specifications, technical support, and integrated chemical solutions rather than competing solely on base grade volume.
Regulatory and Policy Environment as a Market Filter
Regulatory dynamics are functioning as a market filter rather than a blanket constraint. In the United States, domestic rules were harmonized with updated international standards in 2024, prompting relabeling requirements and additional training across the supply chain. While such measures raise short-term operational burdens, they also formalize handling expectations and reduce variability in compliance practices. In parallel, EU REACH continues to require producers and users to prepare costly authorization dossiers, which disproportionately affects operators with limited regulatory resources or fragmented application portfolios. The practical effect is a consolidation of compliant supply bases and a higher barrier for new entrants who lack established regulatory track records. For procurement and sourcing leaders, this environment rewards long-term partnerships with manufacturers that can demonstrate consistent authorization status, transparent documentation, and robust safety protocols. For producers, the strategic imperative is to invest in regulatory capacity early, since compliance credentials are becoming as commercially relevant as technical specifications.
Demand-Side Evolution in End-Use Industries
Demand for hydrazine hydrate is being shaped by evolving priorities within core application sectors. Water treatment continues to be a substantial demand center, supported by ongoing infrastructure maintenance and chemical dosing requirements in industrial and municipal systems. At the same time, polymerization and blowing agent applications represent a significant share of consumption, reflecting the material’s role in foam generation and specialty polymer processing. Agrochemical synthesis remains another critical driver, where hydrazine hydrate serves as a key inorganic input for crop protection agents and related intermediates. Pharmaceutical manufacturing, while smaller in absolute terms, demands higher specifications and more controlled supply conditions. The common thread across these segments is a growing preference for suppliers who can provide grade consistency, technical documentation, and reliable delivery schedules. End-users are increasingly less willing to accept variability in feedstock quality or unpredictable lead times, particularly when production downtime or formulation failures carry high costs. This behavioral shift is pushing manufacturers to strengthen quality assurance systems, expand technical service capabilities, and align production planning more closely with downstream consumption patterns.
Supply Chain and Cost Structure Realignment
The cost structure of hydrazine hydrate production is undergoing noticeable realignment. Upstream feedstock costs have risen by approximately 15 percent in recent periods, placing pressure on conversion economics and prompting manufacturers to explore procurement optimization, energy efficiency improvements, and strategic inventory management. At the same time, shipping and handling requirements continue to add layered costs, particularly for long-distance distribution and cross-border transactions. These factors are encouraging a re-evaluation of network design, with some operators consolidating regional supply points, investing in specialized packaging, and pursuing long-term feedstock agreements to reduce exposure to spot price swings. For commercial teams, the implication is that cost competitiveness is increasingly determined by supply chain architecture as much as by production efficiency. Businesses that can stabilize input costs, optimize logistics, and maintain buffer capacity for demand fluctuations are better positioned to protect margins while preserving customer relationships in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The competitive structure of the hydrazine hydrate market is moderately concentrated, with the top three companies accounting for approximately 26.8 percent of market revenue and the top five collectively representing about 29.4 percent. This concentration level indicates a landscape where established players hold meaningful share but where fragmentation still exists, particularly across regional distribution and specialty grades. The presence of multiple Japanese manufacturers alongside European incumbents reflects a geographically diverse supply base, with each group emphasizing different strengths in product specification, application focus, and regional service networks.
Arkema S.A., headquartered in France, offers hydrazine hydrate at 100 percent concentration along with a full range of dilutions and derivatives, positioning itself as a flexible supplier for polymer foam blowing agent applications and active ingredient synthesis. This breadth allows Arkema to serve customers who require customized dilution levels or derivative formats rather than a one-size-fits-all product. LANXESS AG, based in Germany, supplies hydrazine hydrate as a key inorganic input for the synthesis of crop protection agents and other agrochemical applications. Its emphasis on agrochemical synthesis aligns with one of the market’s most consistent demand streams, and its February 2024 launch of a high-purity 100 percent variant for aerospace applications demonstrates a willingness to extend into highly specification-sensitive segments. Otsuka-MGC Chemical Company, Inc., based in Japan, is recognized as the largest global maker of hydrazine hydrate and the only manufacturer based in Japan, giving it a distinctive domestic production advantage and a broad industrial application footprint. Nippon Carbide Industries Co., Inc., also in Japan, focuses on hydrazine hydrate as a synthetic raw material for pharmaceutical and agrochemical fields, while also supplying boiler cleaning chemicals, which diversifies its end-use exposure. Japan Finechem Co., Inc. produces hydrazine hydrate through its Sakaide plant operations, adding further capacity and regional depth within the Japanese supply base. Kanto Chemical Co., Inc. supplies hydrazine hydrate in technical and analytical grades, catering to customers who require precise grade differentiation for laboratory, quality control, and specialized industrial use.
Sodium Borohydride Market
The strategic positioning of these leaders reveals several differentiating advantages. First, product range flexibility matters. Companies that can supply both concentrated and diluted formats, plus relevant derivatives, reduce the need for customers to manage multiple suppliers for related grades and applications. Second, application specialization is increasingly valuable. Firms that align their capabilities with high-priority end-use areas such as agrochemicals, aerospace-grade purity, or pharmaceutical synthesis can command stronger customer loyalty and more resilient demand. Third, regional manufacturing presence can serve as a strategic asset, particularly where handling regulations, logistics complexity, and customer service expectations vary by market. Japanese manufacturers, for example, benefit from domestic production capabilities that support stable supply and localized technical support, while European players leverage integrated chemical portfolios and established regulatory infrastructure.
Looking ahead, the market structure is likely to continue evolving through a combination of consolidation, specialization, and selective new entry. Regulatory compliance costs and feedstock volatility will make it harder for under-resourced entrants to compete on undifferentiated volume, which may encourage 인수합병 activity or strategic partnerships among mid-tier players seeking scale and compliance capacity. At the same time, the growing importance of specialized grades and application-specific support creates space for focused competitors who can outperform on quality, documentation, and technical service rather than on price alone. New entrants that bring differentiated capabilities—such as advanced purification processes, specialized packaging, or strong regional regulatory readiness—could capture niche positions, but broad-based commodity competition is likely to intensify only where regulatory and logistics barriers are lower. For incumbents, the strategic task is to defend share in core applications while selectively expanding into higher-value specifications where customer willingness to pay is stronger and switching costs are higher.
Worldwide Potassium Carbonate Hydrate Market
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape how the hydrazine hydrate market evolves and where commercial opportunities emerge. The first trend is the continued elevation of regulatory and safety compliance as a core competitive dimension. As authorization requirements, labeling standards, and handling protocols become more entrenched, suppliers with mature compliance systems will gain an advantage in securing long-term contracts with risk-averse end-users. This creates an opportunity for companies to differentiate through documented safety performance, transparent regulatory status, and robust technical support, particularly in regions where compliance expectations are tightening. Businesses that treat compliance as a strategic capability rather than a cost center are better positioned to retain customers and defend pricing during periods of input cost pressure.
The second trend is the gradual shift toward higher-value, application-specific grades and integrated chemical solutions. Demand from sectors such as aerospace, pharmaceutical synthesis, and advanced agrochemical manufacturing is likely to sustain interest in high-purity and precisely specified products. This trend opens commercial pathways for suppliers that can offer tailored concentrations, reliable analytical certification, and close technical collaboration with downstream formulators. It also suggests that pure commoditization pressure may be partially offset by segmentation, where customers in specification-sensitive applications place greater weight on consistency and support than on marginal price differences. Companies that can clearly articulate grade performance, handle documentation efficiently, and align production with customer qualification requirements are more likely to capture these higher-margin positions.
PW Consulting Chemical & Energy Research Center
The third trend is supply chain resilience and cost management becoming central to market competitiveness. With feedstock costs elevated and logistics requirements demanding specialized handling, businesses will continue to optimize procurement, inventory, and distribution strategies. This may lead to more long-term feedstock agreements, regional supply consolidation, and investment in packaging and transport capabilities that reduce downtime and compliance risk. The commercial opportunity here lies in building supply arrangements that provide predictability for both suppliers and customers, especially in applications where production continuity is critical. At the same time, potential risks remain. Regulatory decisions could further constrain certain uses or increase documentation burdens, feedstock cost spikes could compress margins if unable to be passed through, and logistics disruptions could affect delivery reliability in tight markets. Decision-makers should therefore monitor regulatory calendar developments, input cost trends, and regional handling requirements as part of ongoing strategic planning.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to strengthen regulatory readiness, product differentiation, and supply chain stability in tandem. Building and maintaining rigorous authorization documentation, expanding high-purity or application-specific offerings, and securing more stable feedstock arrangements can help protect margins while improving customer retention. Companies should also evaluate whether their current grade portfolio matches the direction of end-use demand, particularly where aerospace, agrochemical, and pharmaceutical customers increasingly expect precise specifications and reliable technical support. Investing in handling and packaging capabilities that reduce logistics friction can further enhance competitiveness, especially in markets where certified transport and storage are limiting factors.
For investors, the key is to assess exposure not only to top-line demand growth but also to the regulatory and cost-structure dynamics that determine profitability. Businesses with strong compliance infrastructure, diversified application bases, and resilient logistics are better positioned to withstand feedstock volatility and regulatory pressure. Evaluation should consider whether a company’s product mix is shifting toward higher-value specifications, whether its regional presence supports stable service and compliance, and whether its cost management practices can absorb input price fluctuations without eroding competitive position. In a market where concentration is moderate and differentiation is increasing, long-term value is likely to accrue to operators that can combine scale with specialized capabilities rather than those competing purely on volume.
For procurement and sourcing leaders, the practical focus should be on supplier qualification, grade consistency, and supply continuity. Given the handling complexity and regulatory sensitivity of hydrazine hydrate, sourcing decisions should weigh documented authorization status, safety protocols, packaging standards, and delivery reliability alongside price. Building longer-term relationships with suppliers that can demonstrate stable compliance and technical support can reduce the risk of disruptions and specification mismatches, particularly in applications where production downtime or formulation issues are costly. Procurement teams should also monitor regional regulatory updates and logistics requirements, since changes in labeling, training, or transport standards can affect total landed cost and operational readiness.
As the hydrazine hydrate market continues to evolve through regulatory refinement, product specialization, and supply chain recalibration, the businesses that succeed will be those that treat these dynamics as strategic levers rather than external constraints. Detailed segmentation data, company-level assessments, and application-specific forecasts can provide the granularity needed to convert these trends into concrete sourcing, investment, and production decisions. For a more comprehensive view of regional breakdowns, application splits, competitive benchmarks, and forward-looking scenarios, the full PW Consulting research report offers a deeper evidence base and tailored guidance for specific strategic contexts.
For detailed analysis of this topic, please visit the official page: Hydrazine Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Eco-Friendly Beneficiation Reagents Market: Why Biodegradable Isolation From 2020–2032 Forecasts a 6.5% Growth Path
By pmarketresearch, 2026-09-18
Navigating the Green Shift: Strategic Insights for the Eco-friendly Beneficiation Reagents Market
Market Landscape and Core Challenges
The global market for eco-friendly beneficiation reagents has entered a phase of sustained expansion, reflecting the mining sector’s broader transition toward lower-impact processing. Over the 2020–2025 period, the industry experienced consistent revenue growth, propelled by incremental adoption of bio-based collectors, non-toxic frothers, and organic depressants. Current trajectories project steady compounding growth well into the early 2030s, signaling that sustainability is no longer a peripheral consideration but a structural requirement for mineral processing operations. The market’s evolution mirrors a broader industrial pivot: rather than treating environmental compliance as a cost center, leading operators increasingly view green reagents as enablers of process efficiency, tailings reduction, and long-term operational license continuity.
Despite this momentum, the industry faces a tightly coupled set of challenges that will shape competitive outcomes over the next decade. First, performance parity remains a persistent tension. Traditional reagents such as xanthates and fossil-derived collectors have decades of operational history, well-understood kinetics, and predictable cost structures. Replacing them with biodegradable collectors or bio-based pH modifiers often requires re-engineering flotation circuits, recalibrating dosage regimes, and retraining plant personnel. For many mid-tier and junior mining companies, the perceived operational risk of switching formulations outweighs the environmental benefits, especially when ore bodies are complex or recovery margins are thin.
Second, the regulatory environment is accelerating adoption but fragmenting demand signals across jurisdictions. Environmental discharge limits, aquatic toxicity standards, and corporate sustainability commitments are pushing procurement teams toward lower-toxicity alternatives. However, regulatory timelines, testing protocols, and compliance expectations differ markedly between established mining regions and emerging resource frontiers. This creates a dual challenge for reagent manufacturers: products must satisfy stringent European and North American chemical safety expectations while remaining cost-competitive and operationally practical in markets where processing infrastructure and waste management capacity vary widely.
General Reagents Market
Third, the supply chain for bio-based feedstocks introduces a new dimension of volatility. Renewable raw materials, including plant-derived oils, lignin-based intermediates, and fermentation-derived biosurfactants, offer compelling environmental profiles. Yet their availability, batch consistency, and pricing are subject to agricultural cycles, logistics constraints, and competing demand from other industrial sectors. For flotation chemical producers, building reliable bio-feedstock pipelines is as critical as formulation innovation. Companies that fail to secure scalable, traceable, and cost-stable inputs risk losing ground to competitors who can deliver consistently performing green reagents without supply disruptions.
Together, these dynamics suggest that the market is moving from early experimentation toward commercial validation. The question is no longer whether eco-friendly reagents will gain share, but which players can deliver the right combination of performance, regulatory alignment, supply reliability, and total cost of ownership.
Key Drivers Reshaping the Market
The expansion of eco-friendly beneficiation reagents is not being driven by a single force. It is the result of overlapping technological, regulatory, demand-side, and supply-side shifts that reinforce one another. Understanding these drivers is essential for companies deciding where to invest, what capabilities to build, and how to position products for different mining segments and geographies.
Technology Innovation and Formulation Breakthroughs
Advancements in green flotation chemistry are steadily narrowing the performance gap with conventional reagents. Research and commercial development increasingly focus on bio-based collectors, safer frothers, and organic depressants that can operate effectively in complex ore environments. Recent academic and industry reviews have introduced classification frameworks for green reagents based on biobased origin, biodegradability, and safer chemical profiles, providing a common language for evaluating alternatives beyond simple toxicity comparisons. This kind of structured assessment is helping procurement teams and process engineers move from qualitative sustainability claims to more rigorous performance benchmarking.
On the commercial side, major reagent developers are showcasing products aimed at both environmental improvement and process efficiency. Advanced collectors and energy-efficient coarse particle flotation formulations are being positioned to improve recovery while reducing energy intensity, particularly for base metals, lithium, nickel, and other minerals tied to the energy transition. At the same time, manufacturers are launching high-performance reagents for industrial minerals and phosphate processing that target higher recovery rates and lower dose requirements. These innovations matter because they reframe green reagents as dual-purpose tools: they address compliance and ESG objectives while also supporting recovery, throughput, and reagent economics.
Policy, Regulation, and the Compliance Accelerator
Regulatory pressure continues to be one of the most powerful catalysts for adoption. Stricter environmental rules and corporate sustainability targets are driving interest in biodegradable, low-toxicity, and bio-based flotation chemicals designed to reduce aquatic toxicity and meet discharge limits. In parallel, evolving chemical safety frameworks and regulatory support for low-toxicity alternatives are encouraging innovation in froth flotation chemistry. The practical effect is that compliance is increasingly shaping formulation priorities, not merely end-of-pipe waste management.
For mining companies, this regulatory momentum translates into procurement shifts and process redesign decisions. Reagents with improved toxicological profiles can reduce permitting friction, simplify wastewater handling, and support broader corporate decarbonization and biodiversity commitments. For reagent suppliers, the regulatory direction rewards products that can demonstrate measurable safety and environmental advantages while maintaining process reliability. The companies that benefit most are those able to align their innovation pipelines with emerging compliance expectations without over-indexing on regional regulatory niches that may not scale.
Demand-Side Shifts Across Mining Business Models
Demand for sustainable beneficiation reagents is being shaped by changing mining business models, ore quality trends, and investor expectations. Lower-grade resources and more complex ore bodies are prompting operators to seek reagents that improve selectivity and recovery without escalating chemical consumption or environmental burden. At the same time, precious metals and base metals mining operations face mounting scrutiny from investors, off-takers, and community stakeholders, all of whom are paying closer attention to water use, chemical discharge, and tailings footprints.
PW Consulting Chemical & Energy Research Center
This demand-side evolution is especially visible in application areas where processing efficiency and environmental risk intersect. Precious metals processing has long been a focus for non-toxic leaching alternatives, while base metals flotation continues to attract interest in collector and frother innovations that can improve recovery and reduce reliance on higher-impact chemistry. Iron ore processing and industrial minerals operations are also part of the equation, particularly where beneficiation decisions influence downstream competitiveness, residue management, and reputational exposure. The overarching trend is that buyers are increasingly evaluating reagents through a total-cost lens that includes compliance risk, operational flexibility, and ESG alignment rather than short-term price alone.
Supply Chain, Cost Structure, and Feedstock Realism
The commercial viability of eco-friendly reagents depends heavily on supply chain maturity and cost structure. Bio-based feedstocks and renewable intermediates can offer strong environmental credentials, but they also introduce variables that traditional chemical supply chains were not designed to manage. Feedstock availability, conversion yields, transportation costs, and supplier concentration can all affect final pricing and consistency. Lignin-based reagents derived from forest biomass and other renewable inputs illustrate both the promise and the complexity of this transition: they can provide biodegradable, non-toxic alternatives for sulfide ore flotation, but scaling them into routine plant use requires dependable sourcing and process validation.
Cost dynamics are further complicated by the need to justify switch-over expenses. Even when a green reagent offers attractive environmental attributes, mines will assess whether it can match recovery, reduce downtime, or lower downstream treatment costs. If the total operating impact is favorable, adoption accelerates. If the switch creates uncertainty in recovery or increases reagent consumption, adoption slows. This reality means that supply chain strategy and product design must advance together. Manufacturers that can stabilize feedstock access, control formulation variability, and demonstrate reliable plant performance are better positioned to convert regulatory and ESG interest into durable demand.
Competitive Landscape and Leading Strategies
The competitive picture in eco-friendly beneficiation reagents is defined by a mix of established chemical leaders, specialized innovators, and regional players targeting specific processing pain points. The market remains moderately concentrated, which gives larger players advantages in formulation scale, application support, and global distribution, while also leaving room for focused entrants with strong technical differentiation. The strategic question for incumbents is how to convert broad portfolios into credible green alternatives; for newer entrants, the challenge is how to prove performance and secure long-term supply commitments.
Worldwide Eco-Friendly Bitumen Market
Incumbents Building on Portfolio Breadth
Large diversified chemical companies are leveraging existing mining solutions portfolios to develop more sustainable flotation products. Nouryon, for example, offers a wide range of flotation collectors for minerals such as phosphate, iron ore, potash, and calcite, with an emphasis on reducing environmental impacts through product reformulation, including efforts to remove certain legacy surfactants and develop lower-impact options. Clariant has similarly built a mining solutions platform around collectors and frothers for sulfide ores, iron ore, phosphate, potash, and a growing set of transition minerals, with a focus on safer alternatives to conventional chemistry, coarse particle flotation, and reduced environmental footprint.
BASF and Syensqo reflect a comparable approach from complementary angles. BASF develops collectors, frothers, and modifiers designed to improve recovery and reduce dose rates while improving safety profiles and incorporating biodegradable options where feasible. Syensqo supports base and precious metals processing with flotation collectors, promoters, and frothers intended to improve sustainability profiles relative to more traditional chemistries while enabling more efficient mineral processing. Arkema, including its associated mineral processing assets, emphasizes enhanced selectivity and recovery through tailored depressants, collectors, frothers, and related products for phosphate, silica sand, iron beneficiation, and industrial minerals.
What distinguishes these players is not simply product volume, but the ability to pair formulation development with application engineering, testing support, and global reach. Their strategies typically center on offering multiple pathways for customers: improving existing circuits with better-performing variants, reducing chemical intensity, and transitioning to greener chemistries without abandoning process reliability. This breadth is a meaningful advantage when mines want to trial alternatives gradually rather than undertake full-scale re-engineering.
Specialized Players Targeting High-Value Problems
At the other end of the competitive spectrum, specialized companies are focusing on discrete but commercially important challenges. Several firms are developing cyanide-replacement leaching reagents for precious metals processing, aiming to provide low-toxicity, non-polluting alternatives with comparable or improved recovery in heap leaching, CIP, and CIL operations. This segment has attracted sustained attention because it directly addresses both environmental risk and process continuity in gold ore beneficiation.
Other innovators are pursuing more fundamental chemistry shifts. Biosurfactant-based additives and fermentation-derived solutions are being explored as ESG-friendly reagents to improve recovery from low-grade ores and tailings. These approaches can offer a different value proposition from conventional chemical formulations: rather than simply substituting one collector or frother for another, they may help unlock recovery from materials that are economically marginal under traditional processing conditions. If scaled effectively, such technologies could expand the economic horizon for both primary extraction and tailings reprocessing.
Market Evolution: Integration, Differentiation, and New Entrants
The competitive landscape appears to be evolving along several lines. First, incumbents with broad reagent portfolios are likely to continue consolidating technical services and application data, using their scale to reduce customer switching costs and accelerate trial-to-commercial pathways. Second, differentiation will increasingly depend on demonstrable attributes: biodegradability, safer chemical handling, reduced dose rates, improved recovery at lower energy intensity, and stronger environmental profiles. Products that can make these claims credible, backed by consistent supply and application evidence, will gain an edge over those competing primarily on price or general sustainability language.
Third, regional specialization remains important. Asia Pacific continues to represent a substantial revenue base, reflecting the scale and diversity of mining and mineral processing activity in the region. Latin America also represents a significant share of market value, driven by active mining economies and expanding mineral processing demand. North America, the Middle East and Africa, and Europe contribute additional, more varied demand profiles shaped by local mineral mixes, regulatory conditions, and processing infrastructure. Companies operating across these regions must navigate different ore types, operating practices, and compliance expectations, which makes localized technical support and flexible product design increasingly valuable.
Finally, the sector is likely to see continued entry by firms targeting specific gaps, such as cyanide alternatives, lignin-based collectors, or biosurfactant additives. Some of these entrants may remain niche players; others may become acquisition targets if their technologies prove scalable and align with the strategic priorities of larger chemical suppliers. The broader trajectory points toward a market where credibility, repeatability, and supply resilience matter as much as formulation novelty.
Future Trends and Commercial Implications
Looking ahead, three interconnected trends are likely to shape the eco-friendly beneficiation reagents market over the next three to five years.
The first trend is the gradual mainstreaming of green reagents in selective applications rather than blanket substitution. Adoption will likely accelerate where the value case is clearest: precious metals leaching substitutions, flotation circuits facing stringent discharge constraints, and processing routes where improved selectivity can reduce downstream costs or tailings burden. In other settings, adoption may proceed more slowly, especially where ore complexity or circuit design makes reformulation riskier. The commercial opportunity lies in targeting the right applications first and building proven performance records that can later be extended to adjacent use cases.
The second trend is deeper integration between formulation innovation and process optimization. Green reagents will increasingly be evaluated not only for their chemical profile, but also for how they interact with recovery targets, energy consumption, water management, and tailings behavior. Coarse particle flotation, lower dose regimes, and improved selectivity are all examples of directions that can blur the line between sustainability and operational efficiency. Companies that position products as part of a broader process improvement strategy, rather than as stand-alone chemical purchases, are likely to win stronger customer commitment.
The third trend is the growing importance of feedstock strategy and lifecycle credibility. As bio-based and biodegradable options become more prominent, procurement and technical teams will pay closer attention to raw material origins, supply consistency, and end-of-life behavior. This creates an opportunity for suppliers that can document renewable sourcing, maintain reliable production, and provide transparent performance data. It also introduces risk for players that depend on volatile feedstocks or cannot guarantee consistent quality across batches.
These trends collectively point to a market that will reward differentiation grounded in real operating value. The upside is significant for suppliers that can demonstrably improve recovery, reduce environmental exposure, and stabilize supply. The downside risk lies in over-promising on sustainability without delivering consistent performance, or in building business models around feedstocks and regulations that may shift faster than commercialization timelines.
Action Priorities for Decision Makers
For manufacturers and product developers, the immediate priority is to align formulation roadmaps with the applications where performance, compliance, and economics reinforce each other. Investment should favor chemistries and delivery models that reduce dose requirements, support safer handling, and can be validated in real flotation or leaching conditions. Equally important is securing supply chains for renewable or lower-impact feedstocks so that product claims can be sustained at commercial scale.
For investors, the most relevant signal is differentiation backed by repeatable customer outcomes. Opportunity exists in companies with strong application data, credible feedstock strategies, and clear relevance to high-stakes segments such as precious metals leaching, base metals flotation, and processing of ores tied to the energy transition. Caution is warranted where growth narratives rely primarily on regulatory optimism or broad sustainability messaging without evidence of process-level benefit and supply resilience.
For procurement and operations leaders in mining and mineral processing, the strategic task is to move beyond simple product substitution and evaluate green reagents within the context of circuit performance, water and tailings management, and long-term permitting exposure. Piloting should be structured to measure recovery, reagent consumption, handling safety, and downstream implications, not just environmental attributes. A disciplined evaluation framework can reduce switching risk while identifying reagent strategies that support both operational and sustainability goals.
Organizations seeking a more granular view of segmentation, regional demand patterns, application-level dynamics, and competitive positioning can benefit from a deeper benchmarking exercise. Detailed market data and customized strategic support are valuable for translating these high-level trends into concrete sourcing, investment, and product decisions. Readers looking for a fuller breakdown of market sizing, segmentation splits, and leading-company strategies are encouraged to consult the comprehensive PW Consulting research report for additional detail and tailored guidance.
For detailed analysis of this topic, please visit the official page: Eco-friendly Beneficiation Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Main-Chain Liquid Crystalline Polymer Market: How a 7.42% CAGR Reshapes Strategy Through 2032
By pmarketresearch, 2026-09-18
Main-Chain Liquid Crystalline Polymer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Structural Challenges
The main-chain liquid crystalline polymer (LCP) market has established itself as a critical enabler for high-performance engineering applications, driven by an unambiguous demand trajectory. Revenue expanded from approximately $1,024 million in 2020 to $1,466 million in 2025, and forward projections indicate sustained momentum toward $2,420 million by 2032. This trajectory translates to a compound annual growth rate of 7.42 percent across the 2026 to 2032 forecast horizon, reflecting a market that is no longer niche but structurally embedded in advanced manufacturing ecosystems. Growth is not evenly distributed across applications or geographies, yet the underlying expansion is anchored by sectors where dimensional stability, thermal resilience, and flow characteristics during precision molding are non-negotiable.
Despite the positive macro trajectory, the industry confronts several structural friction points that will define competitive positioning in the coming years. First, supply chain fragility around specialty monomers creates persistent cost and availability volatility. Purified terephthalic acid and hydroxybenzoate derivatives, which form the backbone of main-chain LCP chemistry, operate within constrained global supply networks. Limited supplier concentration, coupled with batch polymerization requirements, means producers cannot easily decouple from raw material price swings or logistical bottlenecks. This structural premium, often trading at roughly double the cost of high-temperature nylons, limits aggressive substitution in cost-sensitive applications while simultaneously reinforcing the material's value proposition where performance justifies expense.
Second, the regulatory environment is lengthening qualification cycles and raising compliance overhead. Updated chemical safety review frameworks in major markets, alongside evolving disclosure expectations under prevailing chemical strategies, require more extensive testing, traceability documentation, and lifecycle transparency for new LCP grades. These requirements are not peripheral; they directly impact time-to-market for formulation adjustments, additive packages, and biologically balanced variants. For high-volume electronics and mobility customers operating on tight product launch schedules, extended qualification timelines create planning uncertainty and can delay adoption even when technical performance is compelling.
Liquid Crystal Polymers (LCPs) Market
Third, the market is transitioning from performance-driven acceptance to sustainability-conditioned procurement. Original equipment manufacturers and tier suppliers increasingly expect certified green feedstocks, mass-balance traceability, and circular chemistry options alongside thermal and mechanical specifications. This shift does not eliminate demand for conventional main-chain LCPs, but it reshapes purchasing criteria and rewards producers who integrate environmental credentials into product architecture rather than treating them as aftermarket messaging. The convergence of raw material constraints, regulatory elongation, and sustainability-conditioned demand creates a market where scale alone is insufficient. Competitive advantage is migrating toward formulation agility, feedstock diversification, and qualification speed.
Key Drivers Shaping Market Trajectory
Technical Innovation and Formulation Breakthroughs
Material science progress remains the most direct catalyst for expanded LCP adoption. Recent chemistry refinements have focused on balancing high-heat resistance, flame retardancy, and injection flow without sacrificing dimensional tolerances. For high-frequency electronics, 5G infrastructure, and electric vehicle power management, formulators have engineered grades that maintain signal integrity and thermal stability while enabling thinner wall sections and higher component density. The ability to tailor monomer ratios, modify end-group terminations, and integrate specialty additives without disrupting liquid crystalline ordering has extended LCP relevance into applications that previously relied on metal substitution or lower-performance thermoplastics.
A notable example of formulation direction is the introduction of biomass-balanced grades that preserve performance while addressing procurement decarbonization requirements. By applying mass-balance accounting to bio-derived feedstocks, producers have delivered LCP variants that maintain thermal and mechanical characteristics while providing a credible pathway for customers seeking scope reductions in their supply chain emissions. This development signals a broader shift: sustainability is increasingly being engineered into polymer architecture rather than layered on through end-of-life messaging alone.
Policy and Regulatory Environment
Regulatory frameworks are actively reshaping how LCP grades are developed, qualified, and deployed. Chemicals legislation in major jurisdictions continues to tighten testing protocols, disclosure expectations, and substance evaluation timelines. For LCP producers, this means new grades and modified formulations face longer qualification cycles, and customers require more visible documentation around chemical safety, traceability, and compliance status. The operational effect is twofold: it raises barriers to rapid product churn and rewards companies with mature regulatory infrastructure, standardized testing data packages, and established customer qualification relationships.
Simultaneously, policy emphasis on safer chemistries and circular solutions is altering feedstock preferences. Procurement teams increasingly weigh certified feedstocks, mass-balance traceability, and lower-impact sourcing as material selection criteria, particularly in automotive, electronics, and medical supply chains. This environment favors producers that can deliver both performance assurance and verifiable sustainability credentials, while it pressures laggards who must retrofit compliance or feedstock strategy after product architecture decisions are already locked.
Liquid Crystal Polymer (LCP) Films and Laminates Market
Demand-Side Evolution in Key End-Use Markets
Demand is shifting not only in magnitude but in specification. Electrical and electronics applications continue to anchor volume, driven by miniaturization, high-speed data transmission, and thermal management requirements in consumer devices, network infrastructure, and advanced driver-assistance systems. Automotive demand is growing as electrification expands the need for lightweight, heat-resistant, and dimensionally stable components in battery-related assemblies, charging systems, and under-hood modules. Aerospace and defense applications reinforce the market's high-performance core, where strict qualification standards and long service-life expectations reward materials that deliver consistent behavior under extreme thermal and mechanical stress.
Industrial and medical applications add a different growth pattern: lower volume per grade but higher specification precision, especially in semiconductor processing equipment, medical device components, and precision instrumentation. Across these segments, purchasing decisions are becoming more integrated. Procurement, engineering, and sustainability teams increasingly evaluate LCP grades against a combined scorecard of thermal performance, flow behavior, regulatory readiness, and feedstock credentials. The result is a market where multi-attribute value propositions outperform single-dimension price competition.
Supply Chain and Cost Structure Dynamics
Cost structure remains a defining constraint and opportunity. Main-chain LCP pricing carries a structural premium relative to high-temperature nylons because of batch polymerization economics and the reliance on specialty monomers sourced through narrow supply channels. This cost gap limits broad displacement into commoditized applications but protects margins for producers who can deliver differentiated performance, regional supply proximity, and qualification support. Capacity expansions in localized manufacturing footprints are increasingly important for reducing logistics risk, shortening lead times, and improving service levels for high-volume customers who require consistent supply more than marginal unit-cost savings.
The competitive response to cost and supply complexity has been uneven. Leading producers are expanding regional capacity, integrating feedstock strategy into product design, and shortening qualification timelines through standardized data packages. Smaller or less diversified players face the strain of raw material volatility, longer compliance cycles, and customer expectations that increasingly demand more than technical specifications. In this environment, the market's cost structure is not merely a pricing issue; it is a strategic variable that shapes regional supply strategy, customer partnerships, and the pace at which new grades can be commercialized.
Competitive Landscape and Leading Strategies
The main-chain LCP market is characterized by concentrated leadership, with a core group of producers capturing a substantial share of volume and value. The competitive field reflects both legacy formulation expertise and accelerating strategic maneuvering across capacity, acquisition, and sustainability-driven product development. Rather than competing purely on price, leading companies are competing on technical specificity, regional supply assurance, qualification speed, and feedstock strategy.
Among the most prominent participants, Celanese Corporation has positioned its Vectra and Zenite resin and compound portfolio around high-performance electronics, connectors, and automotive applications, emphasizing flow, heat resistance, and dimensional stability. Its recent commissioning of additional LCP production capacity in China reflects a strategic emphasis on local supply for electronics and 5G-related applications, shortening lead times and improving service responsiveness in a region that remains central to electronics demand growth. Polyplastics Co., Ltd. has built its LAPEROS brand around precision molding for semiconductors, medical technology, and automotive applications, and has advanced a biomass-balanced variant using a mass-balance approach with bio-derived raw materials. This move illustrates a broader competitive trend: sustainability is being incorporated as a product attribute rather than a separate communications exercise.
Sumitomo Chemical Co., Ltd. supplies Sumikasuper resins for electronics and high-heat applications, and its acquisition of an additional LCP neat resin business from Syensqo signals a deliberate effort to strengthen offerings in ICT and mobility applications. The transaction highlights a consolidation dynamic in which incumbents are acquiring formulation capability, customer relationships, and product breadth to accelerate positioning in high-growth applications. Toray Industries, Inc. manufactures SIVERAS main-chain LCP materials for electronics and high-frequency applications, with particular emphasis on films and precision components, reinforcing a strategy centered on specialized form factors rather than commodity resin volume. Solvay S.A. through Syensqo provides Xydar grades, including high-heat and flame-retardant variants for EV battery insulation and industrial uses, aligning its portfolio with thermal safety and electrification-driven demand. Ueno Fine Chemicals Industry, Ltd. focuses on main-chain LCP production for high-performance engineering plastics in electronics and other demanding sectors, while Kuraray Co., Ltd. offers main-chain LCP materials including films and fibers for electronics and high-strength applications, extending the material's reach into structural and functional formats beyond conventional molding resins.
The competitive landscape is evolving along several vectors. Consolidation is evident through targeted acquisitions that expand resin portfolios and deepen application coverage, particularly in ICT and mobility. Differentiation is increasingly based on formulation specificity, regulatory readiness, and sustainability-enabled product variants rather than generic performance claims. Regional supply strategy has become a competitive lever, as customers prioritize local or near-local production to mitigate logistics risk and improve responsiveness. At the same time, the market is not closing to new entrants entirely, but entry barriers are rising. Specialty monomer access, batch polymerization know-how, qualification relationships, and sustainability certification infrastructure all raise the threshold for meaningful market participation. The likely trajectory is continued concentration among established producers with diversified application coverage, while niche players survive by serving highly specialized grades or regional demand pockets that larger portfolios do not prioritize. Competitive success will increasingly depend on how effectively companies integrate technical performance with regulatory compliance, feedstock strategy, and localized supply reliability.
PW Consulting Chemical & Energy Research Center
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the main-chain LCP market is likely to follow three interlocking trends that will shape both opportunity and risk. First, demand growth will remain anchored in electrification, advanced electronics, and precision engineering, but the growth will be increasingly grade-specific. General-purpose thermal materials will face substitution pressure, while LCPs engineered for high heat, flame resistance, signal integrity, and precision molding will capture disproportionate value. This means commercial opportunity will concentrate in applications where LCP's structural advantages are difficult to replicate, especially in battery-related assemblies, high-frequency electronics, connector systems, and demanding medical or aerospace components.
Second, sustainability-enabled product architecture will move from differentiator to baseline expectation in premium procurement channels. Biomass-balanced grades, certified feedstocks, and mass-balance traceability will increasingly appear in supplier selection criteria, especially for multinational OEMs and tier suppliers with public decarbonization commitments. Companies that can pair verified sustainability credentials with consistent performance and fast qualification will gain access to a widening premium procurement segment. The risk is that sustainability claims become commoditized if they are not supported by credible mass-balance accounting, transparent disclosure, and robust qualification data.
Third, regional supply strategy and qualification speed will become more decisive in capturing volume. As raw material constraints persist and regulatory review lengthens, customers will favor suppliers that can reduce logistics risk, maintain consistent lot quality, and provide standardized compliance documentation. Capacity expansions in or near key demand regions, paired with efficient qualification support, will help secure long-term supply agreements. The downside risk is that supply expansion without feedstock diversification or regulatory readiness can strand capital in grades that lose competitiveness as customer expectations evolve.
Actionable Recommendations for Decision Makers
For manufacturers and material specifiers, the priority is to align grade selection with application-specific performance thresholds while building sustainability and regulatory readiness into the sourcing decision early. Evaluate LCP grades not only on thermal and flow properties but also on qualification timelines, feedstock credentials, and regional supply reliability. Where electrification, high-frequency electronics, or precision components are involved, prioritize grades with demonstrated performance in relevant thermal, flame, and dimensional stability conditions, and confirm that the supplier can support traceable documentation and accelerated qualification.
For investors and corporate strategists, the market rewards focused exposure to high-value applications and producers with diversified resin portfolios, regional supply footprints, and credible sustainability integration. Monitor consolidation activity, capacity additions, and product launches that deepen positioning in ICT, mobility, and precision medical or aerospace segments. Assess feedstock strategy and regulatory preparedness as leading indicators of commercial resilience, since these factors increasingly determine how quickly new grades can reach customers and how sustainably margins can be defended amid raw material volatility.
For procurement and supply chain leaders, the strategic question is no longer whether LCP delivers performance, but which supplier can deliver performance consistently under evolving compliance and sourcing expectations. Negotiate for data transparency, qualification support, and regional supply assurance alongside unit pricing. Build multi-grade sourcing strategies that balance performance-critical applications with cost-sensitive uses, and ensure that sustainability claims are supported by verifiable mass-balance or feedstock certification rather than generic messaging. Detailed segment-level volume patterns, regional demand distribution, and customized procurement or investment scenarios can sharpen these decisions significantly, and the complete market report provides the granular data needed to translate these strategic insights into concrete sourcing, investment, and product-development actions.
For detailed analysis of this topic, please visit the official page: Main-Chain Liquid Crystalline Polymer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com