

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive Adhesives Market: Why 6.01% CAGR and Regional Shifts Matter

The Automotive Adhesives Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global automotive adhesives market has established itself as a critical enabler of modern vehicle manufacturing, quietly transforming how cars are assembled, bonded, and performance-tested. Valued at approximately USD 6.65 billion in 2025, the sector has expanded steadily from a base of USD 4.97 billion in 2020, reflecting a compound annual growth rate of 6.01 percent through the forecast horizon extending to 2032. At that point, the market is projected to cross the USD 10 billion threshold, signaling a structural shift rather than a cyclical upturn. This trajectory is not merely a function of rising vehicle production volumes. It is being reshaped by material science breakthroughs, regulatory tightening, the electrification of powertrains, and a competitive landscape where consolidation and specialization are occurring simultaneously.
For executives, strategy teams, investors, and procurement leaders, the implications are significant. Adhesives are no longer peripheral consumables; they are strategic inputs that influence body-in-white integrity, battery pack durability, lightweight multi-material assembly, and compliance with environmental mandates. The market's concentration profile—with the top three players accounting for roughly 48.6 percent of revenue and the top five capturing approximately 60.2 percent—indicates a landscape where scale, certification, and application-specific expertise create meaningful barriers. Yet fragmentation persists in niche segments, regional manufacturing hubs, and emerging EV-specific formulations. Understanding where value is created, where margins are pressured, and where capability gaps open doors is essential for making informed capital and partnership decisions.
Market Snapshot and Core Challenges
Over the historical period from 2020 to 2025, the automotive adhesives market grew from USD 4.97 billion to USD 6.65 billion, a pace that accelerated as OEMs and tier suppliers increasingly adopted bonding technologies to replace mechanical fasteners, reduce weight, and improve crashworthiness. The forward trajectory through 2032 points to continued expansion, with year-on-year increments that reflect both volume growth and value migration toward higher-performance formulations. Revenue distribution across regions underscores a clear geographic rebalancing: Asia Pacific leads in aggregate demand, Europe maintains a substantial share driven by stringent safety and emissions standards, North America anchors high-value OEM and aftermarket applications, while Latin America and the Middle East and Africa collectively represent growing but still developing basins of opportunity.
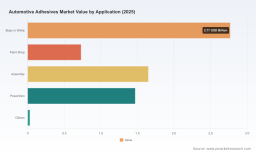
Segmentation by chemistry and application reveals where the market's center of gravity resides. Reactive and structural chemistries—including polyurethane, acrylic, epoxy, and silane-modified polymer systems—command significant share, reflecting the industry's need for durable, crash-resistant, and thermally stable bonds. Application-wise, body-in-white bonding represents the largest demand pool, followed by assembly, powertrain, and paint shop usage, with specialized electronics and sensor modules emerging as faster-growing niches. This distribution is not static; it is being re-drawn by vehicle architecture changes and manufacturing process automation.
Challenge One: Electrification-Driven Specification Complexity
The transition to electric vehicles has introduced a new layer of technical and regulatory complexity. Battery pack assembly now demands adhesives that meet functional safety expectations aligned with ISO 26262, alongside performance characteristics such as thermal stability, electrical insulation, and, increasingly, debonding-on-demand capabilities to support end-of-life recycling. Suppliers that cannot deliver certified, application-validated formulations risk exclusion from increasingly narrow supplier qualification lists. For manufacturers, this complexity raises the cost of validation, extends cycle times for new platform launches, and forces brittle dependencies on a small set of qualified chemistry providers.
Challenge Two: Regulatory Pressure and Emissions-Compliant Formulations
Low-VOC and water-based adhesive systems are no longer optional enhancements; they are becoming baseline requirements under evolving EU and US automotive emission directives. The shift imposes reformulation costs, can alter bonding performance profiles, and demands re-qualification of processes already in production. Companies that treat compliance as a checkbox rather than a product architecture principle may find themselves locked out of certain plants or facing costly retrofits. Conversely, those that embed low-emission design early can convert regulation into a differentiator, especially in European and North American assembly networks where procurement teams are explicitly scoring sustainability metrics.
Engineering Adhesives Market
Challenge Three: Supply Chain Timing and Regional Manufacturing Alignment
Just-in-time delivery expectations are intensifying as vehicle platforms become more customized and production footprints diversify. The establishment of specialized adhesive warehousing and regional distribution nodes—such as recent facility expansions in India to support growing EV and component manufacturing—illustrates how proximity, inventory strategy, and lead-time reliability are being re-evaluated. Companies that depend on distant, inflexible supply chains face higher working capital costs and greater disruption risk. Aligning formulation availability with regional manufacturing rhythms is becoming a competitive necessity rather than an operational nicety.
Key Drivers Reshaping the Market
Technology Innovation and Material Performance Ceilings
Advancements in structural adhesive chemistry are expanding the envelope of what bonding can achieve. Silane-modified polymer systems, next-generation epoxy platforms, and high-temperature resistant hot-melt and reactive formulations are enabling stronger, lighter, and more durable joints across mixed-material bodies. Recent product introductions targeting vibration damping, increased structural integrity, and display-component bonding demonstrate how chemistry is being tuned to specific vehicle subsystems rather than sold as generic industrial inputs. At the same time, adhesives engineered for electronics, lidar, and autonomous driving modules are gaining relevance as sensor suites proliferate, creating a parallel growth path beyond traditional metal-to-metal or metal-to-composite bonding. These innovations are not just performance upgrades; they are value-creation levers that let suppliers command premium positioning in safety-critical and electronics-intensive applications.
Policy and Regulatory Environment as a Market Filter
Regulatory frameworks are increasingly functioning as market filters rather than background conditions. IATF 16949 certification has become effectively mandatory for automotive adhesive suppliers seeking to remain in OEM supply chains, raising the quality management bar and compressing the list of eligible vendors. Simultaneously, low-emission formulation requirements are reshaping chemistry roadmaps, pushing manufacturers toward water-based, low-VOC, and reactive systems that satisfy both performance and environmental criteria. The effect is twofold: incumbents with mature certification infrastructure and reformulation capabilities gain a defensive moat, while new entrants must invest early in quality systems and compliance documentation to be taken seriously. Policy, in this context, is accelerating consolidation among qualified suppliers and raising the cost of market entry for undifferentiated players.
Electronic Adhesives Market
Demand-Side Shifts in Material Architecture and Platform Strategy
Vehicle architecture is moving toward mixed-material construction, where aluminum, high-strength steel, composites, and polymers are combined to optimize weight, cost, and crash performance. This shift increases reliance on adhesives that can handle dissimilar substrates, manage thermal expansion mismatches, and maintain structural continuity under dynamic loading. Body-in-white bonding remains the largest demand pool, but assembly and powertrain segments are expanding as manufacturers use adhesives to streamline line operations, reduce spot-welding dependencies, and enable new joining sequences. On the EV side, battery module and pack assembly has emerged as a distinct demand driver, pulling specialized formulations that balance mechanical strength with thermal and electrical considerations. Procurement behavior is also evolving: OEMs are increasingly seeking single-supplier or reduced-supplier strategies for adhesive families to simplify validation and logistics, which tends to favor suppliers that can offer broad, certified portfolios across multiple vehicle subsystems.
Supply Chain and Cost Structure Dynamics
Raw material volatility, energy costs, and formulation complexity are reshaping cost structures across the adhesives value chain. High-temperature resistant chemistries required for under-hood and powertrain applications depend on specialized feedstocks, and the shift toward low-emission systems can alter raw material baskets and processing requirements. At the same time, regional manufacturing expansion is changing logistics economics: closer proximity to assembly plants reduces freight exposure and improves service levels, but it also requires local inventories and demand-forecasting discipline. Companies that can balance formulation performance with cost-stable sourcing, and that invest in regional distribution to support just-in-time expectations, are better positioned to protect margins while meeting OEM service-level agreements. The broader effect is a market where cost leadership alone is insufficient; reliability, certification, and regional responsiveness are becoming equally weighted in supplier selection.
Competitive Landscape and Leading Strategies
The competitive field is defined by a core group of multinational suppliers with established automotive credentials, complemented by specialized players that compete on chemistry depth, application focus, or regional proximity. Henkel AG & Co. KGaA remains a prominent force with its Teroson structural adhesive portfolio, targeting body-in-white, EV battery assembly, and lightweight designs under IATF 16949 certification. Recent activity underscores a dual strategy of product refinement and geographic enablement: new structural adhesive series have been introduced to enhance integrity, durability, and vibration damping, while silane-modified polymer offerings for display components have extended the portfolio into electronics-adjacent applications. Henkel's regional warehouse expansion in India further illustrates a focus on just-in-time service for growing manufacturing hubs. The company's positioning is broad-spectrum and certification-led, aiming to serve as a multi-application partner across the vehicle.
PW Consulting Chemical & Energy Research Center
3M Company continues to leverage its Scotch-Weld structural and repair adhesives across OEM assembly, collision repair, and high-strength bonding contexts. Its strength lies in a well-recognized brand, broad application coverage, and a repair-market presence that complements original equipment supply. 3M's portfolio approach allows it to address both factory-floor and aftermarket demand, diversifying revenue streams and reducing dependence on any single platform cycle. Sika AG, through its Sikaflex and SikaPower lines, emphasizes crash-durable body shop bonding, exterior applications, and mixed-material joining, aligning closely with the trend toward multi-substrate architectures. Its strategy reflects deep application engineering and strong relationships in body-shop and structural bonding workflows.
H.B. Fuller Company focuses on low-emission water-based, hot-melt, and reactive adhesives for lightweight vehicle structures and aftermarket repair, positioning compliance and process flexibility as core selling points. Dow Inc.'s DOWSIL silicone adhesives and sealants target under-hood, electronics, and mobility applications, capitalizing on thermal and environmental resistance characteristics that are difficult to replicate with other chemistries. Arkema S.A. brings Bostik Pliogrip and EV battery adhesives to the market, with emphasis on composite and battery module bonding, aligning product development with electrification-driven demand. BASF SE's Acronal polymer dispersions address sound-damping and interior trim lamination, reflecting a focus on comfort,NVH, and interior assembly efficiency. Permabond LLC supplies anaerobic, cyanoacrylate, and epoxy adhesives for under-bonnet and high-temperature formed-in-place gasket applications, where thermal endurance up to 250°C is a decisive factor. DELO Industrial Adhesives GmbH has reinforced its automotive quality credentials with IATF 16949 certification and offers UV-cured and two-component adhesives for vehicle electronics, lidar, and autonomous driving modules, capturing value in sensor and electronics bonding. Jowat SE contributes hot-melt and dispersion adhesives for interior lamination and automated assembly, supporting high-speed production environments. Illinois Tool Works Inc. provides Plexus structural adhesives for EV battery assembly and lightweight bonding, aligning with electrification and weight-reduction priorities. Lord Corporation rounds out the field with Chemlok and engineered adhesives for vibration damping, motion management, and structural applications, addressing both performance and functional safety requirements in demanding contexts.
Strategic Positioning and Differentiation
Across this group, several differentiation patterns emerge. Certification and quality systems have become table stakes; suppliers that can demonstrate IATF 16949 compliance and functional safety alignment are better positioned to pass qualification gates. Chemistry breadth and application specificity are the next layer of advantage: companies that can cover body-in-white, battery, electronics, and interior applications with validated portfolios reduce the number of suppliers OEMs need to manage, which has real procurement value. Regional service capability—warehousing, technical support, and rapid response—translates directly into just-in-time reliability and can sway selection in cost-sensitive or high-service environments. Finally, sustainability-enabled formulations are shifting from reactive compliance to proactive differentiation, particularly where emission directives are tightening and where OEM sustainability scorecards influence purchasing decisions.
Evolving Market Structure: Consolidation, Fragmentation, and New Entrants
The market is experiencing simultaneous consolidation and fragmentation. Consolidation is visible in acquisitions that expand adhesive and sealant capabilities, such as PPG Industries' acquisition of Revocoat from the Axson Group to broaden automotive offerings. Such moves allow established coatings or materials players to add bonding technologies, capture cross-selling opportunities, and strengthen regional footprints. Fragmentation persists in specialized niches—electronics-grade UV-cured systems, high-temperature gasketing adhesives, and debonding-on-demand formulations for battery recycling—where smaller or more focused suppliers can win on technical performance and faster iteration cycles. New entrants face a steep climb because certification, validation, and regional service expectations are high, but opportunities exist where incumbents are slow to adapt to EV-specific requirements, low-emission chemistry, or localized supply expectations. In practice, the landscape is likely to tilt toward a core of large, certified suppliers with broad portfolios, complemented by targeted specialists and regional players that serve specific applications or geographies with agility.
Forward Outlook: Trends Shaping the Next Three to Five Years
The next several years will be defined by the convergence of electrification, advanced driver-assistance hardware, and sustainability mandates. One clear trajectory is the expansion of EV battery and high-voltage system bonding as a distinct growth engine. As platforms standardize around modular packs and as recycling considerations become more prominent, demand will grow for adhesives that balance structural and thermal performance with functional safety alignment and debonding-on-demand capability. This trend opens opportunities for suppliers that can deliver validated, recyclable-friendly formulations and provide the documentation and testing support that OEMs require. It also introduces risk: qualification cycles are long, and any performance or safety inconsistency can stall adoption at the platform level.
A second trend is the rise of electronics- and sensor-intensive bonding. Lidar, camera modules, and autonomous-driving hardware require adhesives with precise curing behavior, thermal stability, and fine-tolerance application control. UV-cured and two-component systems are well suited to these applications, and suppliers with strong electronics bonding expertise are positioned to capture value as sensor suites become standard across more vehicle segments. The commercial opportunity lies in pairing material performance with application engineering and process support, because integration complexity often matters as much as the adhesive itself. The uncertainty here stems from the pace of sensor normalization, cost pressure on electronic hardware, and the possibility that alternative mounting technologies could compete with adhesives in certain contexts.
A third trend is the regulatory and operational push toward low-emission, water-based, and low-VOC formulations as a baseline expectation. Companies that treat sustainability as embedded product architecture—rather than as a separate compliance line—can convert regulation into a competitive edge, particularly in European and North American plants where procurement teams are scoring emissions and VOC performance. The associated risk is reformulation cost and the potential for performance trade-offs that require re-validation; suppliers and buyers alike will need to manage the tension between compliance timelines and production continuity.
Across these trends, the commercial opportunity is not simply to sell more adhesive volume. It is to win influence over platform design, reduce supplier fragmentation for OEMs, and build regional service models that make bonding processes more reliable and repeatable. The risk side is equally clear: over-concentration in a small set of chemistries, lagging certification readiness, and inflexible supply chains can quickly erode a supplier's relevance as vehicle architectures and regulations evolve.
Actionable Guidance for Decision Makers
For Manufacturers and Tier Suppliers
Invest early in certification and quality infrastructure, including IATF 16949 alignment and functional safety documentation where relevant. Treat low-emission and water-based formulation development as a core product strategy rather than a reactive fix, and prioritize chemistries that can span multiple applications to reduce the supplier count OEMs must manage. Strengthen regional service capabilities—warehousing, technical support, and rapid issue resolution—to meet just-in-time expectations and to differentiate in competitive bid situations. Finally, build validation partnerships with OEMs on EV battery and electronics bonding applications before platform decisions lock in supplier lists, because late entry is difficult to remedy once qualification cycles close.
For Investors
Focus on suppliers with credible certification records, broad automotive portfolios, and demonstrated ability to scale regional service. Preference should lean toward companies that are expanding into EV-specific bonding, electronics-grade adhesives, and debonding-on-demand or recyclable-friendly formulations, as these areas align with the strongest demand tailwinds. Monitor consolidation activity that adds adhesive and sealant capabilities to existing materials or coatings platforms, since cross-selling and footprint expansion can accelerate revenue and margin improvement. Be cautious about purely volume-driven plays without certification depth or regional responsiveness, because those factors increasingly determine who retains preferred status in OEM supply chains.
For Procurement and Sourcing Leaders
Structure sourcing strategies to balance breadth and reliability: favor suppliers that can provide certified, multi-application portfolios while maintaining regional availability and low-emission compliance. Build transparency into qualification criteria so that sustainability metrics, functional safety documentation, and service-level commitments are weighed alongside unit cost. Encourage early engagement with adhesive suppliers during vehicle architecture planning, because bonding decisions made late in the process often force compromises on performance, logistics, or compliance. Where possible, pilot new formulations on non-critical assemblies first to validate process fit before scaling to structural or battery applications.
The automotive adhesives market is moving from a mature, volume-driven market into a more performance- and compliance-shaped environment where certification, chemistry specificity, regional service, and sustainability are decisive. The companies and investors that understand these shifts—and act on them with discipline—will be better positioned to capture the next phase of growth. For decision makers seeking deeper segmentation, detailed regional and application-level data, and customized strategic recommendations, the full market research report provides the granular evidence base needed to translate these trends into concrete plans and investment decisions.
For detailed analysis of this topic, please visit the official page: Automotive Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com