

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Short Fiber Reinforced Thermoplastic Market: Why the 2032 $3.8M Outlook Changes Strategy

Navigating the Short Fiber Reinforced Thermoplastic Composite Market: Strategic Trends and Commercial Opportunities
Market Landscape: Growth Trajectory Amid Structural Shifts
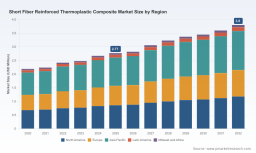
The short fiber reinforced thermoplastic composite market has established itself as a critical materials ecosystem, bridging the gap between traditional unreinforced polymers and heavier, more complex continuous fiber solutions. Over the historical period from 2020 through 2025, the sector demonstrated consistent expansion, reflecting steady adoption across manufacturing verticals that prioritize weight reduction, mechanical performance, and processing efficiency. The market’s evolution from a niche engineering substitute to a mainstream component material underscores a fundamental shift in how designers approach lightweighting and structural optimization.
Looking ahead to the forecast horizon of 2026 through 2032, the market is projected to sustain a compound annual growth rate of approximately 4.52 percent, culminating in a total revenue base that will meaningfully outpace the starting valuation of the current cycle. This growth trajectory is not merely a continuation of historical momentum; it is being reshaped by material science breakthroughs, regulatory pressures favoring recyclable and lightweight structures, and a recalibration of supply chain priorities. The convergence of these forces is creating a market that rewards players who can balance cost efficiency with tailored performance characteristics.
Despite the positive outlook, the industry faces several structural challenges that will define competitive outcomes over the next few years. First, the tension between fiber loading optimization and processability remains a persistent bottleneck. Short fiber composites offer significant stiffness and strength improvements over neat thermoplastics, yet achieving high fiber loadings without compromising melt flow, surface finish, or cycle time requires sophisticated compounding expertise and sometimes costly processing adaptations. Manufacturers must navigate this trade-off carefully, particularly when end-users demand both performance and cost parity with unreinforced alternatives.
Second, raw material volatility and feedstock availability continue to inject uncertainty into cost structures. The prices of glass and carbon fibers, as well as the engineering resins that serve as polymer matrices, are subject to fluctuations driven by energy costs, capacity constraints, and regional supply dynamics. These variables complicate long-term pricing strategies and can compress margins for compounders and converters who lack vertical integration or long-term supply agreements.
Third, the market is experiencing a gradual but decisive shift toward sustainability-driven material selection. While short fiber reinforced thermoplastics inherently offer recyclability advantages over thermoset composites, the industry must still address end-of-life processing, fiber recovery, and the environmental footprint of virgin fiber production. Regulatory frameworks and corporate sustainability targets are increasingly mandating verifiable lifecycle benefits, pushing material developers to innovate in bio-based reinforcements, recycled fiber integration, and design-for-disassembly principles.
Key Drivers Reshaping the Market
Technological Innovation and Material Performance Breakthroughs
The pace of compounding and formulation technology has accelerated, enabling more precise control over fiber length distribution, dispersion quality, and interfacial bonding between fiber and matrix. Advances in twin-screw extrusion, reactive compatibilization, and surface treatment chemistries are allowing manufacturers to push fiber loadings higher while maintaining manageable viscosity profiles. These improvements translate directly into parts that can replace metal components or continuous fiber assemblies in applications where absolute maximum strength is less critical than balanced stiffness-to-weight ratios and high-volume producibility.
Equally important is the evolution of multi-material and hybrid reinforcement strategies. Formulators are increasingly blending glass and carbon short fibers, or combining synthetic fibers with natural reinforcements, to tune cost and performance curves for specific use cases. This customization capability is expanding the addressable market beyond traditional heavy-duty structural components into sectors that previously relied on metal insertion molding or unreinforced engineering plastics. The ability to dial in mechanical, thermal, and dimensional stability characteristics at the compound level is turning short fiber reinforced thermoplastics into a more versatile design tool rather than a single-purpose material class.
Policy and Regulatory Environment as a Catalyst
Regulatory momentum is converging on two fronts that directly benefit short fiber reinforced thermoplastic composites: lightweighting mandates and sustainability requirements. In transportation and industrial equipment, efficiency standards continue to tighten, compelling OEMs to reduce mass without sacrificing safety or durability. Short fiber reinforced thermoplastics offer a practical pathway to weight reduction through part consolidation, thinner wall designs, and substitution of heavier metals, all while retaining compatibility with high-volume injection molding and extrusion processes.
On the sustainability side, policies promoting circular economy practices and extended producer responsibility are reshaping procurement criteria. Unlike thermoset composites, thermoplastic matrices can theoretically be reprocessed, and short fibers do not inherently preclude recycling streams. However, achieving credible circularity claims requires clear data on recyclability, fiber recovery economics, and the performance of recycled-content compounds. Regulatory pressure is therefore pushing both material suppliers and end-users to invest in lifecycle assessment, standardized testing, and transparent reporting, which in turn elevates the strategic value of compounds that can demonstrably reduce environmental impact without compromising functional requirements.
Demand-Side Shifts in End-Use Markets
Demand is being reshaped by a broader design philosophy shift toward multi-material architectures and smart component optimization. Engineers are increasingly selecting materials based on localized performance needs rather than defaulting to a single material across an entire assembly. This approach favors short fiber reinforced compounds in applications where ribbing, boss features, and moderate load-bearing requirements can be met efficiently without the cost and complexity of continuous fiber layup or metal machining. The result is a growing emphasis on application-specific compound design, where mechanical properties, moisture resistance, thermal stability, and surface appearance are tailored to the part’s functional environment.
At the same time, sectors such as transportation, electrical and electronics, and consumer goods are driving volume growth through different mechanisms. Transportation continues to be a dominant demand center as vehicle platforms pursue mass reduction and corrosion resistance. Electrical and electronics applications are benefiting from the need for flame-retardant, dimensionally stable, and lightweight housing and connector materials. Consumer goods and industrial equipment manufacturers are exploring short fiber reinforced thermoplastics for durability and aesthetic improvements in high-wear components. This diversified demand base reduces dependence on any single vertical and provides a buffer against cyclical downturns in individual sectors.
Supply Chain Reconfiguration and Cost Structure Evolution
Supply chain dynamics are undergoing a structural reorientation as manufacturers reassess resilience, proximity, and total cost of ownership. The post-pandemic emphasis on supply security has encouraged regionalization of compounding and conversion capacity, reducing reliance on distant supply nodes and shortening lead times for custom formulations. This trend favors compounders with flexible production assets and strong technical service capabilities, as they can respond more rapidly to design changes, pilot runs, and localized demand fluctuations.
Cost structures are also being reshaped by the interplay between resin pricing, fiber costs, and processing efficiency. While engineering resins such as polyamide and polybutylene terephthalate command premium pricing relative to commodity grades, their ability to deliver higher thermal and mechanical performance can justify the added material cost when part consolidation and metal replacement are achieved. Similarly, the choice between glass and carbon fiber reinforcement creates a spectrum of cost-performance options, allowing formulators to align material economics with the criticality of the application. Companies that can optimize fiber-matrix compatibility, minimize scrap rates, and integrate compounding with downstream conversion are gaining a meaningful cost advantage in a market where margin preservation is increasingly tied to process excellence rather than raw material arbitrage alone.
Thermoplastic Composites Market
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate concentration, with a handful of established compounders and specialty material suppliers capturing a meaningful share of differentiated, higher-performance formulations. Leading players have built their positions not simply on volume, but on technical depth, application engineering support, and the ability to deliver consistent quality across complex short fiber reinforced systems. The most successful companies treat compounding as a service capability, working closely with molders and design engineers to match fiber type, loading, and matrix selection to the functional, regulatory, and economic requirements of each part.
A representative group of companies illustrates the diversity of strategic approaches. One major U.S.-based manufacturer focuses on a broad portfolio of short fiber reinforced formulations with fiber loadings ranging from 10 to 50 percent, spanning commodity and engineering resins intended for semi-structural components. This breadth allows the company to serve a wide range of customers who need ready-to-process compounds with predictable behavior across multiple resin systems. Its competitive advantage lies in offering a library of standardized yet customizable options that reduce development time for parts requiring moderate reinforcement without the lead time of fully bespoke formulations.
A German producer takes a more bespoke approach, engineering tailor-made thermoplastic composites across a spectrum of fibers including glass, carbon, aramid, and natural fibers, and extending up to high-performance polymer matrices. This strategy positions the company in applications where standard compounds are insufficient and where performance, chemistry compatibility, or extreme environmental resistance dictate a custom solution. Its differentiation stems from deep formulation expertise and the ability to adjust fiber-matrix interactions for demanding conditions, making it a preferred partner for engineering teams that require precise control over material behavior.
A U.S.-based supplier specializing in short glass fiber reinforced compounds, offering chopped and milled glass fibers in a range of lengths across commodity and engineering thermoplastics, emphasizes structural and high-performance part solutions. This focus on controlled fiber geometry and consistent dispersion supports applications where predictable mechanical output and processing stability are critical. The company’s positioning reflects a practical, application-oriented approach that appeals to manufacturers seeking reliable reinforcement without the need for extensive material re-engineering.
The competitive environment is evolving along multiple vectors. Consolidation activity is expected to intensify as larger players pursue capability expansion, geographic reach, and access to specialized formulation know-how. At the same time, market differentiation is becoming more granular; companies are unlikely to win on price alone because the value proposition increasingly depends on engineering support, consistent quality, and the ability to solve application-specific challenges. New entrants and niche specialists may find openings in high-growth subsegments that require uncommon fiber combinations, bio-based or recycled content, or exceptional processing characteristics for advanced molding technologies. Ultimately, the market is moving toward a structure where scale provides cost leverage, but technical service and formulation agility determine customer loyalty and premium positioning.
Future Outlook: Trends and Commercial Implications
The next three to five years are likely to be defined by a tightening integration between material design and application engineering. Short fiber reinforced thermoplastic composites will increasingly be specified as part of optimized multi-material systems rather than as standalone replacements. This will elevate the importance of simulation-driven material selection, where finite element analysis and process modeling guide fiber loading, orientation, and matrix choice before tooling is committed. Suppliers that offer validated data packages, application notes, and process window guidance will be better positioned to shorten development cycles and reduce the risk of redesign.
PW Consulting Chemical & Energy Research Center
Sustainability and circularity will shift from aspirational goals to procurement requirements. Buyers will increasingly request evidence of recyclability, recycled content, and reduced carbon intensity, and materials that can integrate recovered fibers or bio-derived reinforcements without sacrificing performance will capture premium interest. Commercial opportunities will emerge for compounders that can deliver certified, drop-in sustainable formulations compatible with existing molds and processing equipment, thereby removing the friction that often accompanies material substitution. There is also potential in design-for-disassembly architectures, where short fiber reinforced thermoplastics are selected specifically because they can be separated and reprocessed more readily than thermoset counterparts.
A third trend is the continued expansion of processing versatility, particularly around high-speed injection molding, extrusion, and hybrid manufacturing flows. Improved fiber length control and dispersion will allow molders to produce parts with more consistent mechanical properties and fewer defects, expanding the range of geometries that can be economically molded. This trend opens opportunities in sectors that value part complexity and consolidation, such as under-the-hood automotive components, electronic housings, and industrial equipment where weight, durability, and cost must be balanced simultaneously. The risk is that processing windows can become narrower as fiber loadings and matrix performance increase, so the commercial winners will be those that pair advanced compounds with clear processing guidance and technical support.
Potential risks include raw material cost spikes, especially if fiber or resin supply tightens in key regions, and regulatory divergence that complicates global product rollouts. Another uncertainty lies in the pace of recycling infrastructure development; if post-industrial and post-consumer recovery systems do not scale in line with material adoption, circularity claims may remain limited to closed-loop or industrial scrap scenarios, constraining the breadth of sustainability-driven demand. Companies that diversify fiber and resin sources, invest in application-specific validation, and build transparent sustainability data will be better insulated against these uncertainties.
Strategic Actions for Decision-Makers
For Manufacturers and Compounders
Prioritize formulation agility as a core competitive asset. The ability to rapidly adjust fiber type, length, loading, and surface treatment in response to application requirements will differentiate suppliers in a market where standard compounds face increasing price scrutiny. Investing in compounding process control, dispersion quality, and consistent lot-to-lot performance will reduce customer risk and strengthen repeat business. Manufacturers should also expand technical service capabilities so that material recommendations are tied directly to part design, processing conditions, and end-use environment, not merely to generic property tables.
Develop a clear sustainability roadmap that connects material choices to verifiable lifecycle benefits. This includes exploring recycled and bio-based fiber options, documenting recyclability and recovery pathways, and aligning product offerings with the procurement criteria that OEMs and industrial buyers are beginning to enforce. A credible sustainability position can become a differentiator in bids where performance is comparable but environmental attributes influence selection.
For Investors
Focus on companies that combine scale with technical differentiation rather than volume alone. In a market where margin preservation depends on formulation expertise, application support, and process efficiency, businesses that can command premium pricing through value-added services are more resilient than undifferentiated commodity players. Pay attention to capabilities in high-performance matrices, hybrid fiber systems, and sustainable content, as these are likely to command stronger demand in segments pursuing lightweighting and circularity simultaneously.
Assess supply chain resilience and geographic positioning as part of the investment thesis. Regional compounding assets, diversified feedstock access, and strong customer technical relationships reduce exposure to logistics disruptions and price volatility. Investors should also evaluate the breadth of application exposure, since a diversified demand base provides stability when individual verticals face cyclical pressure or regulatory shifts.
Worldwide Advanced Thermoplastic Composite Market
For Procurement and Sourcing Leaders
Treat short fiber reinforced thermoplastic selection as a system-level decision rather than a simple material swap. Engage early with compounders and converters to align fiber loading, matrix choice, and processing parameters with part geometry, performance targets, and cost objectives. Early collaboration reduces the risk of suboptimal properties, rework, or processing bottlenecks that can erode the apparent cost advantage of a reinforcement strategy.
Require transparent data on processing windows, mechanical consistency, and sustainability attributes. Specification documents should encompass not only baseline mechanical properties but also tolerance to processing variation, moisture sensitivity where relevant, and available recycled or bio-based content options. Building these requirements into procurement criteria encourages suppliers to compete on overall value, including reliability and lifecycle performance, rather than on unit price alone.
For organizations seeking a more detailed segmentation view, competitive benchmarking, and tailored scenario planning across specific resin systems, fiber types, applications, and regional dynamics, the full PW Consulting research report provides the granular data and customized guidance needed to translate these strategic themes into concrete decisions.
For detailed analysis of this topic, please visit the official page: Short Fiber Reinforced Thermoplastic Composite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com