

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Stone Paper Market: Why 6.5% CAGR and Packaging Demand Redefine the 2032 Outlook

The Stone Paper Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Core Challenges
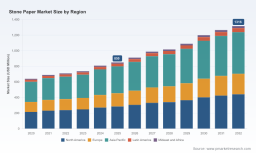
The stone paper market has evolved from a niche sustainable material into a measurable commercial segment with clear growth trajectory. Valued at 640.0 million in 2020, the market expanded to 737.24 million by 2023 and reached 850.0 million in 2025, reflecting a compound annual growth rate of approximately 6.5 percent through 2032. By the end of the forecast period, revenue is projected to approach 1.3 billion, signaling sustained commercial momentum rather than short-term experimentation. This trajectory is anchored in a tangible shift away from conventional pulp-based and petroleum-derived alternatives, particularly in application areas where durability, moisture resistance, and reduced fiber dependency align with procurement priorities.
The composition of demand further clarifies where commercial attention is concentrating. Packaging-related uses represent the largest application share, followed by labeling and self-adhesive formats, indicating that stone paper is increasingly evaluated not as a general-purpose substitute but as a purpose-fit material for specific functional and sustainability requirements. On the supply side, the market is moderately consolidated. The top three participants account for roughly 35 percent of revenue, while the top five collectively hold just above 52 percent. This concentration suggests that scale advantages, formulation expertise, and regulatory readiness are becoming differentiating factors, even as regional demand continues to diversify across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the market is navigating several structural pressures that will shape profitability and adoption speed over the next few years.
The first challenge lies in cost arithmetic and raw material sensitivity. Stone paper does not eliminate cost exposure; it shifts it. Production depends on mineral fillers and resin systems, meaning margin stability is tied to feedstock pricing and energy inputs rather than fiber markets. When input costs rise, manufacturers must absorb volatility or pass it through to buyers who may still compare stone paper against established alternatives on price alone. This creates a persistent tension between sustainability positioning and commercial competitiveness, especially in price-sensitive segments where environmental claims must be matched by total cost-of-ownership logic.
The second challenge is performance perception versus application reality. Stone paper offers distinct advantages in waterproofing, durability, and tree-free production, but it is not a universal replacement for every paper grade. Adoption depends on matching the material to the right use case, printing conditions, converting requirements, and end-of-life pathways. Overgeneralization can create disappointment in contexts where stone paper underperforms expectations, while selective deployment can build credible reference accounts and repeat demand. The market is therefore moving through an inflection point where technical education and application-specific validation matter as much as regulatory tailwinds.
The third challenge is regulatory and standards complexity. The same policies that accelerate interest in stone paper also raise the bar for substantiation. Extended producer responsibility frameworks, single-use packaging obligations, and recycling-target-driven procurement increasingly require documented environmental performance rather than broad eco-friendly positioning. In practice, this means manufacturers and buyers must navigate varying regional expectations, verify food-contact suitability where relevant, and ensure that sustainability claims hold up under procurement scrutiny. Companies that treat compliance as a core capability rather than a backend activity are better positioned to convert demand into durable contracts.
Core Drivers of Market Change
The expansion of the stone paper market is not driven by a single force. It is being shaped by overlapping technical, regulatory, behavioral, and supply-side dynamics that reinforce one another in specific application spaces.
Technological Innovation and Material Refinement
Material formulation remains the most direct lever of market progress. Recent developments point to a pattern of incremental but commercially meaningful refinement rather than sudden breakthrough rhetoric. For example, Taiwan Lung Meng completed installation of an advanced production line that reduced carbon footprint by 15 percent while improving efficiency, reinforcing that process optimization is becoming a competitive necessity as buyers evaluate environmental impact alongside operational performance. Similarly, TBM expanded its LIMEX-based offerings with a sheet designed for global packaging applications, emphasizing durability and sustainability in a format that aligns with converting and handling requirements. These moves matter because they bridge the gap between laboratory-level green promise and production-ready reliability.
At the same time, product launches are becoming more application-specific. Shenzhen Stone Paper introduced wholesale stone powder synthetic paper for vegetable packaging in the printing and packaging industry, illustrating how stone paper is being tailored to fresh-produce and food-adjacent contexts where moisture resistance, printability, and material safety are critical. This kind of targeted innovation increases the likelihood of adoption because it reduces the burden on buyers to adapt the material to their processes. The broader lesson is that stone paper's commercial relevance is increasing as suppliers narrow the gap between material properties and real-world packaging needs.
Policy and Regulatory Dynamics
Regulatory pressure is acting as a demand catalyst, particularly in regions where packaging waste and single-use materials are being re-priced through policy. Extended producer responsibility policies for packaging and printed paper in North America and Europe are encouraging organizations to evaluate stone paper as a plastic alternative that can support recycling targets and reduce single-use plastic waste. In parallel, California's EPR regulations for single-use packaging require producers to bear recycling costs, accelerating adoption of lower-impact alternatives by changing the economic calculus of material selection.
These developments do not automatically translate into demand, but they alter procurement logic. When producers internalize end-of-life costs, materials with lower embedded environmental liability become more attractive in business cases that previously favored the cheapest upfront option. This regulatory context is especially relevant for packaging and labeling applications, where compliance exposure is high and sustainability commitments are increasingly tied to measurable policy outcomes rather than voluntary branding.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand is also being reshaped by procurement behavior. Corporate buyers are increasingly treating sustainable packaging as an operational requirement rather than a differentiator, particularly when customer expectations, retail specifications, or internal targets push them toward reduced plastic use and lower environmental impact. Stone paper is benefiting from this shift because it can be presented as a tree-free, waterproof, and durable option with clear narrative appeal, especially in labeling, retail packaging, and industrial applications where material performance must coexist with sustainability storytelling.
Importantly, demand growth is strongest where the value proposition is concrete. Labeling and adhesive-backed formats, for instance, benefit from stone paper's durability and moisture resistance, while packaging applications gain from its alternative-to-plastic positioning. This suggests that adoption will continue to be opportunistic and segment-specific rather than uniform, with the most successful deployments tied to contexts where performance and policy alignment reinforce each other.
Supply Chain and Cost Structure Dynamics
The cost environment for stone paper production is influenced by the pricing of key raw materials, especially calcium carbonate. Recent pricing signals show meaningful regional variation, with calcium carbonate prices in the USA reaching 437 USD per metric ton in March 2026, the European price index averaging 0.33 USD per kilogram in May 2026, and Chinese prices at 317.10 USD per metric ton FOB in April 2026. These differences matter because they shape regional competitiveness and sourcing strategy.
Asian-based producers, for example, benefit from comparatively lower feedstock costs, which can support price competitiveness in export-oriented or regionally focused operations. European and North American producers, by contrast, must manage higher input costs while still meeting local regulatory and customer expectations. The net effect is that supply chain strategy is becoming a differentiator: companies that secure stable feedstock access, optimize formulation ratios, and manage energy intensity are better positioned to protect margins without sacrificing performance. In this environment, cost leadership is less about raw price cutting and more about input stability, process efficiency, and formulation discipline.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small group of focused manufacturers with differentiated positioning, alongside ongoing room for specialization and regional expansion. Taiwan Lung Meng, TBM, and Shenzhen Stone Paper each illustrate a different pathway to commercial relevance.
Strategic Positioning and Differentiation
Taiwan Lung Meng is positioned around tree-free, waterproof stone composite material based on calcium carbonate and non-toxic resin, serving packaging, labels, and stationery. Its Cradle-to-Cradle certification and export presence across more than 40 countries indicate a strategy rooted in verified sustainability credentials and international reach. In a market where claims must withstand procurement scrutiny, certification and export scale can function as trust multipliers.
Worldwide Flexible Stone Market
TBM is building its case around LIMEX mineral paper for packaging, with emphasis on food and non-food applications and eco-friendly properties. Its recent activities suggest a dual strategy: expanding product formats for global packaging use while also engaging broader corporate decarbonization ecosystems. The memorandum of understanding with Vietnam's FPT Group in August 2025, aimed at supporting corporate decarbonization efforts, reflects an approach that connects material offering with wider sustainability programs rather than treating stone paper as a standalone product transaction.
Shenzhen Stone Paper is pursuing customization and food-contact-safe formulations, targeting industrial and retail packaging with rich mineral paper and high-durability labels. Its wholesale stone powder synthetic paper for vegetable packaging indicates a strategy focused on application-specific solutions, where formulation control and customization can create defensible accounts in niche but commercially meaningful segments.
Market Structure and Evolution Trends
The market is likely to evolve along three interconnected lines. First, consolidation pressure may increase as scale, compliance readiness, and cost control become more important, especially in applications where buyers require dependable supply and documented performance. Second, segmentation will probably deepen, with more specialized offerings for food packaging, labeling, and industrial uses, because generic stone paper positioning is increasingly insufficient for complex procurement decisions. Third, new entrants may find traction not by challenging incumbents directly across all applications, but by targeting specific regional cost advantages, formulation needs, or niche packaging requirements.
This does not imply a winner-take-all structure. Instead, it suggests a landscape where advantage accrues to companies that can combine credible environmental credentials, application-fit formulation, and stable input economics. SMEs and regional players can still compete by serving localized demand or specialized converting needs, while larger or more globally connected participants can leverage certification, export reach, and process efficiency.
Future Outlook: Trends and Commercial Implications
Over the next three to five years, the stone paper market is likely to be shaped by trends that reward precision, credibility, and supply chain discipline.
Trend 1: Application-First Adoption Will Outpace Broad Substitution Narratives
The market will probably move further toward use-case-led deployment. Packaging, labeling, and adhesive applications will continue to generate the strongest pull because they align with stone paper's functional strengths and with regulatory pressure on plastic alternatives. Broad claims that stone paper can replace conventional paper across the board will become less persuasive as buyers demand evidence in specific conditions. Commercially, this creates opportunity for suppliers and end-users who invest in application validation, pilot programs, and reference deployments rather than relying on category-level sustainability messaging.
PW Consulting Chemical & Energy Research Center
Trend 2: Regulatory Pressure Will Keep Raising the Stakes for Substantiation
Policy momentum in packaging and printed paper is expected to intensify the need for credible documentation. Extended producer responsibility and single-use packaging regulations will continue to shift cost considerations toward materials that support recycling targets and reduce disposal liability. This will advantage participants that can clearly articulate environmental performance, food-contact suitability where needed, and recycling or end-of-life compatibility. The commercial implication is that sustainability claims will increasingly need to be operationalized into procurement specifications, not just marketing narratives.
Trend 3: Regional Cost Dispersion Will Shape Sourcing and Competitive Positioning
Because calcium carbonate pricing varies by region, competitive dynamics will remain geographically uneven. Asian producers may retain feedstock cost advantages, while North American and European players will need to compete on efficiency, certification, local compliance alignment, and service differentiation. Procurement teams may also increasingly consider regional sourcing as part of broader supply chain resilience and carbon-reduction strategies. For investors and manufacturers, this means that feedstock access, formulation control, and regional regulatory fit will be central to margin stability and market access.
Worldwide Natural Stone Market
Potential risks and uncertainties should not be understated. Raw material price volatility can still compress margins if not managed through contracts, formulation adjustments, or efficiency gains. Performance misapplication remains a risk if stone paper is positioned where it does not fit technical requirements. In addition, the regulatory environment can evolve in ways that change the relative attractiveness of different materials, especially if recycling infrastructure, compostability rules, or packaging compliance definitions shift. These uncertainties do not undermine the market's direction, but they do require active monitoring and scenario planning.
Strategic Implications for Decision-Makers
For Manufacturers and Material Suppliers
- Prioritize application-specific differentiation. Develop formulations and product formats that solve concrete packaging, labeling, or adhesive challenges rather than competing on generic eco-friendly positioning.
- Treat process efficiency as a market-facing capability. Production improvements that reduce carbon footprint and improve yield are not just internal gains; they support pricing resilience and customer trust in a market where both cost and sustainability claims are scrutinized.
- Strengthen documentation and compliance readiness. Certification, food-contact safety where relevant, and clear end-of-life or recycling alignment can become decisive in procurement decisions, especially under extended producer responsibility and single-use packaging obligations.
For Investors and Strategic Backers
- Focus on players with defensible feedstock strategy and formulation expertise. Cost volatility and performance fit are the principal swing factors, so businesses that can manage input economics and tailor material properties to real applications are more likely to sustain competitiveness.
- Watch for consolidation and specialization signals. Moderately concentrated markets with clear application leadership may present acquisition, partnership, or capacity-extension opportunities, especially where regional cost structures or certification capabilities differ.
- Assess regulatory exposure by region. Procurement shifts driven by EPR and single-use packaging rules can accelerate adoption in some markets faster than others, creating uneven but potentially high-value opportunities.
For Procurement and Business Leaders Evaluating Stone Paper
- Match the material to the task. Evaluate stone paper against the specific functional requirements of the application, including moisture exposure, converting needs, printability, durability, and end-of-life expectations, rather than adopting it as a blanket paper replacement.
- Use total cost and compliance logic in the business case. Where recycling costs, single-use obligations, or packaging compliance raise the cost of conventional options, stone paper's value may be strongest when assessed across the full procurement and disposal picture.
- Demand evidence and reference use cases. Ask for application-appropriate testing, food-contact compatibility where relevant, and documented environmental performance to ensure that procurement decisions are based on verifiable attributes.
Conclusion
The stone paper market is moving from early-stage curiosity to a more structured commercial segment defined by application fit, regulatory pressure, and input economics. Growth to nearly 1.3 billion by 2032 is plausible within the current trajectory, but the more important question for decision-makers is not whether the market is expanding, but where expansion will be most profitable and durable. The strongest opportunities are likely to emerge where material performance, sustainability substantiation, and regional cost dynamics align in packaging, labeling, and adhesive applications. Companies that build differentiation through formulation, process efficiency, certification, and targeted use-case validation are better positioned to convert momentum into repeatable commercial advantage. For leaders seeking to act on these dynamics with greater precision, more granular segmentation data and customized strategic guidance will be essential to move from directional confidence to execution-ready decisions.
For detailed analysis of this topic, please visit the official page: Stone Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com